
Where It All Began
The modern concept of tracking ultra-high-net-worth individuals emerged in the late 1990s, when wealth managers and private banks realized they needed a way to quantify their most lucrative clients. Before then, "rich" was a relative term—someone with $10 million in Manhattan was middle-class; in Dallas, it made you a local power player. But as global capital flows accelerated, banks like UBS and Credit Suisse began publishing reports on the how many UHNWIs in US and worldwide, defining the threshold at $30 million in liquid assets. The first estimates put the number around 20,000 in the US by 2000. That figure seemed astronomical at the time, but it was a drop in the bucket compared to what was coming. The early 2000s were a proving ground. The dot-com bubble burst, but the survivors—those who had diversified into real estate or private equity—emerged stronger. The Bush-era tax cuts of 2001 and 2003 had already begun eroding top marginal rates, but the real inflection point was the 2008 financial crisis. While Main Street reeled, Wall Street’s ultra-wealthy not only survived but thrived. Banks like Goldman Sachs and Morgan Stanley handed out bonuses that turned traders into instant millionaires. Private equity firms, which had been flying under the radar, suddenly became household names as they scooped up distressed assets. The question how many UHNWIs in US after 2008 wasn’t just about recovery—it was about who had been playing a different game all along.The Early Signs
By 2010, the cracks were showing. Occupy Wall Street chanted "We are the 99%", but the data told a different story: the top 1% held 35% of all privately held wealth, up from 25% in 1989. The ultra-high-net-worth tier was no longer just the preserve of old-money families. Tech entrepreneurs like Mark Zuckerberg and Elon Musk were rewriting the rules, proving that wealth could be created in a garage—or a Silicon Valley loft—without decades of corporate climbing. Meanwhile, the tax code was being rewritten to favor the wealthy. The 2012 "Buffett Rule" proposal, which suggested taxing the rich at higher rates, died in Congress. The message was clear: the system was rigged to keep wealth where it was. The final nail in the coffin came with the 2017 tax overhaul. The corporate rate dropped to 21%, and pass-through deductions allowed business owners to pay even lower rates. For the ultra-rich, it was a windfall. The number of UHNWIs in the US began climbing at an unprecedented rate. By 2019, estimates from Knight Frank and Wealth-X put the figure at over 300,000. The pandemic only accelerated the trend. While small businesses shuttered, the ultra-wealthy saw their net worth surge by $5.2 trillion in 2021 alone, according to Oxfam. The question how many UHNWIs in US was no longer academic—it was a political and economic fault line.The Turning Point
The moment the ultra-high-net-worth landscape shifted irrevocably wasn’t a single event but a series of policy decisions that created a feedback loop. The 2017 tax cuts weren’t just about lowering rates—they were about rewriting the rules of wealth accumulation. Capital gains taxes dropped, estate taxes were relaxed, and the carried interest loophole remained untouched. The result? Wealth became self-perpetuating. A hedge-fund manager could now pass their fortune to heirs with minimal tax burden. A tech founder could sell a company, take a small salary, and live off capital gains. The system wasn’t just favoring the rich—it was designing them."The ultra-rich don’t just benefit from economic growth—they engineer it. And when you give them the tools to pass wealth across generations with almost no friction, you don’t just get more billionaires. You get a permanent class." — Gabriel Zucman, economist and author of The Triumph of InjusticeWhat made this turning point different was the speed. In the past, wealth took generations to accumulate. Today, it takes decades—or even a single market cycle. The rise of alternative assets like private credit, venture capital, and even NFTs (briefly) created new pathways to ultra-high-net-worth status. The question how many UHNWIs in US became a proxy for a larger debate: Is this a meritocracy, or is it a system where the rules are written by those who already have the most?
The Build-Up, Year by Year
| Period | What Happened |
|---|---|
| 2000–2008 | Pre-crisis boom: UHNWI count grows from ~20,000 to ~30,000 as private equity and hedge funds expand. The financial sector becomes the primary wealth-creation engine. |
| 2009–2016 | Post-crisis recovery favors the wealthy. The number of UHNWIs stabilizes but begins rising again as tech valuations surge. The first wave of "new money" enters the ranks. |
| 2017–2020 | Tax overhaul and stock market rally fuel explosive growth. The count jumps from ~300,000 to over 400,000 by 2020. SPACs and crypto briefly mint new UHNWIs at an unprecedented rate. |
| 2021–2023 | Pandemic wealth effect: UHNWIs gain $5.2 trillion collectively. Real estate and private markets become the dominant wealth stores. The definition of "ultra-high-net-worth" expands to include alternative assets. |
| 2024 (Projected) | Slowdown in public markets, but private wealth continues growing. The number of UHNWIs may stabilize around 420,000–450,000, with a shift toward global diversification (e.g., second passports, offshore holdings). |
Lessons From the Journey
- Wealth creation is no longer linear. The old model—work hard, save, invest—still applies, but the returns are asymmetric. The ultra-rich don’t just earn money; they leverage it in ways that create outsized gains.
- The tax code is the ultimate accelerator. Every major policy shift in the past 20 years has favored the wealthy. The question how many UHNWIs in US is directly tied to how aggressively (or not) the government taxes capital.
- Liquidity is the new currency. Cash is no longer king—access to private markets, alternative investments, and offshore structures is what separates the ultra-wealthy from the merely rich.
- The definition of "wealth" is evolving. Traditional metrics (stocks, bonds, real estate) are being supplemented by illiquid assets like art, wine, and even digital collectibles. This makes tracking how many UHNWIs in US even harder.
Where Things Stand Today
As of 2024, the most widely cited estimates place the number of ultra-high-net-worth individuals in the US between 420,000 and 450,000, depending on the source and definition of "net worth." Wealth-X and Knight Frank both report figures in this range, though their methodologies differ—some include only liquid assets, while others factor in illiquid holdings like private businesses. What’s clear is that the growth curve has flattened slightly in the past two years, not because wealth is disappearing, but because the barriers to entry have risen. The ultra-rich are no longer just getting richer—they’re getting more strategic. Offshore accounts, family trusts, and private investment vehicles are now standard tools in their arsenal. The most striking trend isn’t the raw numbers but the geographic and demographic shifts. The Northeast and California still dominate, but Florida and Texas have surged as tax-friendly havens. The average age of a UHNWI is dropping—tech founders in their 30s and 40s now outnumber traditional corporate executives. And while the public still fixates on billionaires, the real action is in the $30 million to $100 million bracket, where private wealth managers and family offices are the gatekeepers. The question how many UHNWIs in US today isn’t just about counting names—it’s about understanding the invisible networks that sustain them.
Conclusion
The story of ultra-high-net-worth individuals in the US isn’t just about money. It’s about power. The question how many UHNWIs in US reveals a system where wealth begets more wealth, where policy decisions are made by those who benefit most from them, and where the gap between the haves and have-nots grows wider with each passing year. The numbers themselves—400,000, 450,000, whatever the final tally—are less important than what they represent: a society where the rules of the game are written by a tiny fraction of the population. The ultra-rich don’t just live differently; they operate under a different set of economic laws. The next decade will test whether this model can sustain itself. Will the number of UHNWIs keep rising, or will political pressure finally force a reckoning? One thing is certain: the answer to how many UHNWIs in US won’t just be a statistic. It will be a reflection of who we are as a country—and who we’re willing to let write the rules.Comprehensive FAQs
Q: What exactly defines an ultra-high-net-worth individual (UHNWI) in the US?
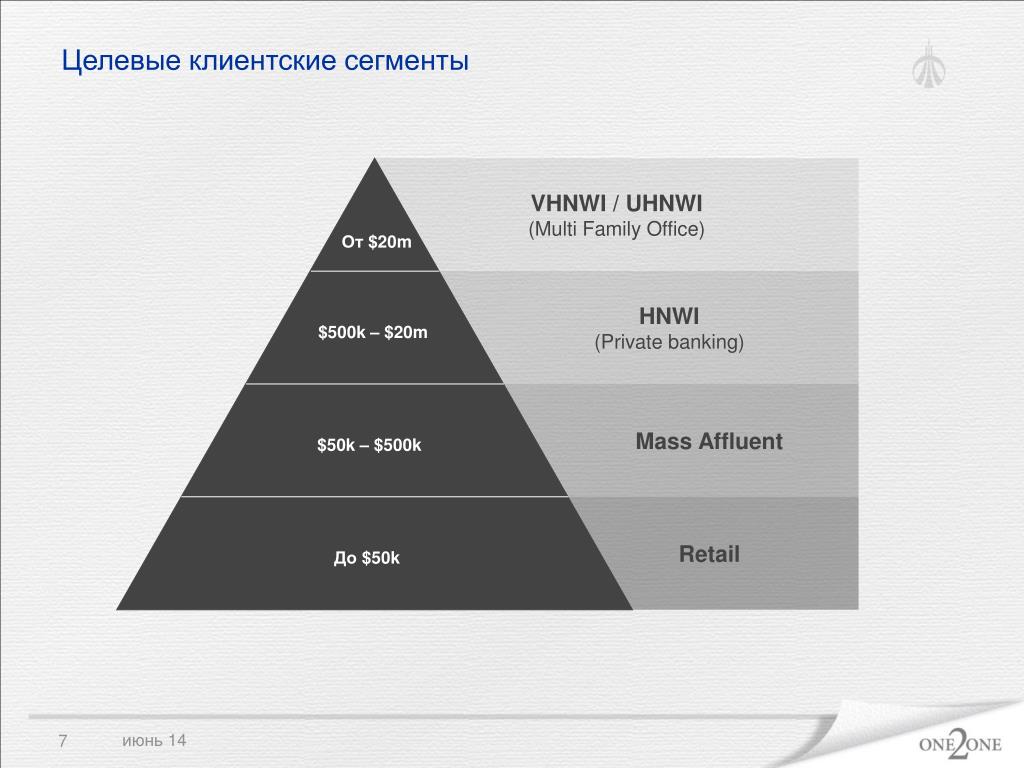
Most sources define a UHNWI as someone with $30 million or more in liquid assets, though some firms use $50 million as the threshold. The key distinction is that UHNWIs are not just "rich"—they have enough wealth to access private banking, family offices, and alternative investments that are off-limits to the merely affluent.
Q: How does the US compare to other countries in terms of UHNWI count?
The US consistently leads globally, with estimates suggesting it accounts for 30–40% of all UHNWIs worldwide. China is a distant second, followed by Japan and Germany. The US’s dominance stems from its stock market, tax policies favoring capital gains, and the concentration of global tech and finance industries in cities like New York, San Francisco, and Austin.
Q: Are there more UHNWIs today than in previous decades?
Absolutely. In the 1990s, the US had fewer than 20,000 UHNWIs. By 2024, that number has grown 20-fold, driven by tax policy, stock market performance, and the rise of new wealth-creation pathways like private equity, venture capital, and alternative assets. The growth isn’t just quantitative—it’s qualitative, with new sectors (tech, crypto, influencer economy) contributing to the ranks.
Q: How do UHNWIs typically accumulate their wealth?
Most UHNWIs today fall into one of four categories:
- Entrepreneurs/Founders: Tech, biotech, and finance founders (e.g., Zuckerberg, Musk) who build and sell companies.
- Investors: Hedge-fund managers, private-equity partners, and angel investors who leverage capital for outsized returns.
- Legacy Wealth: Heirs to family fortunes who manage trusts and private holdings across generations.
- Alternative Assets: Collectors of art, wine, rare assets, and even digital assets who benefit from illiquid markets.
Q: What’s the biggest misconception about UHNWIs in the US?
The biggest myth is that ultra-high-net-worth status is earned through hard work alone. In reality, access to capital, inheritance, and systemic advantages play a far larger role than individual effort. Studies show that 80% of UHNWIs inherit at least some of their wealth, and many use trusts, offshore accounts, and legal loopholes to shield their assets from taxation. The system isn’t just rigged—it’s optimized for those who already have a head start.
Q: Will the number of UHNWIs keep rising, or is it stabilizing?
Growth is likely to slow in the near term due to higher interest rates, market volatility, and potential policy changes. However, the ultra-wealthy have proven resilient—shifting from public markets to private assets, real estate, and alternative investments. Long-term, the number will depend on tax policy, stock market performance, and whether new wealth-creation sectors (like AI or biotech) emerge. For now, the trend is toward stabilization at high levels, not decline.
