
The Short Answers
- As of 2023, 10.9% of American households have net worth exceeding $1 million, up from 7.7% in 2016.
- The median net worth for households in the top 10% is now $1.2 million, but the average is skewed higher by ultra-high-net-worth individuals.
- Home equity drives ~45% of millionaire-level wealth, while financial assets (stocks, retirement accounts) make up roughly 30%.
- Wealth inequality has widened: the top 1% now hold ~35% of all household wealth, up from 30% in the early 2000s.
- Geographic disparities are stark—25% of households in D.C. metro areas exceed $1M in net worth, vs. 3% in Mississippi.
- The percentage of Americans with over $1 million in net worth is projected to rise further due to low interest rates, rising home values, and inheritance trends.
Deep Dive: The Full Picture
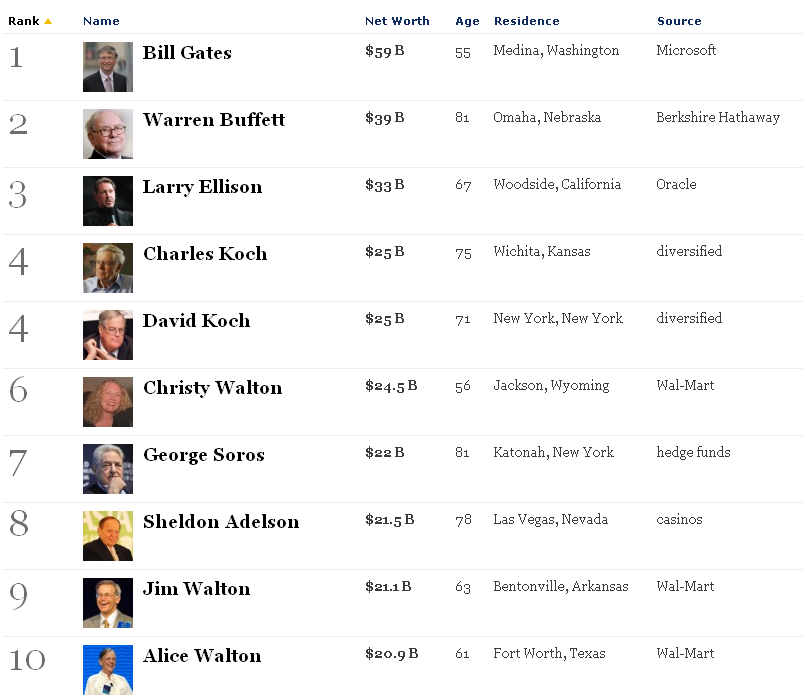
The rise in the share of Americans with net worth over $1 million isn’t a uniform phenomenon. It’s a story of two economies: one where asset appreciation has lifted millions into the ranks of the wealthy, and another where stagnant wages and student debt have left others further behind. The Federal Reserve’s data shows that the median net worth for the top 10% of households has grown by 60% since 2010, adjusted for inflation, while the median for the bottom 50% has inched up by just 15%. That divergence explains why the percentage of Americans with over $1 million in net worth has climbed even as median household wealth stagnates. What’s less discussed is the volatility beneath these numbers. A 2022 study by the Urban Institute found that 30% of households with net worth between $500K and $1M could drop below $1M within three years due to market downturns, job loss, or unexpected expenses. The $1 million threshold isn’t just a milestone—it’s a fragile one for many. For those who cross it via home equity, a housing market correction could erase years of accumulation overnight. Meanwhile, the ultra-wealthy—the top 0.1%—hold $20 million or more in net worth, a tier where liquidity and generational wealth create a far more stable footing.The Context You Need
The post-2008 recovery played a crucial role in inflating the percentage of Americans with over $1 million in net worth. The Fed’s near-zero interest rates, coupled with quantitative easing, sent asset prices—homes, stocks, even fine art—soaring. A 2021 analysis by the Brookings Institution estimated that $5.2 trillion in household wealth was created between 2019 and 2021 alone, with 70% of that gain flowing to the top 20% of earners. The S&P 500’s recovery from its 2009 lows, the rebound in commercial real estate, and the surge in tech valuations all contributed to a wealth effect that lifted millions into the millionaire bracket. But the picture changes when you adjust for geography. In coastal cities like San Francisco or New York, the share of households with over $1 million in net worth exceeds 20%, thanks to high home values and concentrated wealth. In the Midwest or South, that figure hovers around 5–8%. The disparity isn’t just about income—it’s about opportunity. A teacher in Austin with a $600K home might have a net worth of $1.1 million, while a similarly educated peer in Detroit with the same home value could be underwater due to higher local taxes or maintenance costs. The percentage of Americans with over $1 million in net worth tells us little about the quality of that wealth.The Mechanics
The mechanics of crossing the $1 million net worth threshold vary by demographic. For Baby Boomers, it’s often a combination of home equity, retirement accounts, and inheritance. A 2023 report by the Spectrem Group found that 60% of millionaires over 65 cite home equity as their primary wealth driver, while 40% point to defined-benefit pensions—a shrinking but still significant source. For Gen X and younger Millennials, the path is different: stock ownership and employer-sponsored retirement plans (like 401(k)s) now dominate. The rise of index funds and robo-advisors has democratized access to market gains, but only for those who can afford to invest in the first place. Tax policy has also played a hidden role. The 2017 Tax Cuts and Jobs Act lowered capital gains rates, making it easier for asset holders to realize gains without triggering higher tax brackets. Meanwhile, the step-up in basis for inherited assets means heirs often pay little to no tax on appreciated property, allowing wealth to compound across generations. When you overlay these factors onto the percentage of Americans with over $1 million in net worth, you see a system where wealth begets wealth—and where policy changes have disproportionately benefited those who already have assets.Details That Change the Picture
The percentage of Americans with over $1 million in net worth is often cited as a measure of economic health, but it’s a flawed metric. For one, it ignores liquidity. A $1.5 million home in Cleveland might not be as valuable as a $1.5 million condo in Miami, yet both would register the same on net worth statements. For another, it conflates nominal wealth with real purchasing power. Inflation has eroded the value of cash savings, meaning a $1 million net worth in 2010 would buy far fewer goods today. Adjust for inflation, and the real growth in millionaire households looks less dramatic. Then there’s the debt factor. Many households with net worth exceeding $1 million carry significant liabilities—mortgages, private school tuition, or business loans—that aren’t reflected in the headline numbers. A 2022 study by the New York Fed found that 25% of households with $1M–$5M in assets have debt levels exceeding 30% of their net worth, leaving them vulnerable to economic shocks. The percentage of Americans with over $1 million in net worth doesn’t distinguish between secure wealth and leveraged exposure."Wealth isn’t just about the number on a balance sheet. It’s about control—control over your time, your choices, and your legacy. A $1 million net worth can be a prison if it’s all tied up in illiquid assets or debt. The real measure isn’t crossing the line; it’s what you can do once you’re there." — Dr. Edward N. Wolff, Professor of Economics at NYU and author of The Assets of the American Middle Class
| Demographic Group | % with Net Worth > $1M (2023) |
|---|---|
| Households headed by someone 65+ | 18.3% |
| Households headed by someone 35–54 | 9.8% |
| Households headed by someone under 35 | 2.1% |

Conclusion
The percentage of Americans with over $1 million in net worth has risen, but the story behind the numbers is one of uneven progress. For some, it’s a reflection of smart savings, disciplined investing, and the tailwinds of a recovering economy. For others, it’s a fragile achievement tied to home values that could correct, or to retirement accounts that may not stretch as far in retirement as they once seemed. What’s clear is that wealth in America is no longer just about income—it’s about access to assets, geographic luck, and the generational head start that many lack. The conversation around wealth inequality often focuses on the top 1%, but the share of Americans with over $1 million in net worth reveals a broader truth: the middle class is being squeezed from both ends. Those who cross the $1 million threshold today may find themselves in a different economic landscape tomorrow, where inflation, policy shifts, or a market downturn could redefine what it means to be wealthy. The question isn’t just how many have made it—but whether the system is designed to keep them there.Comprehensive FAQs
Q: Is the percentage of Americans with over $1 million in net worth higher in cities or rural areas?
The share is significantly higher in urban areas, particularly in tech hubs (San Francisco, Seattle), financial centers (New York, D.C.), and coastal markets (Miami, Boston). In these areas, 20–25% of households exceed $1M in net worth, compared to 3–8% in rural or Southern states. The difference stems from home values, wage levels, and access to high-earning professions.
Q: Does owning a $1 million home automatically put you in the top 10% by net worth?
Not necessarily. Net worth includes all assets minus liabilities, so if you have a $1M home but $800K in mortgage debt, your net worth is just $200K. The Federal Reserve’s data shows that only about 40% of households with a home valued at $1M+ have net worth exceeding $1M due to debt. The rest are asset-rich but cash-poor.
Q: How has the share of Americans with over $1 million in net worth changed since the 2008 financial crisis?
It has more than doubled. In 2007, before the crash, 5.5% of households had net worth over $1M. By 2010, that figure had dropped to 4.2% as asset values plummeted. Since then, it has climbed steadily, reaching 10.9% in 2023—a recovery driven by home price appreciation, stock market gains, and low interest rates.
Q: Are most millionaires self-made, or do they inherit wealth?
It depends on the generation. Boomers and older Gen Xers are more likely to have inherited wealth—40% of millionaires over 65 report receiving an inheritance at some point. For younger generations, earned wealth dominates: 70% of millionaires under 50 built their wealth primarily through careers, entrepreneurship, or investing. However, inheritance still plays a role in 30–40% of cases even for younger cohorts.
Q: Does having over $1 million in net worth guarantee financial security?
No. While $1M is a significant buffer, spending habits, healthcare costs, and market volatility can erode it quickly. A 2022 study by the Center for Retirement Research found that $1M is enough to generate $40K/year in retirement income—but only if you’ve paid off your mortgage and have low living expenses. For many, $1M is a starting point, not an endpoint.
Q: How does the percentage of Americans with over $1 million in net worth compare to other countries?
The U.S. has a higher share of millionaire households than most developed nations, but the gap narrows when adjusted for population and wealth distribution. In Canada and Australia, roughly 8–9% of households exceed $1M in net worth (adjusted for purchasing power). In Western Europe, the figure is closer to 5–7%, partly due to higher taxes on wealth and different housing markets. The U.S. stands out for its concentration of ultra-high-net-worth individuals—those with $30M+—which skews the overall numbers.
Q: What’s the biggest misconception about the share of Americans with over $1 million in net worth?
The biggest myth is that it reflects broad-based prosperity. In reality, the rise in millionaire households is heavily concentrated among older, white, and college-educated demographics. Black and Hispanic households have a net worth share of $1M+ at just 3–4%, compared to 12% for white households. Additionally, many who cross the $1M threshold do so temporarily—due to a windfall (like a home sale) rather than sustainable wealth-building.
Q: Will the percentage of Americans with over $1 million in net worth keep rising?
Likely, but at a slower pace. The Fed’s projections suggest that if current trends continue—low interest rates, rising home prices, and strong stock markets—the share could reach 12–14% by 2030. However, risks like inflation, a housing correction, or policy changes (e.g., higher capital gains taxes) could temper growth. For younger generations, student debt and stagnant wages remain major hurdles, meaning the percentage of Americans with over $1 million in net worth may not rise as quickly for them as it has for older cohorts.
