
Where It All Began
The origins of tracking how many Americans have net worth of over one million dollars lie in the post-World War II era, when the middle class was still the dominant force in the U.S. economy. In 1950, only about 1.5 million households—roughly 3% of the population—had a net worth exceeding $1 million in today’s dollars. Most of these were industrialists, landowners, or professionals who had benefited from the G.I. Bill, cheap credit, and a booming manufacturing sector. Wealth wasn’t just about cash; it was tied to tangible assets: factories, farms, and family homes. The idea that a blue-collar worker could retire with a seven-figure portfolio was unthinkable. By the 1970s, that began to shift. The rise of financialization—the growth of mutual funds, pension plans, and stock ownership—meant that wealth could now be held in paper assets rather than just physical property. The Employee Retirement Income Security Act (ERISA) of 1974 expanded access to 401(k) plans, though participation remained low. Still, the number of households with $1 million+ net worth crept upward, reaching 5 million by 1989. The key driver? The Tax Reform Act of 1986, which slashed capital gains taxes and made investing more attractive. Suddenly, wealth wasn’t just for the old money elite; it was within reach for those who could play the stock market.The Early Signs
The 1990s marked the first decade where the question of how many Americans have net worth of over one million dollars became a mainstream economic concern. The dot-com boom and the subsequent bust revealed how fragile wealth could be—yet also how quickly it could rebound. By 2000, the number of millionaire households had nearly doubled to 9 million, thanks to the tech stock bubble and the housing boom of the late 1990s. But the crash of 2000–2002 wiped out paper wealth for many, and the number stagnated. What became clear was that wealth accumulation wasn’t just about income—it was about asset appreciation. A teacher saving in a 401(k) could become a millionaire if the S&P 500 kept rising. A real estate agent flipping homes in Florida could hit the mark if prices kept climbing. The problem? Not everyone had access to the same levers. Homeownership rates among Black and Hispanic families lagged behind white families by 20–30 percentage points, and stock ownership remained concentrated among the wealthy. The early 2000s showed that $1 million net worth wasn’t just a financial milestone—it was a gateway to generational wealth.The Turning Point
The Great Recession of 2008–2009 could have been the end of the story. Millions lost homes, retirement accounts shrank, and the number of millionaire households dropped by 1.5 million in a single year. But what followed was the most aggressive monetary policy in U.S. history: near-zero interest rates, quantitative easing, and a stock market that refused to correct. By 2012, the Federal Reserve began publishing data showing that the top 10% of households held 70% of all liquid assets. The game had changed. Wealth wasn’t just about working harder—it was about owning the right things at the right time. The turning point wasn’t just economic; it was cultural. The rise of fintech, index funds, and passive investing democratized access to wealth-building tools, but the benefits didn’t trickle down evenly. Meanwhile, home values in coastal cities surged, turning real estate into the ultimate wealth multiplier. By 2016, 12.3 million households had crossed the $1 million threshold—more than double the 2007 figure. The question of how many Americans have net worth of over one million dollars had become less about individual effort and more about structural advantage."Wealth isn’t just money. It’s the ability to turn money into more money—and that ability is rigged." — Edward N. Wolff, Professor of Economics at NYU and author of The Asset Price Meltdown

The Build-Up, Year by Year
| Period | Key Developments | Impact on Millionaire Count |
|---|---|---|
| 1980s–1990s |
|
Growth from 5M to 9M households. |
| 2000–2007 |
|
Peak at 11M before 2008 crash. |
| 2010–2020 |
|
Explosive growth to 24M by 2020. |
Lessons From the Journey
- Wealth is now tied to asset ownership—not just income. A teacher with a diversified portfolio can out-earn a CEO who lives paycheck-to-paycheck.
- The $1 million threshold is no longer a static number. Inflation, stock market performance, and housing prices constantly redefine what it means.
- Geography matters more than ever. A millionaire in Miami looks different from one in Des Moines.
- Inheritance is the silent multiplier. The top 10% of estates account for 40% of all intergenerational transfers, perpetuating wealth concentration.
- Debt is a double-edged sword. Student loans and medical debt can prevent accumulation, while leveraged real estate can accelerate it.
- The millionaire puzzle isn’t just about money—it’s about opportunity. Who gets access to financial education, high-paying jobs, and asset-building tools?
Where Things Stand Today
As of 2023, estimates suggest between 25 and 28 million American households have a net worth exceeding $1 million. The exact number fluctuates with market conditions, but the trend is clear: wealth is becoming more concentrated. The top 1% now holds 35% of all wealth, up from 25% in 1990. Meanwhile, the median net worth of the bottom 50% has barely budged since the 1980s. The question of how many Americans have net worth of over one million dollars is less about celebration and more about alarm. Because for every household that crosses the threshold, three others are falling further behind. What’s driving the current surge? Three forces: corporate stock ownership (thanks to 401(k)s and ESG funds), rising home values (especially in high-cost cities), and passive income streams (dividends, rental properties, private equity). Yet the data also shows a geographic divide. In San Francisco, Seattle, and New York, the millionaire rate exceeds 25% of households. In Mississippi, Arkansas, and West Virginia, it’s below 5%. The millionaire map of America is no longer a national statistic—it’s a zip code lottery.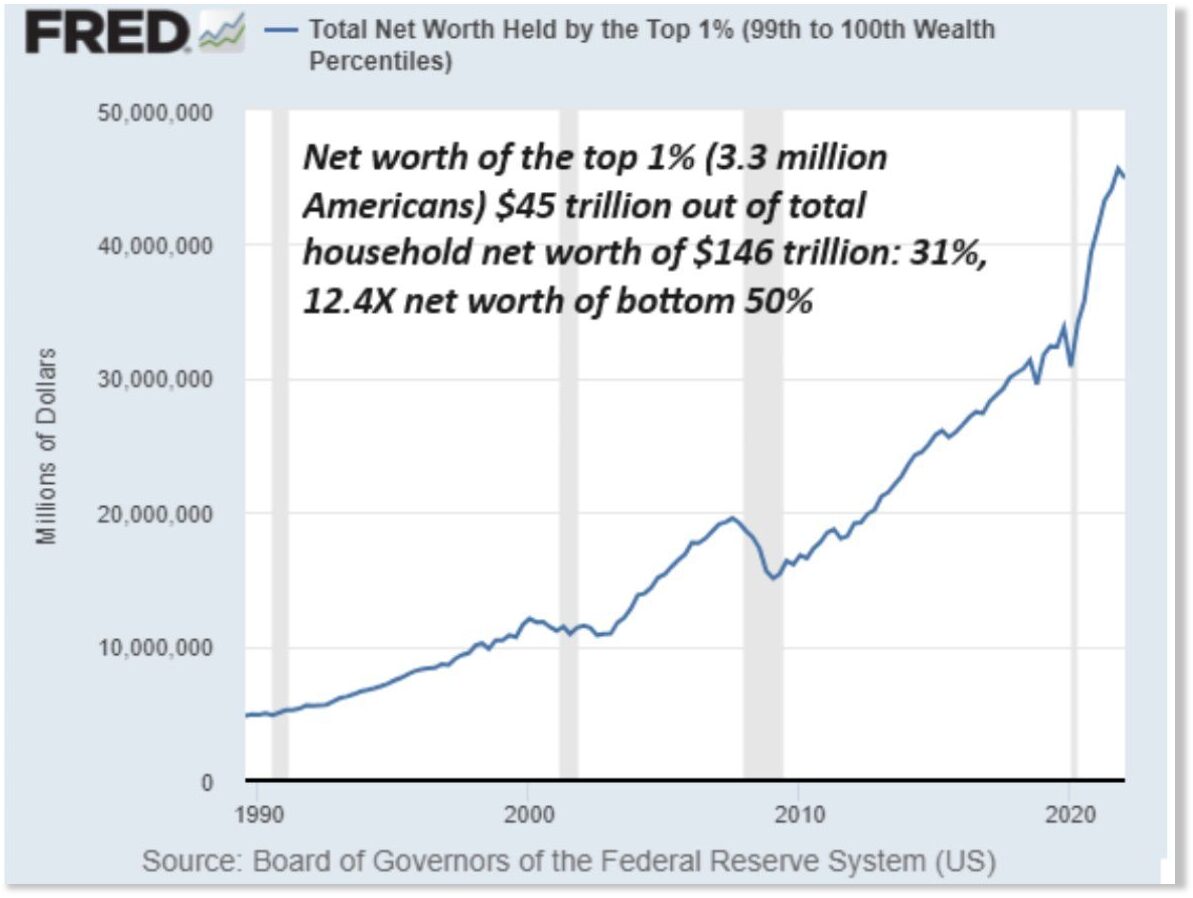
Conclusion
The story of how many Americans have net worth of over one million dollars is more than a ledger entry. It’s a reflection of how wealth is created, who gets to participate, and what happens when the rules favor the few. The data doesn’t lie: the ladder is longer, the rungs are narrower, and the climb is harder for those who didn’t start at the top. Yet there’s also a quiet resilience in the numbers. Millions of Americans—teachers, nurses, small-business owners—have built wealth through discipline, luck, and the right opportunities. The challenge now is whether those opportunities will expand or remain the exclusive domain of the already privileged. One thing is certain: the next decade will test whether the millionaire count keeps rising—or whether the system finally cracks under the weight of inequality. The answer will determine not just who gets rich, but what kind of country we leave to the next generation.Comprehensive FAQs
Q: What’s the most common way Americans reach $1 million in net worth?
The top three paths are: 1. Home equity (especially in high-appreciation markets like Austin, Phoenix, or coastal cities). 2. Retirement accounts (401(k)s and IRAs, boosted by stock market growth). 3. Business ownership (small businesses, franchises, or professional practices). Inheritance and windfalls (lottery, stock options) account for a smaller but significant share.
Q: Are more Americans becoming millionaires than in past decades?
Yes—but the growth is uneven. The millionaire rate (households with $1M+ net worth) has risen from ~2% in 1983 to ~10% today, but the top 1% has seen the most dramatic gains. The middle class has stagnated, while the ultra-wealthy have seen their share of total wealth rise from 20% to 35% since 1990.
Q: Does having $1 million make someone "rich" in the U.S.?
It depends on where you live. In San Francisco or Manhattan, $1 million may not cover basic living costs for a family. In rural America or the Midwest, it can be a lifetime of financial security. The real threshold for "rich" in the U.S. is often $5 million+, where true generational wealth transfer begins.
Q: How does student debt affect the chance of reaching $1 million?
Heavily. A 2022 Federal Reserve study found that households with student debt have 10–15% lower net worth than those without. The reason? Debt delays homeownership, retirement savings, and investment. Even among high earners, student loans can reduce the likelihood of millionaire status by 20–30%.
Q: Are more women crossing the $1 million threshold than in the past?
Yes—but the gap persists. Women now make up 30% of millionaire households (up from 20% in 1990), but they still face pay gaps, career interruptions, and lower pension balances. The fastest-growing segment? Single women over 50, who are increasingly relying on divorce settlements, inheritance, and real estate to build wealth.
Q: What’s the biggest myth about reaching $1 million in net worth?
The myth that it’s purely about income. Most millionaires aren’t high earners—they’re consistent savers, smart investors, and asset owners. The average millionaire household has a median income of $250,000, but their wealth comes from home equity, retirement accounts, and low-cost index funds, not just salary.
