The Short Answers
- About 11.7% of U.S. households (15.6 million) had net worth over $1 million in 2023, per Federal Reserve data.
- Wealth concentration is extreme: the top 10% hold 70% of all net worth, while the bottom 50% hold just 2.6%.
- Geographic disparities matter—New York, California, and Massachusetts have the highest millionaire densities, but rural and Southern states lag.
- Age plays a critical role: 60% of millionaires are over 55, with inherited wealth and home equity as key drivers.
- Homeownership is the primary asset for most millionaires—65% of those over $1M rely on real estate for the bulk of their wealth.
- Inflation and market volatility mean these numbers fluctuate—the 2022 downturn erased $5 trillion in household wealth, pushing some above the threshold while others fell below.
Deep Dive: The Full Picture
The Federal Reserve’s Survey of Consumer Finances (SCF) remains the gold standard for answering what percentage of the U.S. population has net worth over a million. Released every three years, the latest 2022 data (adjusted for 2023 inflation) shows that 11.7% of households cleared that benchmark. Yet this snapshot obscures critical nuances. For instance, single-person households hit the $1 million mark at a lower rate (8.2%) than married couples (15.3%), reflecting how wealth compounds through shared resources. The median net worth for these households? $2.2 million—a figure that skews higher in coastal cities but plummets in the Midwest and South. What’s often overlooked is the asset composition of millionaire households. The SCF reveals that primary residences account for 35% of total wealth in these families, while financial assets (stocks, bonds, retirement accounts) make up another 30%. The remaining 35% is split between business equity, vehicles, and other holdings. This mix explains why homeowners dominate the millionaire ranks—but it also exposes vulnerability. A 2023 study by the Urban Institute found that 40% of millionaires would struggle to cover a $10,000 emergency without liquidating assets, proving that net worth ≠ spendable cash.The Context You Need
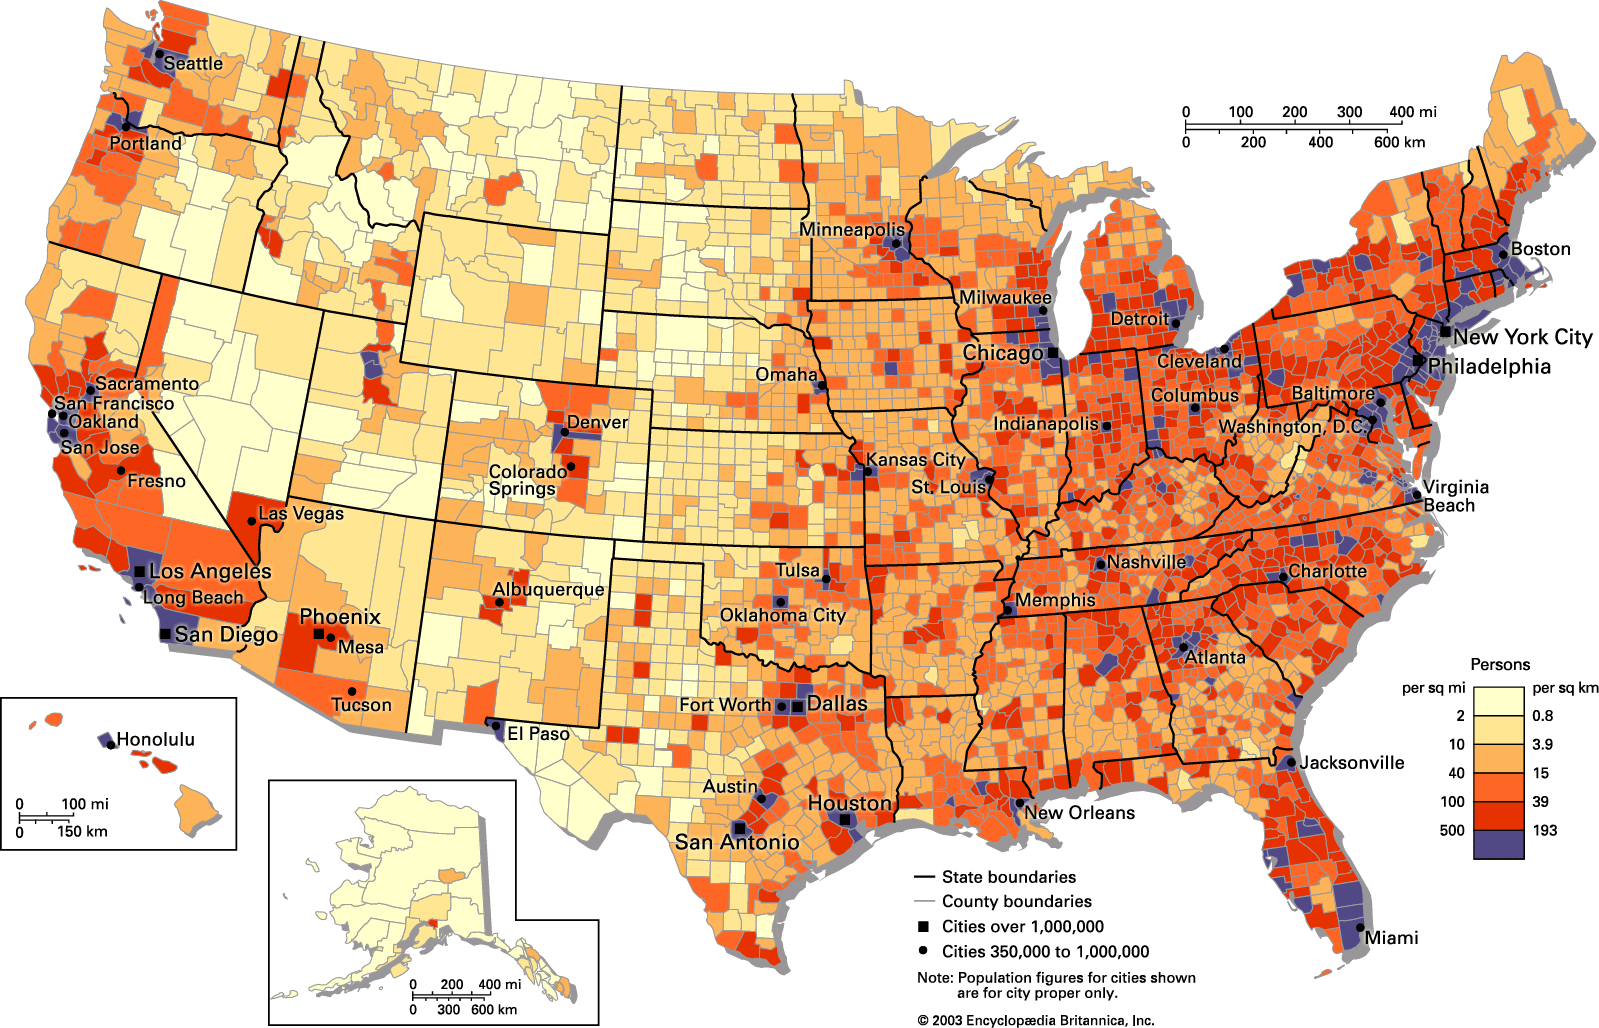
The $1 million threshold isn’t arbitrary. It’s a psychological and structural dividing line. Economists at the St. Louis Fed note that households above this level typically face lower marginal tax rates, access to private banking services, and greater influence in political and philanthropic circles. But the path to crossing it has shifted dramatically over decades. In the 1980s, entrepreneurship and small-business ownership were the primary routes; today, passive investments (index funds, real estate trusts) and inherited wealth dominate. The Pew Research Center estimates that 60% of millionaires today are first-generation wealthy, but the share of inherited wealth in the top 1% has risen from 35% in 1989 to 50% today. Regional disparities further complicate the answer to what percentage of Americans have net worth over a million. States like New York, California, and Massachusetts have millionaire rates 2-3x the national average, thanks to high-paying industries and expensive real estate. Meanwhile, Mississippi and West Virginia hover around 5-6%, where stagnant wages and lower home values suppress wealth accumulation. Even within cities, zip codes dictate outcomes: a 2023 Brookings Institution report found that wealth in majority-Black neighborhoods is 30% lower than in comparable white neighborhoods, despite similar incomes.The Mechanics
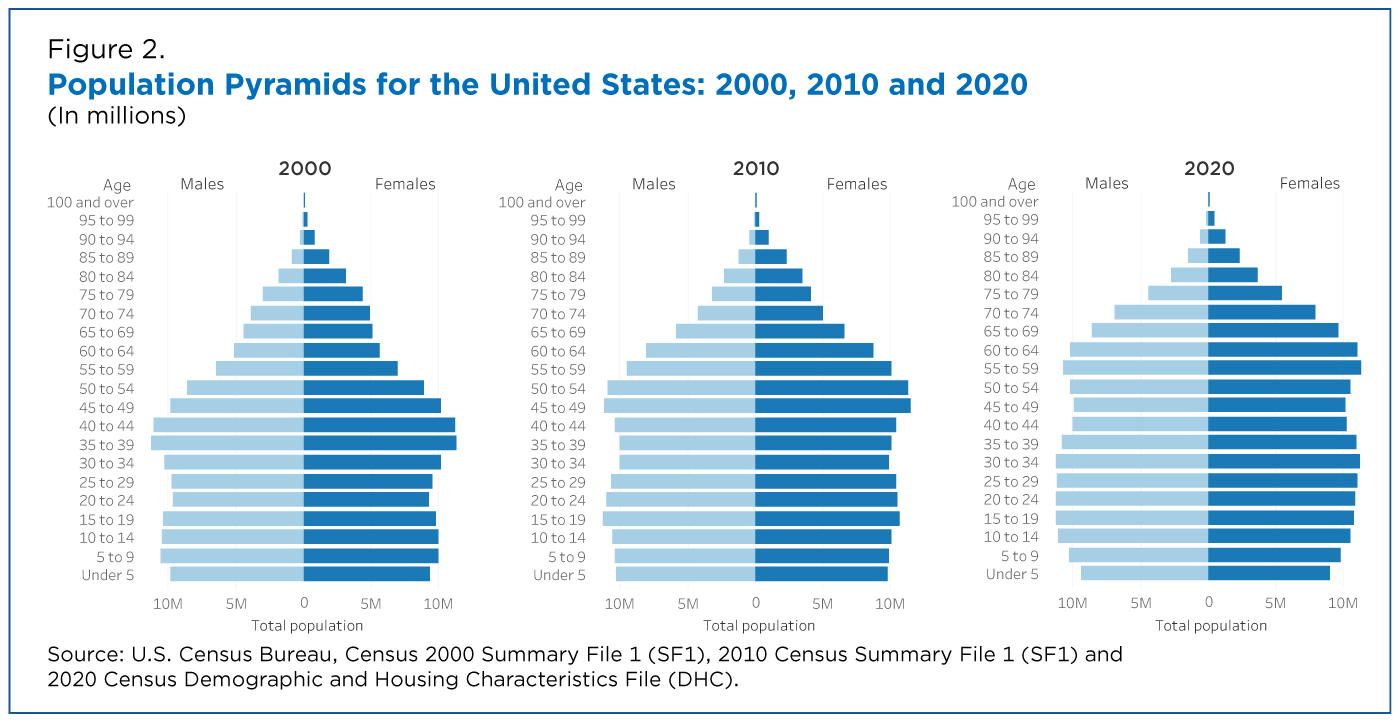
The mechanics of millionaire creation are less about raw income and more about asset accumulation strategies. The SCF data shows that home equity is the single largest driver—households with mortgages under $100,000 are 5x more likely to reach $1 million than those with higher debt. Retirement accounts (401(k)s, IRAs) contribute 20% of wealth for pre-retirees, while stock ownership (even modest ETF holdings) pushes many over the line during bull markets. The tax code plays a silent role: capital gains taxes on appreciated assets mean that realizing wealth (selling stocks, refinancing homes) can trigger unexpected liabilities. Demographics matter just as much as dollars. Millionaires skew older: 60% are over 55, with the average age at 62. This reflects how wealth builds over time—compound interest, salary growth, and inheritance are the trio of forces at work. Younger households (under 35) have a 3.2% millionaire rate, but this cohort is growing faster than any other, thanks to remote work, gig economy savings, and crypto investments. The catch? Liquidity crises—many young millionaires are "house rich" with little cash flow, a vulnerability exposed during the 2020-2022 market downturn.Details That Change the Picture
The raw percentage—what percentage of the U.S. population has net worth over a million—tells only part of the story. The quality of that wealth varies wildly. Consider this: a doctor in Dallas might have $1.2 million in net worth, but $900,000 of it is tied up in their medical practice, leaving them with limited flexibility. Conversely, a software engineer in Austin could have the same net worth but $800,000 in liquid assets, offering far greater financial mobility. This distinction explains why net worth alone is a poor predictor of economic security. Another layer is debt leverage. The SCF reveals that 40% of millionaire households carry debt, often in the form of mortgages or business loans. For some, this debt is a tool—using leverage to buy rental properties or scale a business. For others, it’s a ticking time bomb. The 2008 financial crisis demonstrated how quickly overleveraged millionaires could fall below the threshold. Today, student loans and credit card debt are emerging risks, particularly for younger high-net-worth individuals."Wealth isn’t just about the balance sheet—it’s about the options it unlocks. A $1 million net worth in Manhattan buys you a different life than the same number in Memphis. The real question isn’t how many people cross that line, but what they can do once they’re there." — Edward N. Wolff, Professor of Economics at NYU and author of The Asset Price Meltdown
| Metric | Key Finding |
|---|---|
| Median Net Worth for Millionaires | $2.2 million (varies by region) |
| Primary Wealth Driver | Home equity (35%), financial assets (30%) |
| Liquidity Gap | 40% of millionaires lack emergency cash reserves |

Conclusion
The answer to what percentage of Americans have net worth over a million is a moving target, shaped by market cycles, policy shifts, and generational transitions. What’s clear is that the millionaire club isn’t just about money—it’s about access to opportunities that most Americans never see. From tax-advantaged investments to elite networking circles, the benefits of crossing that threshold extend far beyond balance sheets. Yet the data also exposes a harsh truth: wealth in America is still a game of geography, inheritance, and timing. Without structural changes, the percentage of households above $1 million will continue to reflect the same old inequalities—just with bigger numbers. For policymakers, the question isn’t just statistical but moral. If 11.7% of families can achieve this level of wealth, why do so many others struggle to save for retirement? The answer lies in the uneven playing field—where some start with generational wealth, others with student debt, and most with neither. The next decade will test whether the U.S. can broaden the path to millionaire status—or whether the numbers will remain a testament to how the game is fixed.Comprehensive FAQs
Q: How does inflation affect the percentage of Americans with net worth over $1 million?
The Federal Reserve adjusts net worth figures for inflation, but nominal thresholds (like $1 million) lose purchasing power over time. For example, a $1 million net worth in 1990 had the buying power of $2.2 million today. This means the real percentage of households with "millionaire" wealth is likely lower than reported, as many would fall below the adjusted threshold.
Q: Are there more millionaires now than in 2000?
Yes—but the growth is uneven. The number of U.S. millionaires doubled from 7.8 million in 2000 to 15.6 million in 2023, per the Fed. However, this growth is concentrated in asset classes (stocks, real estate) rather than wages. The median income-adjusted net worth has stagnated for most Americans, meaning the millionaire boom hasn’t trickled down.
Q: Can you be a millionaire on a modest salary?
Technically yes, but it requires extreme frugality, asset appreciation, or inheritance. A 2023 study by GoBankingRates found that saving $500/month for 30 years at a 7% return could yield ~$600,000—but this assumes no major expenses, debt, or market downturns. Most millionaires on modest incomes rely on home equity, low-cost investments, or family wealth transfers.
Q: Do most millionaires work in finance or tech?
No. While finance and tech executives are overrepresented, the largest groups are:
- Small business owners (30%)
- Healthcare professionals (20%)
- Retired public-sector workers (15%)
- Real estate investors (12%)
Q: How does student debt impact the millionaire rate?
Student debt suppresses wealth accumulation by delaying homeownership and investment. A 2022 Brookings study found that households with student loans have net worth 40% lower than comparable debt-free peers. This is why millionaire rates among Gen X and Millennials are 20-30% lower than Boomers’, despite similar incomes. The debt burden effectively raises the net worth threshold for younger generations.
Q: Are there more millionaires in rural areas than the stats suggest?
Not significantly. While rural millionaires exist, their numbers are skewed by:
- Undervalued land (e.g., farmland in Nebraska can be worth millions but isn’t liquid).
- Off-the-books wealth (cash businesses, unrecorded assets).
- Lower cost of living (a $1M net worth in rural Iowa buys far less than in NYC).
Q: What’s the biggest misconception about the $1 million net worth statistic?
The biggest myth is that crossing $1 million means financial freedom. In reality:
- 60% of millionaires still work (often out of choice, not necessity).
- 30% have no retirement savings beyond their primary home.
- 20% are "paper millionaires"—their wealth is tied up in illiquid assets (e.g., a single rental property).
