
The Complete Overview of What Percentage of Americans Have a Net Worth of $2 Million or Greater
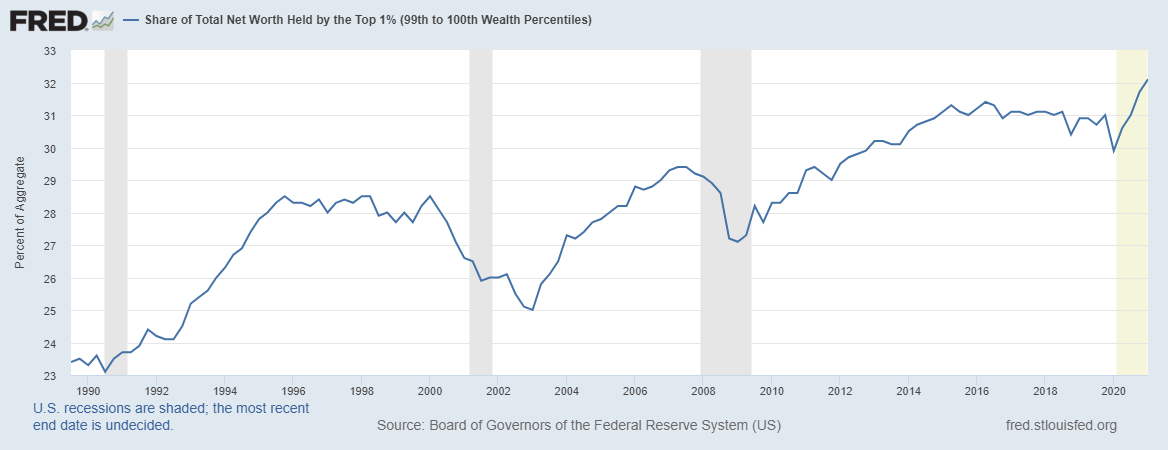
The $2 million net worth benchmark isn’t arbitrary. It’s a psychological and economic tipping point where tax liabilities shift, estate planning becomes critical, and access to exclusive investment vehicles—private equity, venture capital, or even certain retirement accounts—opens up. Yet only a fraction of Americans ever reach this level, and the reasons are as much about systemic barriers as they are about individual effort. The Federal Reserve’s data shows that white households are nearly 10 times more likely to hit this threshold than Black households, and Asian households are roughly 5 times more likely than Hispanic households. These disparities aren’t just statistical anomalies; they reflect centuries of policy, education access, and wealth inheritance patterns. What’s equally striking is how concentrated the wealth is among the ultra-affluent. The top 0.1% of Americans—about 160,000 households—hold $25 million or more, a figure that dwarfs the $2 million cutoff. This elite group controls 22% of all U.S. wealth, while the bottom 50% collectively own just 2.6%. The $2 million threshold isn’t just a wealth milestone; it’s a dividing line between financial security and true economic power. Understanding what percentage of Americans have a net worth of $2 million or greater requires peeling back layers of inheritance, education, and geographic opportunity—factors that most personal finance discussions gloss over.Historical Background and Evolution
The modern era of tracking net worth began in the 1980s, when the Federal Reserve started publishing its Survey of Consumer Finances. Before that, wealth data was fragmented, relying on tax records or spotty census estimates. The 1989 survey marked the first time the Fed explicitly broke down net worth by percentile, revealing that only 3.2% of households had $1 million or more (adjusted for inflation, roughly equivalent to today’s $2 million). By 2000, that figure had crept up to 4.5%, but the dot-com crash and Great Recession sent it plummeting. It didn’t recover to pre-2000 levels until 2016. The post-2008 recovery reshaped the landscape. The stock market’s surge, coupled with rising home values in high-cost cities, pushed the $2 million net worth threshold into reach for more households—though not nearly enough to close the racial or regional gaps. The Fed’s 2022 data shows that homeownership accounts for 60% of the net worth of households at or above $2 million, while financial assets (stocks, bonds, retirement accounts) make up the remainder. This dynamic underscores why real estate bubbles and market volatility have outsized impacts on who crosses this financial line. The question of what percentage of Americans have a net worth of $2 million or greater isn’t static; it’s a moving target shaped by macroeconomic forces, policy shifts, and generational wealth transfers.Core Mechanisms: How It Works
Reaching $2 million in net worth isn’t just about earning a high income—it’s about asset accumulation over time. The average household takes 20–30 years to cross this threshold, assuming consistent saving, smart investing, and favorable market conditions. For most, it’s a combination of home equity, retirement accounts (401(k)s, IRAs), and investment portfolios. The top earners in this group often have multiple income streams: business ownership, dividends, rental properties, or even passive income from digital assets. Tax policy plays a hidden but critical role. The $2 million net worth level triggers higher capital gains taxes, estate taxes (for married couples over $25 million in 2024), and more complex financial planning. Wealthy households often employ trusts, charitable giving strategies, or offshore accounts to mitigate these burdens. Meanwhile, the opportunity cost of not reaching this level is stark: access to elite schools, private healthcare, and political influence becomes far more limited. The mechanics of crossing the $2 million line are less about raw income and more about structural advantages—inheritance, education, and geographic luck—that most Americans never encounter.Key Benefits and Crucial Impact
Crossing the $2 million net worth threshold isn’t just a financial achievement; it’s a social and economic unlock. The benefits extend beyond tax savings to include enhanced financial flexibility, such as the ability to retire early, fund children’s education without debt, or weather market downturns without selling assets. For business owners, it means access to private credit lines, venture capital, or even the ability to buy out partners. Yet the most tangible advantage may be intergenerational wealth transfer: households at this level can leave $1 million+ to heirs without triggering federal estate taxes (for most couples), ensuring their children or grandchildren start life with a head start. The psychological impact is equally significant. Wealth at this level often correlates with reduced financial stress, greater ability to take calculated risks (like starting a business or pursuing a passion project), and even longer lifespans—studies show that financial security in later years improves health outcomes. But the benefits aren’t equally distributed. White households are far more likely to leverage this wealth for home purchases in desirable neighborhoods, while households of color often face higher costs for similar assets due to systemic discrimination in lending and zoning. The divide isn’t just about money; it’s about opportunity hoarding."Wealth isn’t just about what you earn; it’s about what you own and what you control. The $2 million threshold isn’t a finish line—it’s the starting gate for a different kind of economy." — Edward N. Wolff, Professor of Economics at NYU and author of The Asset Price Meltdown
Major Advantages
- Tax optimization: Access to lower long-term capital gains rates (15–20%) and estate planning tools like grantor retained annuity trusts (GRATs) to pass wealth tax-free.
- Investment diversification: Ability to allocate funds into private equity, hedge funds, or real estate syndications—vehicles typically closed to lower-net-worth individuals.
- Estate continuity: Heirs inherit assets with built-in appreciation, reducing the need for liquidity during probate.
- Geographic mobility: Financial independence allows relocation to lower-cost areas or countries with favorable tax regimes (e.g., Portugal’s Non-Habitual Resident program).
- Philanthropic leverage: Donations to universities, museums, or political campaigns carry greater weight, influencing policy and cultural narratives.
Comparative Analysis
| Metric | Households with $2M+ Net Worth |
|---|---|
| Demographic Breakdown | 7.5% of U.S. households (2022 Fed data); 90% white, 4% Asian, 3% Hispanic, 1% Black. |
| Primary Asset Sources | 60% home equity, 25% financial investments, 10% business ownership, 5% other. |
| Income vs. Net Worth | Median income: ~$350K; median net worth: $2.2M. Many in this group rely on passive income. |
| Regional Concentration | Top states: California (12% of national total), New York (10%), Florida (8%), Texas (7%). Rural areas: <1%. |
Future Trends and Innovations
The next decade may see a slow but steady increase in the percentage of Americans with $2 million+ net worth, driven by rising home values in Sun Belt states and the growth of alternative investments like cryptocurrency and private markets. However, inflation and student debt could offset gains for younger generations. The Fed’s next survey (expected 2025) may reveal whether the post-pandemic wealth boom was a temporary spike or the beginning of a new trend. Innovations in automated wealth management (robo-advisors, AI-driven portfolio optimization) could democratize access to high-net-worth strategies, but structural barriers—like the racial wealth gap—will persist without policy intervention. Meanwhile, estate planning tools like donor-advised funds and family limited partnerships are evolving to help wealthy families preserve assets across generations. The question of what percentage of Americans have a net worth of $2 million or greater will increasingly hinge on whether these tools bridge gaps—or widen them.
Conclusion
The $2 million net worth threshold isn’t just a number; it’s a reflection of America’s economic divides. While 7.5% of households have crossed it, the journey to that point is shaped by forces beyond individual effort. Inheritance, education, and geography play outsized roles, and the data shows that wealth begets wealth in ways that defy meritocratic narratives. For those who achieve it, the benefits are undeniable—but the system that produces these winners also ensures that millions remain locked out. The conversation around what percentage of Americans have a net worth of $2 million or greater must extend beyond statistics to address the policies, cultural norms, and historical inequities that sustain this divide. Without intentional change, the figure will remain stubbornly low—and the gap between the ultra-wealthy and everyone else will only widen.Comprehensive FAQs
Q: How does the $2 million net worth figure compare to other wealthy benchmarks?
The $2 million threshold is often cited as the entry point for "high net worth" status, but true ultra-high-net-worth (UHNW) begins at $5 million or more. The top 1% of Americans hold $10 million+, while the top 0.1% have $25 million+. The Fed’s data shows that only 0.3% of households fall into the $5 million+ category.
Q: Are there regional differences in who reaches $2 million?
Yes. States like California, New York, and Massachusetts have higher concentrations due to high-paying industries (tech, finance, biotech) and expensive real estate. Conversely, rural states (e.g., Mississippi, West Virginia) have less than 2% of households at this level. Even within cities, zip-code disparities matter—wealthy neighborhoods see 3–5x higher rates than adjacent lower-income areas.
Q: Does inheritance play a major role in reaching $2 million?
Absolutely. Studies show that inheritance accounts for 20–30% of net worth for households at or above $2 million. The average inheritance for this group is $500,000–$1 million, a sum that can accelerate asset accumulation. Without inherited wealth, many would take decades longer to cross the threshold.
Q: How does education factor into net worth outcomes?
Households headed by college graduates are 4x more likely to reach $2 million than those without a degree. Advanced degrees (MBAs, law, medicine) correlate with higher earning potential and asset-building opportunities. However, student debt can delay progress—30% of households with $2M+ net worth still carry education loans, though often at manageable levels.
Q: What’s the biggest misconception about who has $2 million in net worth?
The biggest myth is that it’s earned solely through high salaries or business success. In reality, most at this level rely on a mix of home equity, retirement accounts, and long-term market exposure. Many never earned six figures annually—yet their wealth grew through compounding investments over 30+ years. The path is less about income spikes and more about disciplined asset accumulation.
