
7 Things Worth Knowing About What Percentage of Americans Have a Net Worth of Over $1,000,000
The debate over what percentage of Americans have a net worth of over $1,000,000 isn’t just about counting the wealthy—it’s about exposing the cracks in the American Dream. The figures reveal where opportunity exists, where it’s disappearing, and who gets left behind. Here’s what the data shows, beyond the headlines.1. The official estimate sits at around 11.5%
According to the Federal Reserve’s 2022 Survey of Consumer Finances, roughly 11.5% of American households have a net worth exceeding $1 million. This includes primary residences, retirement accounts, and other assets. However, the number fluctuates based on market conditions—stock market rallies in 2021 and 2023 temporarily inflated these figures, while recessions can erase wealth overnight. The Fed’s data also shows that the top 10% of households hold 70% of all wealth, meaning the majority of Americans are clustered well below that $1M mark. What’s often overlooked is that this 11.5% figure is a national average. In states like New York, Massachusetts, and California, the percentage jumps to 15% or higher, thanks to high home values and tech-driven wealth. In contrast, states like Arkansas and Mississippi hover around 5% or less. The disparity isn’t just regional—it’s generational. Households headed by someone over 65 are far more likely to hit $1M than those under 35, a reflection of decades of compounded savings and home equity.2. The real number could be higher—or lower—depending on how you measure wealth
The Fed’s definition of net worth includes primary residences, retirement accounts, and business equity, which can skew the numbers upward for homeowners. Exclude the family home, and the percentage of Americans with $1M in liquid assets drops significantly. Some economists argue that only about 7% of households have $1M in investable assets alone—meaning most millionaires are home-rich but cash-poor. This distinction matters when discussing financial mobility: a retiree with a paid-off mansion may feel secure, but a young professional with no real estate holdings faces a much steeper climb. Then there’s the issue of underreporting. Wealthy individuals, particularly those with offshore accounts or complex asset structures, may not fully disclose their net worth in surveys. The Fed acknowledges this limitation, noting that self-reported data can underestimate true wealth. Conversely, inflation-adjusted figures from past decades suggest that what percentage of Americans have a net worth of over $1,000,000 has actually declined for middle-class families when accounting for rising costs. In 1989, about 5% of households hit $1M (adjusted for inflation)—today, that figure is lower when adjusted for median wages.3. The wealth gap by race is one of the most glaring inequalities
The racial divide in net worth is stark. White households have a median net worth of $188,200, while Black households sit at $24,100 and Hispanic households at $36,400, according to the Fed. When it comes to what percentage of Americans have a net worth of over $1,000,000, the gap widens further: 22% of white households cross that threshold, compared to just 6% of Black households and 5% of Hispanic households. These disparities stem from historical factors like redlining, predatory lending, and wage gaps—but also from modern barriers like student debt and lack of access to high-paying industries. The data doesn’t lie: wealth is inherited, not just earned. A 2023 study by the Urban Institute found that 60% of wealth transfers (inheritance) go to the top 10% of earners. For families of color, the odds of receiving an inheritance are far slimmer, creating a cycle where wealth accumulation is nearly impossible without external help. This isn’t just an economic issue—it’s a civil rights one. Policies like the Child Tax Credit expansions in 2021 temporarily narrowed the gap, but their expiration reversed progress for millions.4. Age matters more than income in crossing the $1M threshold
You’d assume that high earners are more likely to hit $1M, but the data tells a different story. Age is the strongest predictor of wealth, not salary. The Fed’s data shows that only 2% of households under 35 have a net worth over $1M, compared to 25% of those over 65. This isn’t just about time—it’s about compounding. A 30-year-old with a $100,000 salary may never reach $1M without homeownership, inheritance, or a windfall. Meanwhile, a 60-year-old with a modest income but decades of home equity and retirement savings stands a far better chance. The implication is clear: the system rewards patience. Those who can afford to wait—who don’t need to tap their 401(k) for student loans or medical bills—are the ones who accumulate wealth. For younger generations, the path is far harder. The Great Recession wiped out decades of progress for many, and now, student debt and housing costs mean fewer people can build the kind of asset base needed to cross $1M. Even in high-earning fields like tech or finance, what percentage of Americans have a net worth of over $1,000,000 by 40 remains shockingly low—often under 5%.5. Geography determines who makes it—and who doesn’t
If you live in San Francisco, New York, or Washington, D.C., your chances of hitting $1M are far higher than if you live in Detroit, Cleveland, or rural Texas. The Fed’s data shows that 20% of households in the Northeast have $1M+ net worth, compared to just 7% in the South. This isn’t coincidence—it’s the result of home values, job markets, and cost of living. Take California: 18% of households exceed $1M, but the median home price in San Francisco is $1.3 million. Many "millionaires" are home-rich but cash-poor, with little left after mortgage payments. In contrast, Dallas and Houston have lower home prices but also lower median net worths—meaning fewer people cross the $1M line. The lesson? Location isn’t just about opportunity—it’s about leverage. Those who buy homes in high-appreciation areas early can ride the wealth effect, while others are left behind.6. The rise of the "accidental millionaire" masks deeper inequality
The narrative of the self-made millionaire dominates headlines, but the reality is that most Americans hit $1M through luck, inheritance, or market timing. A 2023 report from the Institute for Policy Studies found that 65% of millionaires derive their wealth from home equity, retirement accounts, or stock market gains—not entrepreneurship. This means that what percentage of Americans have a net worth of over $1,000,000 is heavily dependent on when they bought their first home, how the stock market performed, and whether their parents left them money. The "accidental millionaire" phenomenon also obscures the fact that wealth volatility is real. A single market crash or job loss can erase decades of progress. The Fed’s data shows that net worth drops by 25% or more for 10% of households during recessions. For those near the $1M mark, one bad year can push them back into the middle class. This instability is why liquid wealth (cash, investments) is a better indicator of financial security than total net worth.7. The political implications are undeniable
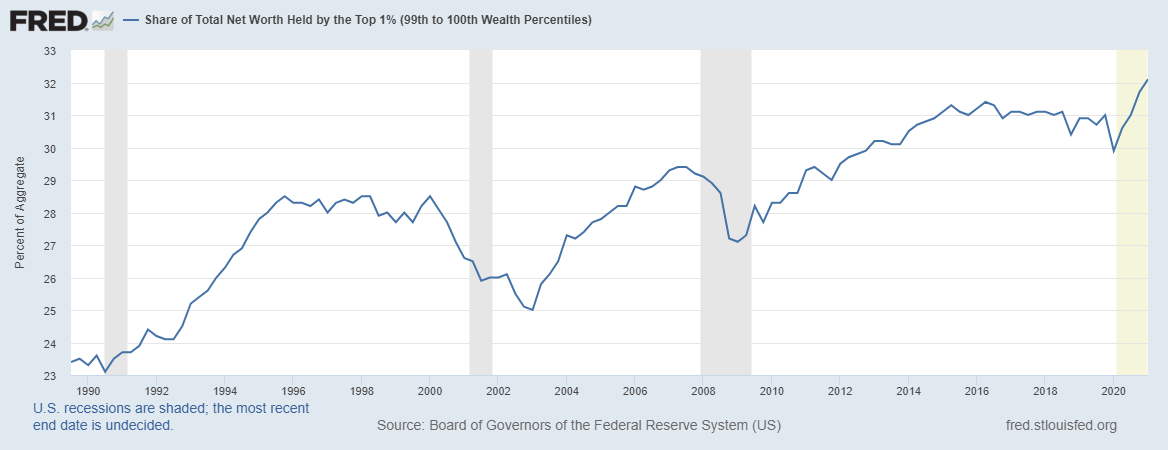
The concentration of wealth at the top has direct political consequences. When what percentage of Americans have a net worth of over $1,000,000 is so low, it means fewer people have the financial freedom to take risks—like starting a business, running for office, or even retiring early. Politicians rely on campaign donations, and 80% of political contributions come from the top 1%. This creates a feedback loop where policies favor the wealthy, further entrenching inequality. Consider capital gains taxes. The top 0.1% pay an effective tax rate of 23.8%, while the bottom 20% pay 30%. This means the ultra-wealthy keep more of their gains, accelerating wealth concentration. Meanwhile, Social Security and Medicare—programs that benefit older, wealthier Americans—face solvency crises, forcing cuts that hurt lower-income retirees. The result? A system where wealth begets more wealth, and those who don’t start with advantages are left behind."Wealth isn’t just about money—it’s about power. And in America, power is increasingly concentrated in the hands of those who already have it." — Darrick Hamilton, economist and professor at The New School

How These Facts Connect
The numbers on what percentage of Americans have a net worth of over $1,000,000 aren’t just statistics—they’re a diagnosis of a broken system. When only 11.5% of households cross that threshold, it means 88.5% are playing a rigged game. The racial wealth gap, the age disparity, and the geographic divide all point to the same conclusion: wealth accumulation in America is less about merit and more about timing, inheritance, and location. Those who benefit from homeownership in high-appreciation areas, stock market booms, or family wealth have a massive head start. Everyone else is left scrambling. The data also reveals why economic mobility is a myth for most Americans. The Fed’s findings show that children of parents in the top 20% are 10 times more likely to reach the top 20% themselves. This isn’t just correlation—it’s causation. Without inherited wealth, access to elite education, or connections in high-paying industries, the odds of hitting $1M are slim. Even high earners in their 40s and 50s often find themselves asset-rich but cash-poor, unable to retire or take financial risks. The result? A society where only the lucky—or the well-connected—get ahead.| Key Factor | Impact on $1M+ Net Worth | Who Benefits Most? |
|---|---|---|
| Age | Only 2% under 35 vs. 25% over 65 | Boomers, Gen X with home equity |
| Race | 22% white vs. 6% Black vs. 5% Hispanic | White households (inheritance, wage gaps) |
| Geography | 20% Northeast vs. 7% South | Coastal city homeowners |
| Wealth Source | 65% from home equity/stocks, not earnings | Those who bought low, sold high |
Conclusion
The question of what percentage of Americans have a net worth of over $1,000,000 isn’t just about counting millionaires—it’s about understanding who has the power to shape America’s future. The numbers show a system where wealth is inherited, not earned, where geography and race determine opportunity, and where most Americans are one bad investment or medical bill away from financial ruin. The 11.5% figure is a starting point, but the real story is in the disparities: why some states have twice the rate of others, why Black and Hispanic households are so far behind, and why age matters more than income. The implications are clear. If only a small fraction of Americans can build generational wealth, then the American Dream is dead for most. The solution isn’t just personal—it’s structural. Policies that expand homeownership, close the racial wealth gap, and reform capital gains taxes could shift the numbers. But without change, what percentage of Americans have a net worth of over $1,000,000 will keep shrinking for the middle class—while the top 1% hoards even more.Comprehensive FAQs
Q: If only 11.5% of Americans have $1M+, does that mean most people will never get there?
A: Statistically, yes—but it’s not inevitable. The top 20% of earners have a far better shot, as do those who inherit wealth, buy homes early, or invest in appreciating assets. However, student debt, stagnant wages, and high housing costs make it nearly impossible for many. The Fed’s data shows that only 1 in 10 households will ever hit $1M without external advantages.
Q: Are there more millionaires now than in the past?
A: Yes, in raw numbers—but not in relative terms. The Fed’s data shows that the percentage of households with $1M+ net worth has stayed roughly flat since the 1980s when adjusted for inflation. However, the ultra-wealthy (those with $10M+) have grown rapidly, thanks to tech booms and private equity. The issue? Most of the gains went to the top 1%, while median net worth stagnated.
Q: Does having a $1M net worth guarantee financial security?
A: No—not if it’s all tied up in a home or illiquid assets. Many "millionaires" are house-rich but cash-poor, meaning they can’t retire early or cover emergencies. The Fed’s data shows that only about 30% of $1M households have $500K+ in liquid assets. Without diversified investments, one bad year can push them back into the middle class.
Q: How does student debt affect the chances of hitting $1M?
A: Devastatingly. The average student loan borrower has $37,000 in debt, which delays homeownership, retirement savings, and investment opportunities. A 2023 study found that graduates with student loans are 30% less likely to reach $1M by age 50 than those without debt. This is why what percentage of Americans have a net worth of over $1,000,000 is so much lower for younger generations.
Q: Could policies like wealth taxes or inheritance reforms change these numbers?
A: Yes—but it’s politically difficult. Countries like Denmark and Sweden use progressive wealth taxes to fund social programs, reducing inequality. In America, proposals like closing the step-up in basis loophole (which lets heirs avoid capital gains on inherited assets) could shift wealth downward. However, lobbying by the ultra-rich has blocked major reforms, ensuring that what percentage of Americans have a net worth of over $1,000,000 remains skewed toward the privileged.
Q: What’s the biggest misconception about millionaires in America?
A: That most are self-made entrepreneurs. The reality? Most millionaires are homeowners, retirees, or beneficiaries of stock market gains—not small business owners. A 2022 study found that only 12% of millionaires made their wealth from business income. The rest came from wages, investments, or inheritance. This debunks the myth that hard work alone guarantees financial freedom.
