
Where It All Began
The first serious attempt to measure what percentage of the population has a net worth of $1 million dollars came in 1989, when the Federal Reserve launched its triennial Survey of Consumer Finances. The results were stark: just 2.1% of households had crossed that threshold. Most of them were white, male, and over 55—heirs to postwar prosperity, homeowners in stable neighborhoods, beneficiaries of employer pensions. The millionaire wasn’t a tech CEO or a hedge fund manager. They were the quiet winners of an economy that still rewarded steady work over speculation. The early 1990s were a period of stagnation. Wages flatlined, healthcare costs rose, and the savings rate hovered near zero. Yet even then, the seeds of change were planted. The repeal of Glass-Steagall in 1999 allowed banks to merge commercial and investment banking, creating the financial products that would later fuel both wealth and crisis. Meanwhile, the rise of index funds and 401(k)s democratized investing—if only slightly. By 2001, the percentage of households with what percentage of the population has a net worth of $1 million dollars had inched up to 3.2%. The growth was slow, but the trend was clear: wealth accumulation was becoming less about inheritance and more about asset exposure.The Early Signs
The dot-com bubble wasn’t just a speculative frenzy. It was a dress rehearsal for the wealth explosion to come. In 1995, only 0.5% of households under 35 had a net worth of $1 million. By 2000, that number had jumped to 1.2%—mostly young professionals who’d cashed out stock options or sold their startups to bigger firms. The bubble’s collapse in 2000-2002 wiped out paper fortunes, but the lesson was already learned: tech and finance could mint millionaires faster than traditional paths. The real turning point wasn’t the bubble itself, but what followed. The early 2000s saw the rise of private equity, leveraged buyouts, and the unshackling of executive pay. CEOs who’d once earned 20 times their average worker’s salary now made 300 times as much. Meanwhile, the middle class was told to rely on home equity and retirement accounts—both of which required time, stability, and good luck. The stage was set for a wealth divide that would only widen.The Turning Point
The 2008 financial crisis didn’t destroy wealth. It redistributed it. While the S&P 500 recovered by 2013, the median household net worth remained 13% below its 2007 peak. The top 1% saw their net worth grow by 11% over the same period. By 2016, the percentage of households with what percentage of the population has a net worth of $1 million dollars had surged to 7.2%. The reason? The Fed’s balance sheet expansion, which pushed asset prices higher. Real estate in coastal cities became unaffordable, but for those who already owned, it was a windfall. The crisis also exposed the fragility of the middle class. Those with no savings, no college degrees, and no home equity were left with debt and no safety net. The recovery that followed wasn’t shared. While the rich got richer from stock market gains, the poor got poorer from stagnant wages. The gap wasn’t just in net worth—it was in opportunity.“You don’t build wealth on a salary. You build it on assets.” — Warren Buffett, 2013The quote captured the shift perfectly. The new millionaires weren’t inheriting family businesses. They were buying rental properties, flipping houses, or betting on startups. The old rules—save, invest, retire—were still valid, but they were no longer enough.

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2000-2007 |
|
| 2008-2015 |
|
| 2016-Present |
|
Lessons From the Journey
- Wealth is geographic. The top 10% in San Francisco have a median net worth of $2.8 million. In Youngstown, it’s $120,000.
- Age matters more than income. A 60-year-old with a pension and home equity is far more likely to be a millionaire than a 30-year-old with a six-figure salary.
- Inheritance accelerates wealth. 30% of millionaires inherit at least part of their fortune.
- Debt is the great equalizer. Student loans and medical bills can derail asset accumulation for decades.
- Policy shifts have outsized effects. The 2017 Tax Cuts and Jobs Act boosted capital gains taxes for the wealthy, but the stock market rally that followed benefited existing investors more than savers.
- The millionaire threshold is arbitrary. A family in Miami needs $1.5M to live like the Joneses. In rural Iowa, $800K suffices.
Where Things Stand Today
As of 2023, what percentage of the population has a net worth of $1 million dollars in the U.S. sits at 11.7%, according to the Fed’s latest data. But the number is a moving target. The 2024 election, inflation, and potential recessions could shift it dramatically. What’s clear is that the millionaire class is younger, more diverse in some cities, and more reliant on alternative assets like crypto and private equity. The biggest wild card? Housing. In 2020, home equity accounted for 50% of the net worth of millionaires. But with mortgage rates near 7%, many are locking in low rates or selling properties at peak values. The question now isn’t just what percentage of the population has a net worth of $1 million dollars, but whether that wealth is liquid—or just paper gains waiting to be tested by a downturn.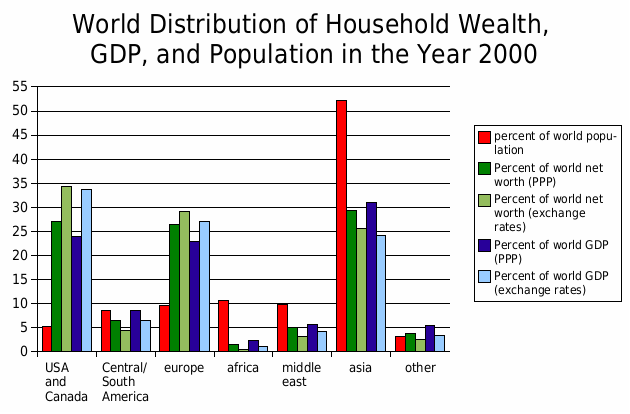
Conclusion
The story of what percentage of the population has a net worth of $1 million dollars is more than a statistical footnote. It’s a reflection of an economy that rewards patience, risk-taking, and—above all—luck. The millionaires of today are not just the heirs of the past. They’re the beneficiaries of a financial system that has tilted toward asset holders, away from wage earners. The data shows a clear pattern: those who own stocks, real estate, or businesses are the ones who’ve seen their net worth grow. Those who don’t? They’re playing catch-up in an economy that moves faster every year. The real question isn’t how many households have crossed the $1 million mark. It’s whether that number will keep rising—or if the next crisis will reveal how fragile that wealth truly is.Comprehensive FAQs
Q: How does the percentage of millionaires vary by state?
The top five states with the highest share of households worth $1M+ are:
- Maryland (18.5%)
- New Jersey (17.2%)
- Hawaii (16.8%)
- Connecticut (16.5%)
- Washington (15.9%)
Q: Are millionaires mostly white?
Yes. In 2022, 78% of millionaire households were white, 8% were Black, and 10% were Hispanic. However, the gap is narrowing among younger cohorts, particularly in cities like Atlanta and Dallas, where Black and Latino entrepreneurs are building wealth through business ownership.
Q: Does having a college degree increase the odds of becoming a millionaire?
Absolutely. 50% of millionaires have at least a bachelor’s degree, compared to 30% of the general population. Advanced degrees (MBAs, law, medicine) further boost odds, but the correlation isn’t absolute—many self-made millionaires are college dropouts who succeeded in tech, real estate, or trades.
Q: How many millionaires are there globally?
Credit Suisse’s 2023 Global Wealth Report estimates there are 59.4 million millionaires worldwide (in USD terms). The U.S. leads with 23.7 million, followed by China (6.3 million) and Japan (4.2 million). The number has grown 12% annually since 2016, driven by stock markets and rising asset prices.
Q: Can you be a millionaire on a modest salary?
It’s possible but rare. Most millionaires under 50 have multiple income streams (rental income, side businesses, investments). The average millionaire’s primary job pays $150K–$250K, but their wealth comes from assets, not salary. Frugality and long-term investing are key—many millionaires live below their means for decades.
Q: What’s the biggest mistake people make when trying to reach $1M?
Assuming time alone will do it. The three biggest pitfalls are:
- Overestimating returns. Assuming 10% annual gains on investments without adjusting for inflation or fees.
- Ignoring debt. Carrying high-interest debt (credit cards, student loans) can erase decades of savings.
- Not diversifying. Putting all wealth into a single asset (e.g., a single stock or property) is risky.
Q: Will the percentage of millionaires keep rising?
Likely, but not linearly. Factors that could accelerate growth:
- Continuing stock market gains (though valuations are high).
- Remote work driving up home values in secondary markets.
- More people investing in crypto, private equity, or alternative assets.
- Inflation eroding real returns.
- Recessions wiping out paper wealth.
- Policy changes (e.g., higher capital gains taxes).
