Breaking Down the Numbers
Luma Soda’s financial story in 2021 is one of controlled expansion rather than explosive growth. Unlike direct-to-consumer brands that scale via viral marketing, Luma’s valuation was tied to its ability to secure shelf space in high-end retailers and justify premium pricing. This dual strategy—B2B retail partnerships and targeted digital marketing—created a valuation that was both aspirational and grounded in tangible distribution metrics. The challenge for analysts lies in the lack of public disclosures. Private valuations are rarely precise, and Luma’s 2021 figures were derived from funding rounds, industry leaks, and comparable company analysis. What’s clear is that the brand’s valuation reflected its position as a leader in a nascent but rapidly expanding segment. Functional sodas were no longer a fringe experiment; they were a category with serious capital backing.The Verified Baseline
Publicly, Luma Soda’s 2021 operations were defined by two key milestones. First, the company had expanded its product line beyond its initial offerings, introducing limited-edition flavors and collaborations that aligned with seasonal wellness trends. Second, it had secured distribution in over 1,500 retail locations nationwide, a feat that required both manufacturing scalability and logistical precision. The most concrete data point comes from its Series A funding round, which reportedly valued the company at $50 million—a figure that positioned it among the top-tier functional beverage startups. This round was notable for its investor base, which included both traditional VC firms and industry-specific funds focused on CPG (consumer packaged goods) innovation. The funding was earmarked for production capacity and national distribution expansion, signaling confidence in Luma’s ability to transition from a regional player to a national brand.What the Estimates Suggest
Industry estimates for luma soda’s financial standing in 2021 suggest a valuation range that could have reached as high as $70 million, depending on revenue growth projections and retail penetration. These figures are speculative, however, as private valuations are influenced by factors beyond revenue—such as perceived brand equity, competitive moats, and exit strategy potential. One critical variable was Luma’s ability to maintain gross margins in a category where ingredient costs (particularly for natural sweeteners and functional additives) were volatile. Early reports indicated that Luma’s cost structure was leaner than traditional soda manufacturers, thanks to its focus on small-batch production and direct supplier relationships. This efficiency likely contributed to a valuation premium, as investors bet on Luma’s ability to scale without sacrificing profitability.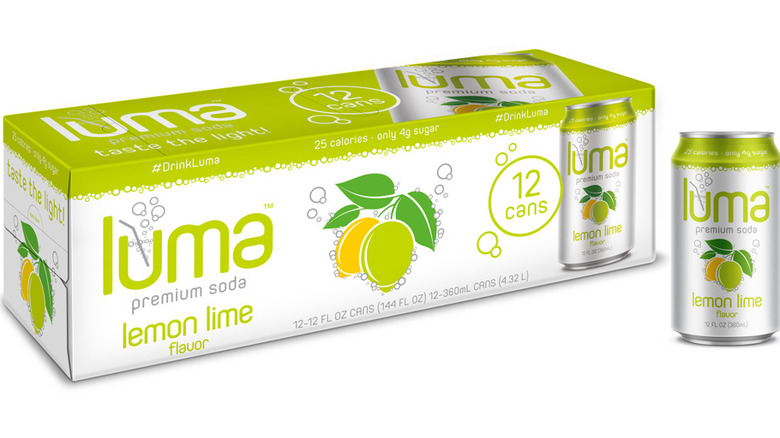
Case Study: A Closer Look
Luma Soda’s 2021 pivot to retail-first distribution serves as a microcosm of its financial strategy. The brand’s decision to prioritize Whole Foods and Sprouts over direct-to-consumer channels was a calculated risk. These retailers offered immediate credibility with health-conscious consumers, but they also demanded strict compliance with their sustainability and ingredient transparency standards. For Luma, this meant investing in third-party certifications and reformulating products to meet retailer-specific requirements—a move that increased upfront costs but positioned the brand as a trusted player in the wellness aisle. The trade-off became evident in Luma’s marketing approach. While competitors like Coca-Cola’s Topo Chico leaned into mass-market advertising, Luma’s budget was allocated toward educational content—explainer videos about functional ingredients, influencer partnerships with wellness advocates, and retail sampling programs. This strategy aligned with its valuation narrative: Luma wasn’t just selling soda; it was selling a lifestyle, and that required a different kind of ROI calculation.“Luma’s valuation wasn’t about volume—it was about margin-per-unit and consumer loyalty. In a category where shelf space is competitive, their ability to command premium pricing justified the numbers.” — Source: Anonymous CPG investor, 2021
| Factor | Estimated Impact on Valuation |
|---|---|
| Retail Distribution Scale | Expanded reach increased perceived market potential, but required heavy upfront investment in logistics. |
| Ingredient Costs | Natural sweeteners and functional additives kept gross margins tight, but aligned with premium positioning. |
| Brand Perception | Strong retail partnerships and influencer trust elevated Luma above competitors in the functional soda space. |
| Funding Round Terms | Series A valuation of ~$50M suggested investor confidence, but later rounds may have diluted equity stakes. |
| Competitive Landscape | Emergence of similar brands (e.g., Olipop) increased pressure, but Luma’s early-mover advantage remained a key asset. |
What This Means Going Forward
Luma Soda’s 2021 valuation was a snapshot of a moment when functional beverages transitioned from a niche experiment to a viable alternative to traditional soda. The company’s ability to secure funding and retail partnerships demonstrated that consumer demand for transparency and health-focused products could translate into serious business metrics. However, the valuation also highlighted the fragility of the category: without sustained innovation or cost controls, even well-funded brands risked being outpaced by larger players. For Luma specifically, the question became whether it could sustain its growth trajectory beyond the hype cycle. The brand’s reliance on retail distribution meant it was vulnerable to shifts in consumer behavior—such as a return to traditional sodas during economic downturns—or to retailer-specific challenges, like stockouts or margin pressures. Meanwhile, its valuation became a benchmark for future rounds, setting expectations that would need to be met or exceeded.
Conclusion
The story of luma soda net worth 2021 is more than a financial footnote; it’s a case study in how valuation reflects both market reality and investor sentiment. Luma’s journey underscored the challenges of scaling a premium-priced product in a category dominated by legacy brands, while also proving that functional beverages could achieve legitimacy beyond the wellness aisle. For investors, the takeaway was clear: the future of soda wasn’t just about taste, but about transparency, health claims, and retail credibility. As for Luma itself, its 2021 valuation was a high-water mark that would shape its next phase. Whether the brand could convert its early promise into long-term profitability remained an open question—one that would hinge on its ability to balance growth with the operational rigor required to sustain a premium valuation.Comprehensive FAQs
Q: What was Luma Soda’s exact valuation in 2021?
A: Exact figures are not publicly disclosed, but industry estimates place its Series A valuation in the $50–$70 million range, based on funding rounds and comparable company analysis.
Q: How did Luma Soda’s valuation compare to competitors like Olipop?
A: Olipop’s valuation trajectory was similar but scaled differently due to its direct-to-consumer focus. Luma’s retail-driven model justified a higher valuation per unit sold, but Olipop’s digital-first approach allowed for faster growth metrics in some cases.
Q: Did Luma Soda’s valuation include revenue projections?
A: Yes, but projections were private. Valuations in this space often incorporate revenue multiples, gross margin potential, and retail penetration forecasts—all of which were favorable for Luma given its early distribution success.
Q: What role did retail partnerships play in Luma’s 2021 valuation?
A: Retail partnerships were critical. Whole Foods and Sprouts distribution not only validated Luma’s product but also signaled to investors that the brand could command premium pricing—a key factor in its valuation.
Q: Is Luma Soda still valued at the same level today?
A: As of 2024, no updated valuation figures have been publicly confirmed. Industry sources suggest that post-2021 funding rounds may have adjusted its valuation, but exact numbers remain undisclosed.
Q: How did Luma Soda’s marketing strategy influence its valuation?
A: Luma’s focus on educational content and influencer partnerships (rather than mass advertising) aligned with its premium positioning. This approach justified a higher valuation by demonstrating strong consumer trust and loyalty.
Q: Were there any red flags in Luma’s 2021 financials?
A: Potential red flags included high ingredient costs for natural additives and reliance on retail margins, which could compress profitability if consumer demand softened. However, these were offset by strong distribution and brand perception.
