Where It All Began
The roots of this paradigm stretch back to the 1970s, when old-money families in Europe and the U.S. first noticed a glaring flaw in traditional wealth metrics. Net worth—assets minus liabilities—had long been the gold standard, a number whispered in vaults and printed in Forbes’ annual lists. But during the oil shocks of the ’70s, even blue-chip stocks and bonds turned to dust when liquidity dried up. A German industrialist, whose family’s fortune was tied to steel mills, found himself unable to meet payroll because his shares were illiquid. His net worth on paper was €500 million. His ability to operate? A fraction of that. The early signs were subtle but undeniable. In 1982, a study by the Bank for International Settlements revealed that during the Latin American debt crisis, countries with higher liquid asset reserves—hard currency, gold, and short-term securities—weathered the storm while those relying on net worth alone collapsed. The message was clear: liquid assets more than net worth when markets seized up. By the late ’80s, Swiss private banks began quietly advising clients to hold 20–30% of their wealth in cash equivalents, not as a safety net, but as a strategic weapon.The Early Signs
The shift gained momentum in the 1990s, as technology and globalization introduced new risks. A hedge fund manager in Hong Kong, who had made his name trading Asian currencies, watched as his net worth—backed by a mix of real estate and stocks—plummeted during the 1997 Asian financial crisis. His properties lost 60% of their value. His stocks? Another 50%. But his $120 million in U.S. Treasury bills and Eurodollar deposits remained untouched. That liquidity let him short the baht, buy undervalued Korean conglomerates, and emerge richer than ever. The lesson spread: liquid assets more than net worth in a world where assets could become liabilities overnight. Meanwhile, in the art world, dealers noticed something similar. A Russian oligarch might own a Picasso worth $150 million, but selling it would take six months, trigger capital controls, and invite scrutiny. His real leverage? The $50 million in Swiss francs he could wire to Monaco the next day. The oligarch’s net worth was a headline. His liquid asset firepower was what got deals done.The Turning Point
The 2008 crisis didn’t just accelerate the trend—it redefined it. For the first time, the gap between net worth and usable capital became a matter of survival. A New York law firm’s analysis of ultra-high-net-worth families showed that those with liquid assets more than net worth ratios above 30% not only survived the crash but expanded their holdings while others liquidated. The reason? Illiquid assets like private equity, real estate, and collectibles became toxic. Banks stopped lending against them. Buyers vanished. Even the richest families found their "wealth" trapped in balance sheets. The turning point wasn’t just financial. It was psychological. For the first time, liquid assets more than net worth became the silent metric of real power. A family’s net worth might be $1 billion, but if $800 million of that was tied up in a vineyard, a shipping fleet, or a tech startup with no exit, their options were limited. The new elite? Those who held cash, gold, and marketable securities—assets that could be deployed instantly, without negotiation or discount."In 2008, we saw something we’d never seen before: people with $100 million in net worth begging for $10 million in cash loans. The banks didn’t care about their yachts or their art. They cared about what they could seize—and what they could lend against. That’s when the game changed forever." — Geneva-based private banker, 2010

The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1997–2001 | Asian financial crisis exposes illiquidity risks. Hedge funds and sovereign wealth funds begin holding 25–40% of portfolios in cash/T-bills. Art and real estate become "decorative" assets rather than liquid wealth. |
| 2002–2007 | Private equity boom inflates net worth numbers, but dry powder (cash reserves) becomes the real currency. LBOs fail when sponsors can’t meet margin calls—illiquid assets become liabilities. |
| 2008–2012 | Liquidity crisis forces revaluation: families with liquid assets more than net worth ratios above 30% thrive. Banks prioritize cash collateral over illiquid assets. "Net worth" becomes a lagging indicator. |
| 2013–Present | UHNWIs shift to "liquidity-first" portfolios: 40–60% in cash, gold, and short-duration bonds. Private credit and distressed debt become primary investment vehicles. Liquid assets more than net worth is now the default strategy. |
Lessons From the Journey
- Net worth is a snapshot. Liquid assets are the operating system. A $100 million net worth means nothing if $90 million is locked in a single asset.
- Cash is king in crises. During 2008, families with high liquidity ratios bought assets at fire-sale prices while others were forced to sell.
- Illiquid assets are leverage, not wealth. A private jet or a vineyard may appreciate—but they don’t pay salaries or fund acquisitions.
- Liquidity begets opportunity. The ability to deploy capital instantly creates arbitrage opportunities others can’t access.
- Taxes and regulations favor liquidity. Holding cash in multiple jurisdictions reduces exposure to capital controls and wealth taxes.
- The richest families now structure portfolios around liquid assets more than net worth—even if it means lower "paper" wealth on balance sheets.
Where Things Stand Today
Today, the divide between net worth and liquidity is wider than ever. A 2023 study by UBS found that the top 1% of global wealth holders now allocate 45% of their portfolios to cash, gold, and short-term securities—up from 20% in 2008. The reason? Liquid assets more than net worth isn’t just a strategy; it’s a survival mechanism in an era of geopolitical fragmentation, regulatory unpredictability, and market volatility. Consider the case of a Middle Eastern sovereign wealth fund that held $200 billion in assets—but only $50 billion was truly liquid. When oil prices collapsed in 2020, the fund’s net worth dropped by 30%. But its liquid asset base let it stabilize currencies, buy distressed European bonds, and emerge as a major player in global markets. The lesson? Liquid assets more than net worth in determining who wins when systems fail.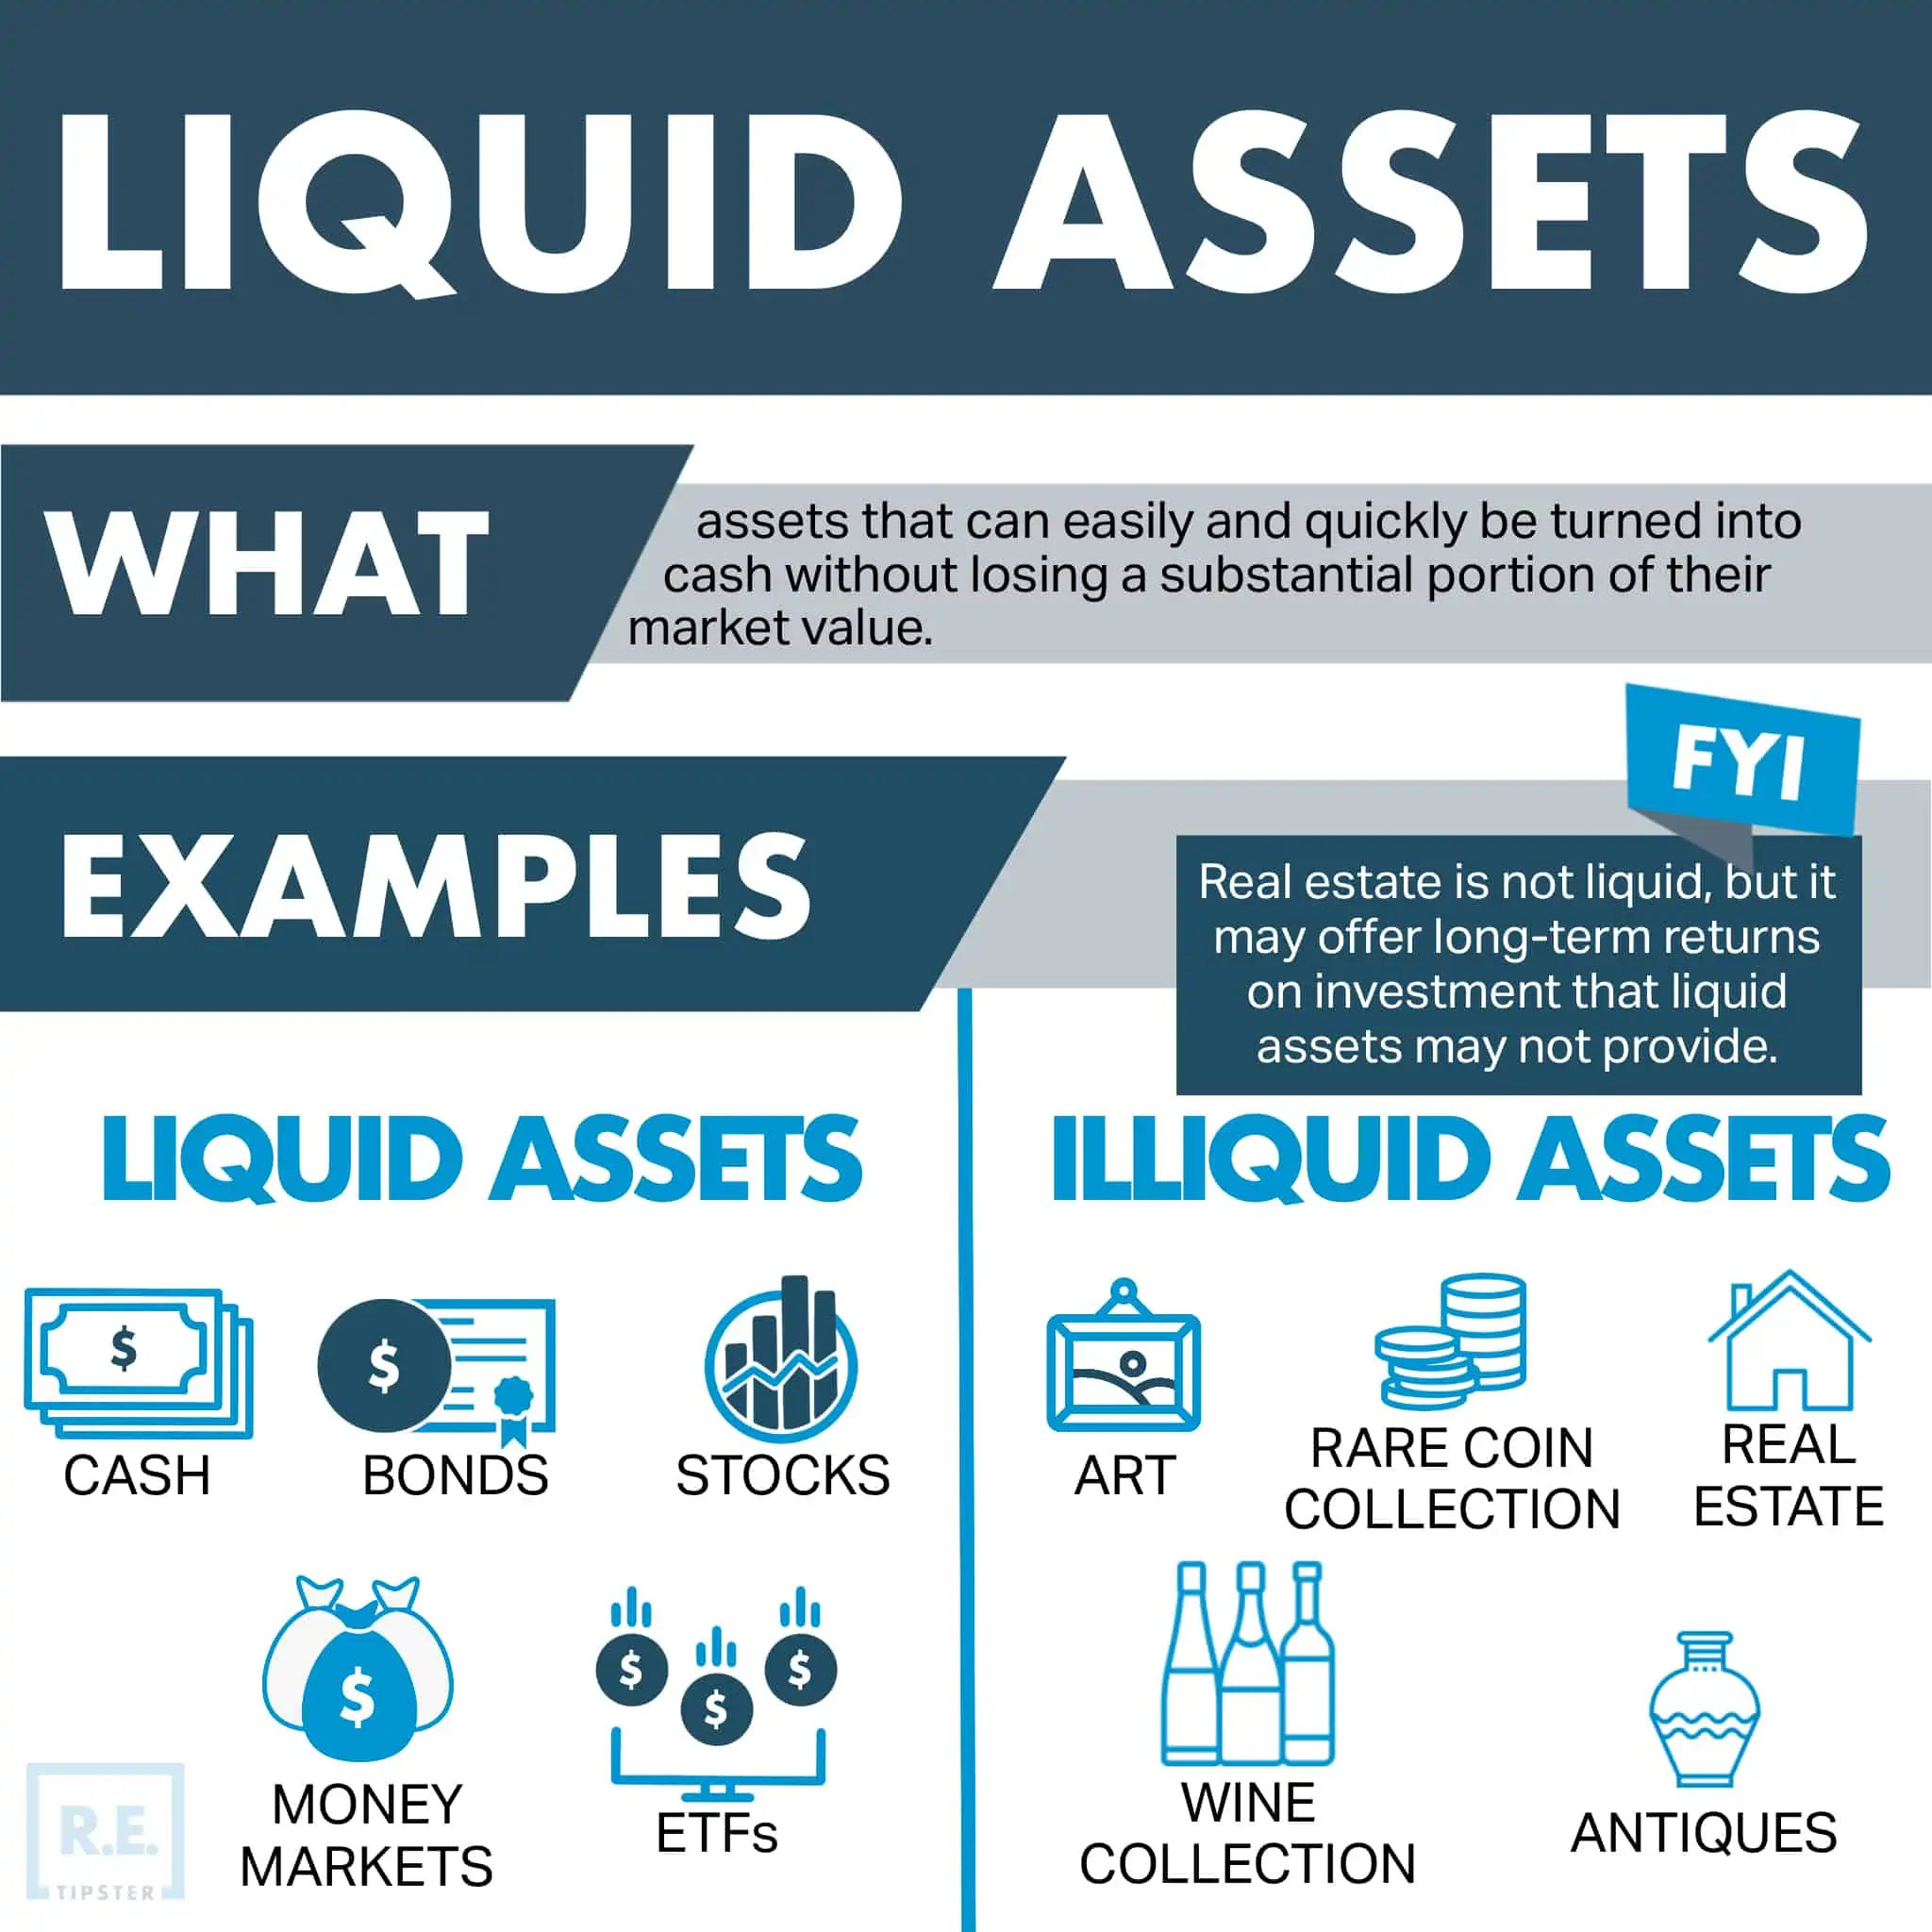
Conclusion
The obsession with net worth—once the ultimate measure of success—has given way to a quieter, more pragmatic truth: liquid assets more than net worth when it matters. Whether it’s buying a company at a discount, weathering a currency crisis, or simply writing a check without hesitation, the real wealth lies in what can be deployed, not what’s listed on a balance sheet. The shift isn’t just financial. It’s cultural. The new elite don’t flaunt their net worth. They control their liquidity. And in a world where assets can turn to dust overnight, that’s the only currency that truly matters.Comprehensive FAQs
Q: Why do ultra-high-net-worth individuals prioritize liquid assets over net worth?
Because net worth is a static number—what matters is usable capital. A $1 billion net worth means little if $900 million is tied up in illiquid assets like private equity, real estate, or art. Liquid assets more than net worth in determining who can act quickly in crises, seize opportunities, or avoid forced sales.
Q: How much of a portfolio should be in liquid assets?
There’s no one-size-fits-all answer, but industry estimates suggest 30–50% for high-net-worth individuals, rising to 50–70% for those in volatile regions or sectors. The goal isn’t just safety—it’s strategic agility. Families with higher liquidity ratios often outperform in downturns.
Q: Can liquid assets still lose value?
Yes—but less so than illiquid assets. Cash loses to inflation, but gold and short-term bonds provide stability. The key is diversification within liquidity: holding cash in multiple currencies, gold, and high-grade bonds to hedge against different risks.
Q: What happens if you hold too much in liquid assets?
Opportunity cost. If 60% of a portfolio is in cash, it may underperform in bull markets. The balance depends on risk tolerance and strategic needs—some families hold more liquidity to exploit crises, while others prioritize growth.
Q: How do I calculate my liquid asset ratio?
Divide your cash + marketable securities (stocks, bonds, ETFs) + gold by your total net worth. For example, if you have $50 million in liquid assets and $200 million in net worth, your ratio is 25%. The higher, the more operational flexibility you have.
Q: Are there tax advantages to holding liquid assets?
Yes, but it depends on jurisdiction. In some countries, holding cash in offshore accounts reduces wealth taxes. Others favor gold or short-term bonds for tax efficiency. Always consult a cross-border tax advisor—liquidity strategies often intersect with tax optimization.
