The Short Answers
- Lifesum’s net worth is estimated between £100 million and £200 million, though exact figures are private.
- The company’s valuation is tied to its B2B corporate wellness contracts, not just consumer app revenue.
- Unlike public health-tech firms, Lifesum’s growth has been fueled by retained earnings and strategic funding, not IPOs.
- Its valuation reflects challenges in monetizing free-tier users—a common pain point in the nutrition-app space.

Deep Dive: The Full Picture
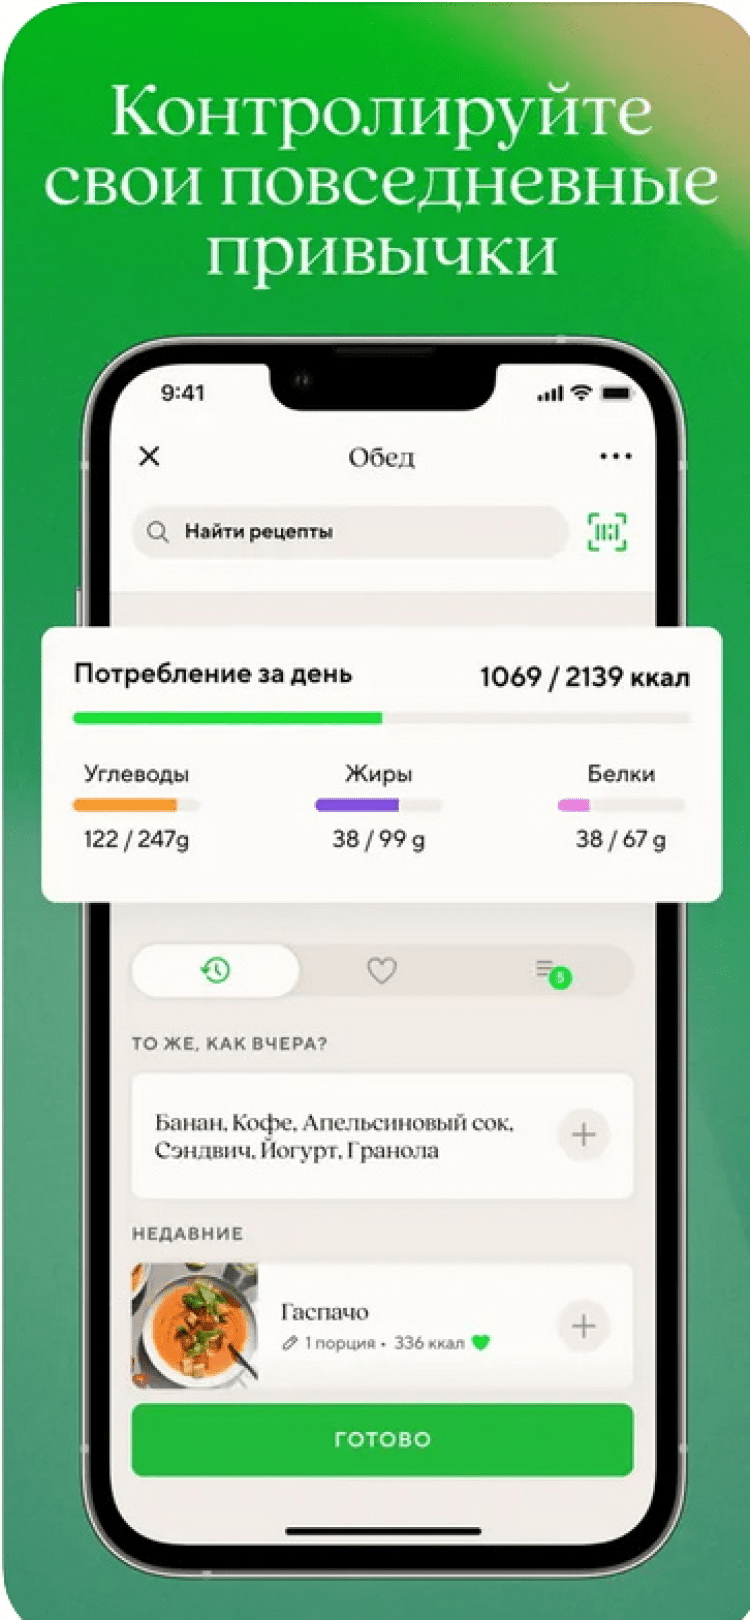
Lifesum’s financial narrative begins in 2015, when it raised €10 million from Nordic investors, a round that set the stage for its expansion beyond Sweden. The app’s strength lay in its algorithm-driven meal plans, which appealed to both health-conscious individuals and employers looking to slash employee healthcare costs. By 2018, it had secured another €15 million, this time from a mix of venture capital and corporate backers—including a notable investment from Schibsted, the Norwegian media conglomerate. These rounds weren’t just about growth; they were about proving Lifesum could scale without the aggressive user-acquisition burns of its competitors. The company’s valuation trajectory became clearer in 2020, when reports emerged of a €50 million funding round at a valuation nearing €200 million. This wasn’t a traditional VC check; it was a strategic injection from existing shareholders, including Schibsted and the founders themselves. The timing was deliberate. The pandemic had supercharged demand for digital wellness tools, and Lifesum’s corporate wellness arm—Lifesum for Business—was suddenly in high demand. Yet the valuation wasn’t just about market conditions. It also reflected Lifesum’s ability to convert free users into paying subscribers at rates higher than industry averages, though still far from profitable.The Context You Need
The nutrition-app market is a graveyard of high valuations and low conversions. MyFitnessPal’s acquisition proved that user scale alone doesn’t guarantee success; monetization is the real acid test. Lifesum’s approach has been to double down on B2B, where annual contracts with companies like IKEA and Telia provide recurring revenue streams. This model insulates it from the whims of consumer app trends, but it also caps its potential. A company valued at £150 million with millions of free users is a different beast from a SaaS unicorn with predictable margins. The other context is Europe’s health-tech funding landscape. Unlike the U.S., where health apps often secure massive rounds, European investors favor slow, sustainable growth. Lifesum’s valuation isn’t about hypergrowth; it’s about asset light scalability. Its database of user preferences is its most valuable asset—not just for meal plans, but as a behavioral data goldmine for corporate wellness programs. This dual revenue stream explains why Lifesum’s net worth isn’t a single number, but a range tied to its two business pillars.The Mechanics
Lifesum’s revenue model is a hybrid of freemium monetization and enterprise licensing. The consumer app generates income through premium subscriptions (€9.99/month), but the real engine is its B2B platform, where companies pay €5–€15 per employee per year for customized wellness programs. This structure creates a recurring revenue flywheel: happy corporate clients mean stickier employee retention, which in turn attracts more businesses. The challenge? Unit economics. While Lifesum’s customer acquisition cost (CAC) is lower than rivals like Noom, its lifetime value (LTV) per user remains modest. The company’s valuation assumes it can increase LTV through upsells—like its Lifesum Pro tier or add-ons like meal-kit integrations. Yet in a market where 80% of users never pay, even small shifts in conversion rates can dramatically alter its net worth trajectory. The mechanics aren’t just about code; they’re about psychological triggers—nudging users from free to paid without alienating them.Details That Change the Picture
Lifesum’s valuation isn’t just about today’s numbers; it’s about what it could become. The company’s refusal to pursue an IPO or aggressive expansion into the U.S. has kept its financials under wraps, but it’s a calculated move. Private equity allows for longer timelines, where the focus is on marginal improvements rather than quarterly growth. This patience is evident in its 2022 restructuring, where it laid off 15% of its workforce—not a sign of distress, but a pruning of non-core functions to sharpen its B2B focus. The other wild card is data monetization. Lifesum’s trove of user behavior data isn’t just for meal plans; it’s a negotiating chip in corporate wellness deals. Companies pay premiums for insights into employee health trends, turning Lifesum’s app into a two-way value exchange. This isn’t speculative—it’s a proven model in Europe, where data-driven HR is becoming standard. The question is whether Lifesum can export this model to markets where privacy laws and corporate cultures differ."Lifesum’s valuation isn’t about how many people use the app—it’s about how many companies pay to keep them engaged. That’s a different math entirely." — Health-tech analyst at Nordic Capital
| Metric | Estimated Range |
|---|---|
| Total Valuation (2023) | £100M–£200M |
| Annual Revenue (2023) | £20M–£35M |
| B2B Revenue Share | 60–70% |
| Free vs. Paid Users | 90% free, 10% paying |
Conclusion
Lifesum’s net worth is a study in quiet ambition. It’s not chasing the next MyFitnessPal-style exit; it’s building a self-sustaining ecosystem where corporate wellness and consumer habits feed each other. The valuation figures—whatever they are—aren’t the end goal. They’re a benchmark for a company that measures success in retention, not hype. In an era where health-tech valuations are inflated by VC euphoria, Lifesum’s approach feels almost old-school: profitability before scale. Yet the question remains: Can this model survive beyond Europe? The U.S. market is vast, but it’s also fragmented and privacy-sensitive. Lifesum’s valuation will only tell the full story when it either expands aggressively or stays the course, proving that niche dominance can outlast the noise. For now, its net worth is less about a number and more about what it chooses to prioritize.Comprehensive FAQs
Q: Is Lifesum profitable?
Lifesum has never disclosed exact profit margins, but industry estimates suggest it broke even on a net basis by 2021, thanks to its B2B revenue streams. Profitability in the consumer app space is rare, but Lifesum’s corporate contracts provide a stable cash flow that offsets free-user costs.
Q: How does Lifesum’s valuation compare to competitors?
Direct comparisons are tricky, but Lifesum’s £100M–£200M range is far lower than MyFitnessPal’s $475M exit. However, it’s higher than most pure-play nutrition apps because of its B2B model. For context, Noom (a competitor) raised $350M at a $1.7B valuation in 2021—but burned cash aggressively. Lifesum’s valuation reflects sustainability over speed.
Q: Why hasn’t Lifesum gone public?
Going public would dilute founder control and subject it to quarterly earnings pressure, which clashes with its long-term strategy. Private equity also allows for flexibility in R&D spending, particularly in AI-driven personalization—a key differentiator. The company has no urgency to exit; its valuation is negotiated privately, not dictated by market sentiment.
Q: What’s the biggest risk to Lifesum’s valuation?
The conversion rate of free users is the biggest wild card. If Lifesum can’t increase its paid subscriber ratio beyond 10–12%, its consumer app revenue will stagnate. The other risk is B2B churn—if corporate clients shift to cheaper alternatives or in-house solutions, its recurring revenue model could weaken. Both depend on economic conditions, not just tech trends.
Q: Could Lifesum be acquired?
An acquisition is plausible but not imminent. Potential buyers include larger health-tech firms (like Teladoc or Virgin Pulse) or corporate wellness platforms looking to integrate its data. However, Lifesum’s private valuation gives it leverage—sellers would need to offer significantly more than its current range to attract founder interest. For now, strategic partnerships (like its deal with IKEA) are more likely than a full buyout.
Q: How does Lifesum’s data monetization work?
Lifesum’s user behavior data is anonymized and aggregated before being sold to corporate clients. For example, a company might pay a premium to see trends in employee sugar intake or meal-planning adherence. This isn’t raw personal data—it’s population-level insights used to design wellness programs. The revenue from these B2B data packages can double the ARPU (average revenue per user) for corporate clients.
