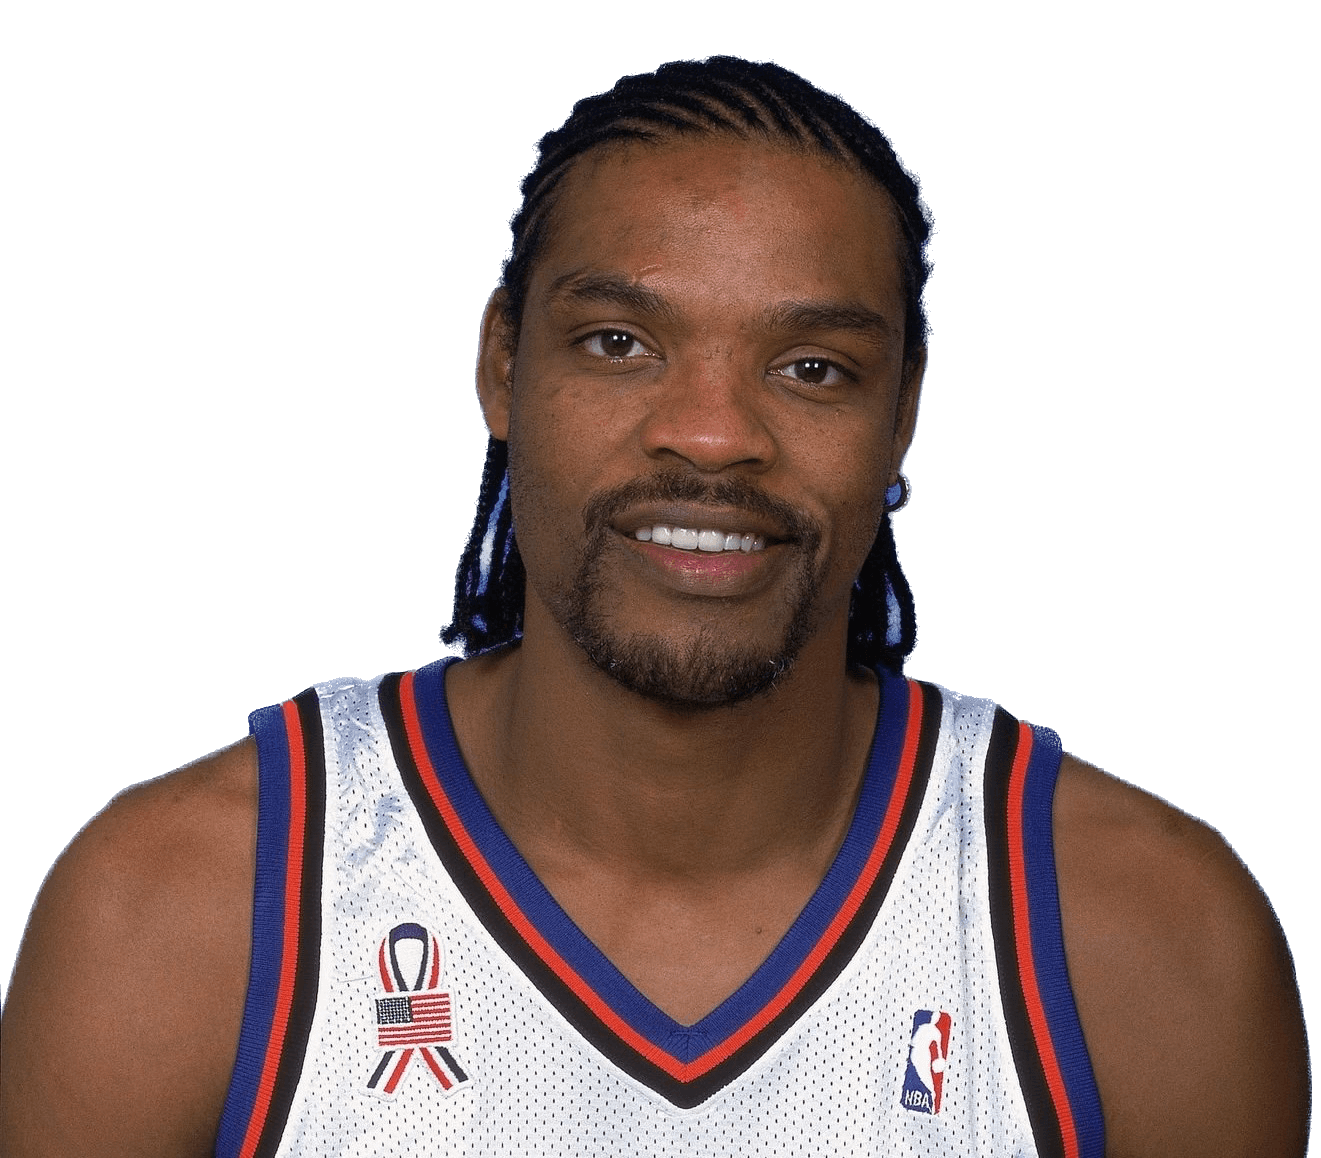
The Short Answers
- Sprewell’s NBA pension is tied to his 13-year career, with payments structured based on service time and vesting rules.
- Accessing early pension benefits typically requires meeting specific age or service thresholds, though hardship clauses exist.
- Legal disputes over pension withdrawals can drag on for years, as seen in Sprewell’s case involving the NBAPA and league.
- Players with disciplinary issues (like Sprewell’s 1997 suspension) may face restrictions on pension access or benefits.
- The NBA pension plan is funded by player contributions during their careers, with the league matching a portion.

Deep Dive: The Full Picture
The NBA’s pension system operates like a 401(k) with stricter vesting requirements. Players contribute a percentage of their salary (currently 10% for veterans), and the league matches those contributions up to a cap. For Sprewell, whose peak earnings were in the late 1990s, his pension pot grew over years of service—but its value became a contentious issue when he sought early access. The NBAPA’s rules state that players can withdraw vested funds at age 50, but Sprewell, then in his late 40s, argued his financial distress warranted earlier access. His case revealed how the system’s rigid structure clashes with players’ unpredictable post-career needs. What makes Sprewell’s situation unusual is the intersection of his pension fight with his public persona. Known for his volatile on-court behavior and later legal troubles (including a 2008 arrest for domestic violence), his financial struggles—reportedly tied to unpaid debts and failed business ventures—painted a picture of a player who burned through earnings long before retirement. The NBA’s pension plan doesn’t account for such personal failures, leaving players like Sprewell to navigate a system that offers little flexibility. His legal battle over pension withdrawals became a proxy for broader questions: How much should the league prioritize financial responsibility over humanitarian concerns?The Context You Need
The NBA’s pension plan was overhauled in 2011 to align with modern financial realities, shifting from defined benefits to a hybrid model. Before that, players could retire at 35 with full benefits—a rule that favored longevity over short-term careers. Today, the plan is more actuarial, with payouts based on years of service and age. For Sprewell, who left the league in 2008 after 13 seasons, his pension was vested but not yet fully accessible. The NBAPA’s hardship clause allows early withdrawals for medical or financial emergencies, but Sprewell’s request was denied initially, setting off a legal standoff. The tension in Sprewell’s case stems from the NBA’s dual role as both employer and gatekeeper of player finances. The league argues that early withdrawals set a precedent that could destabilize the pension fund, while players like Sprewell contend that the system fails to address real-world crises. His fight also underscores a generational divide: older players, like Sprewell, entered the league under different pension rules, while younger stars now face a 401(k)-style plan with higher contribution requirements.The Mechanics
Sprewell’s pension is calculated using a formula tied to his salary history and service time. For players with 10+ years, the plan provides a monthly annuity starting at age 50, with the amount based on a percentage of their peak earnings. Early withdrawals are permitted under hardship, but the NBAPA reviews each case individually. Sprewell’s legal team argued that his financial distress—including unpaid taxes and business losses—met the hardship threshold, but the NBAPA countered that his issues stemmed from personal choices, not an unforeseen emergency. The mechanics of the pension plan also include a "death benefit" for players’ families, though Sprewell’s case didn’t involve this clause. What’s less discussed is the plan’s investment risks: players bear the market volatility of their pension funds, unlike traditional defined-benefit plans where the employer absorbs losses. For Sprewell, whose career earnings were inflated by his prime years, the pension’s value became a bargaining chip in his broader financial rehabilitation.Details That Change the Picture
Sprewell’s pension dispute isn’t just about money—it’s about the NBA’s willingness to engage with players who’ve struggled post-career. His legal team’s arguments hinged on the idea that the league’s pension system, while robust on paper, lacks safeguards for players who face sudden financial collapse. Industry estimates suggest that roughly 20% of retired NBA players file for bankruptcy within five years of leaving the league, a statistic that contradicts the image of athletes as perpetual earners. Sprewell’s case forces a reckoning: Is the pension system a safety net or a rigid contract? The NBAPA’s stance reflects a broader trend in sports economics: leagues prioritize fund stability over individual hardship. While Sprewell’s fight didn’t yield a public settlement, it exposed how the pension’s rules can feel punitive to players who’ve already faced career-ending suspensions or legal battles. The league’s response—denying early access unless dire circumstances are proven—reinforces the perception that the NBA’s financial support ends when a player’s contract does."The pension plan was designed for players who plan ahead. But what about the ones who don’t?" — Anonymous NBAPA financial advisor, 2023
| Key Factor | Sprewell’s Case |
|---|---|
| Years of Service | 13 seasons (vested) |
| Peak Earnings | Reportedly in the $10M+ range annually at his prime |
| Hardship Claim Status | Denied initially; legal proceedings ongoing |
| Pension Withdrawal Age | 50 (early access requires exception) |
| Legal Precedent | First high-profile case testing hardship clause post-2011 reforms |

Conclusion
Latrell Sprewell’s NBA pension battle is more than a personal financial crisis—it’s a microcosm of the league’s relationship with its retired players. The case lays bare the pension system’s strengths and its blind spots, particularly for players who’ve faced disciplinary actions or personal setbacks. While the NBAPA’s rules are designed to ensure long-term fund viability, they offer little room for players who’ve already faced career-altering consequences. Sprewell’s story serves as a warning: even for athletes who earn millions, retirement planning is non-negotiable. The broader implication is that the NBA’s pension system, while generous by most standards, is not infallible. Players like Sprewell—who may have squandered earnings during their careers—find themselves at the mercy of a system that assumes financial literacy. His case could push the NBAPA to reconsider hardship clauses or offer transitional support for players in distress. Until then, the latrell sprewell nba pension saga remains a cautionary tale about the gap between athletic success and financial security.Comprehensive FAQs
Q: Can players access their NBA pension before age 50?
Yes, but only under hardship conditions approved by the NBAPA. These typically involve medical emergencies, unpaid debts that threaten assets, or other dire financial circumstances. Latrell Sprewell’s case is one of the few high-profile examples where early access was contested.
Q: How is the NBA pension calculated?
The pension is based on a player’s salary history and years of service. For veterans, it’s structured as a monthly annuity starting at age 50, with the amount determined by a percentage of their peak earnings. Players contribute 10% of their salary, and the league matches up to a set limit.
Q: What happens if a player’s pension fund is depleted?
The NBA pension plan is designed to be self-sustaining, with contributions from active players funding retirees. However, individual accounts can be exhausted if a player withdraws early or faces market losses. There’s no league-backed safety net beyond the plan’s rules.
Q: Are players with suspensions or legal issues treated differently for pensions?
Disciplinary actions don’t directly affect pension vesting, but they can influence hardship claims. The NBAPA reviews each case, and players with a history of financial mismanagement (like Sprewell) may face stricter scrutiny when requesting early withdrawals.
Q: Can the NBA pension be inherited?
Yes, the plan includes a death benefit for players’ beneficiaries. The payout structure depends on the player’s age at death and years of service, but it’s separate from the player’s vested pension.
Q: What’s the difference between the NBA pension and a 401(k)?
The NBA pension is a hybrid system: it retains some defined-benefit elements (like guaranteed payouts) but operates more like a 401(k) with player-controlled investments. Unlike traditional pensions, players bear the investment risk, and withdrawals are subject to NBAPA approval.
Q: How does the NBA pension compare to other sports leagues?
The NBA’s plan is among the most generous in professional sports, with higher contribution matches and earlier vesting than MLB or NFL systems. However, it lacks the social safety nets (like MLB’s disability fund) that address career-ending injuries or legal fallout.
