
Where It All Began
James Dewey Watson was born in 1928 in Chicago, the son of a business executive and a mother who encouraged his curiosity. By his early teens, he was dissecting squirrels in his backyard, a habit that would define his path. But it wasn’t just the thrill of discovery that drove him—it was the opportunity to be seen. Watson’s early ambition wasn’t just intellectual; it was performative. He knew, even then, that science was a stage, and he wanted to be the star. His financial foundation was modest: a middle-class upbringing that instilled discipline but didn’t provide safety nets. The Nobel Prize wouldn’t arrive until he was 25, but the seeds of his wealth-building strategy were sown much earlier—through relentless networking, strategic mentorship, and an uncanny ability to position himself at the right institutions at the right time. Watson’s breakthrough with Crick in 1953 didn’t just solve a scientific puzzle; it created one. The race to understand DNA had been a high-stakes game, and Watson’s role in it was both celebrated and scrutinized. While Wilkins and Crick shared the Nobel with him, the financial fallout of the discovery was uneven. Watson, ever the opportunist, leveraged his newfound status to secure a position at Harvard, where he could shape the next generation of geneticists. But it was his move to Cold Spring Harbor in 1968 that would redefine his financial trajectory. The laboratory, though prestigious, was financially fragile. Watson’s decision to take the helm wasn’t just about leadership—it was about control. He recognized that institutions, not just individuals, could become vehicles for wealth accumulation.The Early Signs
The 1970s were a decade of quiet accumulation for Watson. His net worth wasn’t yet a public topic, but the signs were there: speaking engagements at $5,000 a pop, textbook royalties from The Molecular Biology of the Gene, and the slow but steady growth of Cold Spring Harbor’s endowment under his direction. Watson was building two things simultaneously—a scientific empire and a personal brand. The laboratory became his playground, where he could test ideas, mentor protégés, and, crucially, monetize access. By the time he stepped down as director in 1994, Cold Spring Harbor was no longer just a research hub; it was a powerhouse with ties to pharmaceutical giants and biotech startups. His financial influence was less about personal fortune and more about shaping the ecosystem that would later enrich others—and, by extension, himself. What’s often overlooked is how Watson’s wealth strategy aligned with his scientific one: he bet on longevity. While other scientists chased short-term grants, Watson invested in infrastructure—buildings, equipment, and the intellectual property that would pay dividends for decades. His decision to focus on cancer research in the 1980s wasn’t just altruistic; it was a calculated move. Cancer was the ultimate "big science" problem, one that would attract sustained funding from governments and corporations alike. As Cold Spring Harbor’s influence grew, so did Watson’s ability to leverage that influence for personal gain—through consulting gigs, board seats, and the occasional high-profile lecture where his name alone guaranteed attendance.The Turning Point
The year 2007 marked the moment when James Watson’s net worth became inseparable from his reputation. It wasn’t a financial crisis—it was a cultural one. In an interview with The Sunday Times, Watson suggested that intelligence was hereditary and that certain ethnic groups were genetically predisposed to lower IQs. The backlash was immediate and brutal. Universities revoked his honorary degrees, Cold Spring Harbor distanced itself, and his speaking invitations dried up overnight. The financial impact was less about lost earnings and more about lost opportunity. Watson, who had spent decades cultivating his image as a fearless truth-teller, found himself pariah material. The controversy didn’t just damage his standing; it forced a reckoning. Watson’s wealth protection strategy shifted from growth to preservation. The Cold Spring Harbor Laboratory, which he had spent years building into a financial asset, became a liability. Donors pulled funding, and the institution’s stock—both literal and figurative—plummeted. Watson’s response was telling: he doubled down on his scientific work, publishing papers on aging and longevity, while quietly restructuring his personal finances. The lesson was clear: in the 21st century, a scientist’s net worth wasn’t just about discoveries—it was about how those discoveries were perceived."I have said some things that were not well thought out. But I have never said anything that contradicts the data." —James Watson, 2007The quote captures the essence of Watson’s dilemma. His entire career had been built on the premise that raw intelligence justified bold statements. But in an era where words were dissected for their social implications, his financial resilience depended on something new: discretion. The man who had once thrived on controversy now had to navigate a world where his net worth was as vulnerable as his reputation.

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1953–1968 |
Nobel Prize (1962) launches Watson’s profile, but financial gains are indirect—prestige opens doors to Harvard, speaking gigs, and textbook royalties. Cold Spring Harbor becomes his long-term project. |
| 1968–1994 |
As director of Cold Spring Harbor, Watson expands the lab’s endowment, secures corporate partnerships, and positions it as a biotech hub. His personal wealth grows through institutional ties, though exact figures remain private. |
| 1994–Present |
Post-directorship, Watson shifts focus to consulting, board roles (e.g., Biogen Idec), and high-profile research. The 2007 controversy forces a pivot—fewer public engagements, more behind-the-scenes influence. His net worth stabilizes but no longer grows at the same pace. |
Lessons From the Journey
- Prestige is a currency. Watson’s early financial leverage came from being the right person in the right place at the right time. The Nobel Prize wasn’t just an honor—it was a financial passport.
- Institutions are wealth multipliers. Cold Spring Harbor’s growth under his leadership wasn’t just about science; it was about creating an ecosystem where his influence translated into tangible assets.
- Reputation is an asset class. The 2007 backlash proved that in the modern era, a scientist’s net worth isn’t just about patents—it’s about social capital.
- Discretion becomes a survival tool. After the controversy, Watson’s wealth strategy shifted from expansion to protection—fewer risks, more controlled engagements.
- The long game matters. Watson’s bets on "big science" problems like cancer paid off decades later, proving that financial success in science often hinges on patience.
Where Things Stand Today
As of recent estimates, James Watson’s net worth is placed in the range of $10–20 million, though exact figures remain speculative. The majority of his wealth is tied to Cold Spring Harbor’s endowment, which he helped shape into a self-sustaining entity. His direct holdings—stocks, real estate, and consulting fees—are thought to contribute to the remainder. What’s clear is that his financial story is no longer about explosive growth. It’s about preservation. Watson, now in his 90s, has stepped back from the public eye, but his legacy continues to generate income through the lab’s research partnerships and his occasional appearances in scientific circles. The irony of Watson’s net worth today is that it’s as much a product of what he avoided as what he achieved. The 2007 controversy didn’t just cost him invitations—it forced him to rethink how he monetized his name. No longer could he rely on the shock value of his statements. Instead, his wealth maintenance strategy has become about steady, low-risk income streams: royalties from older works, occasional high-profile research collaborations, and the quiet influence of Cold Spring Harbor’s alumni network. The lab itself, now a global leader in cancer research, remains his most enduring financial legacy—a testament to the idea that sometimes, the greatest wealth isn’t what you accumulate, but what you build that outlives you.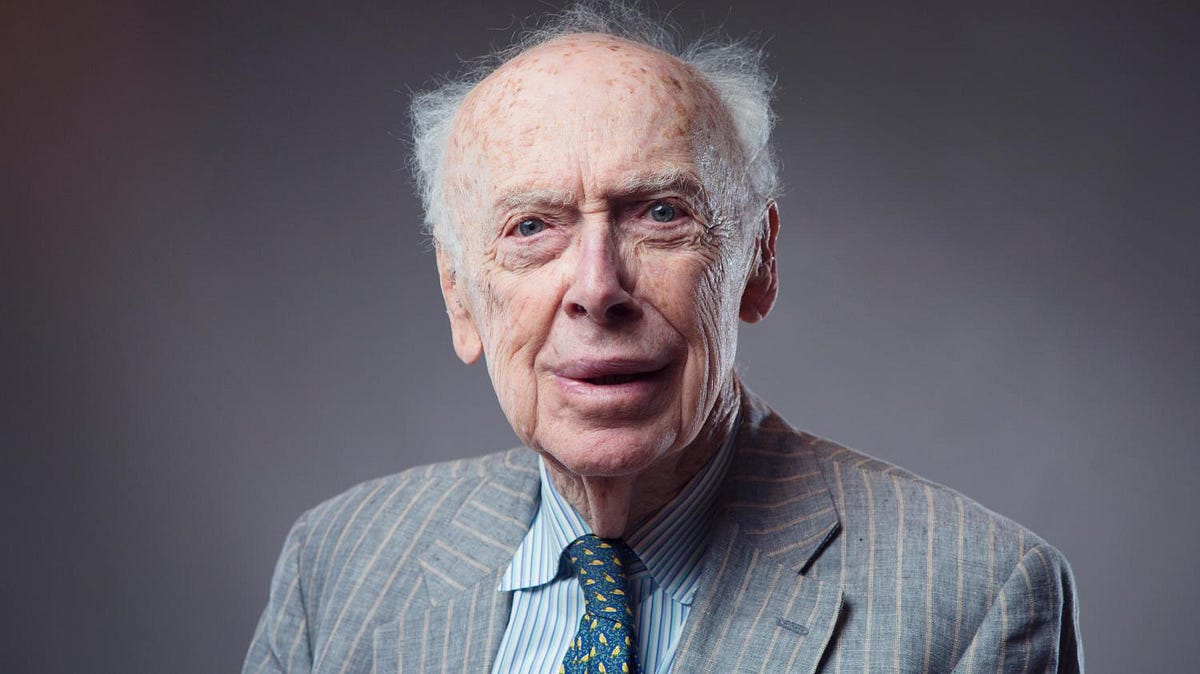
Conclusion
James Watson’s life is a study in contrasts. He was the scientist who unlocked the secrets of life, yet struggled to understand the consequences of his words. His net worth reflects that duality: a fortune built on genius, but also one that required constant recalibration in the face of public opinion. What’s fascinating isn’t just the size of his financial holdings, but how they evolved in response to external pressures. Watson’s story is a reminder that in the modern world, a person’s wealth—especially for a public figure—isn’t just about what they earn. It’s about what they’re allowed to keep. The lesson for scientists, entrepreneurs, and anyone who builds a career on influence is clear: wealth in the 21st century isn’t just about talent. It’s about timing, adaptability, and the ability to pivot when the world decides your old playbook no longer works. Watson’s financial journey isn’t just a footnote to his scientific achievements. It’s a case study in how reputation, institutions, and even controversy can shape a legacy—and a bank account.Comprehensive FAQs
Q: How did James Watson’s Nobel Prize directly impact his net worth?
The Nobel Prize itself didn’t come with a cash prize (the award was symbolic), but it indirectly boosted his financial trajectory by opening doors to high-paying academic positions, speaking engagements, and textbook royalties. The real impact was prestige-driven opportunity—his name became a brand, allowing him to command fees and secure institutional roles that would later translate into wealth.
Q: Did Cold Spring Harbor Laboratory’s growth under Watson directly increase his personal net worth?
While Watson’s personal wealth isn’t publicly detailed, his leadership at Cold Spring Harbor undoubtedly contributed to his financial standing. The lab’s expansion under his direction created consulting opportunities, board roles (e.g., Biogen Idec), and endowment ties that likely enriched him. However, his net worth is also tied to the lab’s long-term sustainability—his later decisions to restructure its finances post-controversy suggest a strategic focus on protecting, rather than growing, his personal assets.
Q: What was the financial fallout of Watson’s 2007 remarks on intelligence and ethnicity?
The immediate financial impact wasn’t a sudden loss of wealth, but a shift in earning potential. Universities revoked his honorary degrees, speaking invitations dried up, and corporate partnerships became riskier. While exact figures are unknown, his net worth growth likely stalled as high-profile income streams vanished. The controversy forced him to pivot to lower-risk ventures, such as behind-the-scenes research and institutional roles.
Q: Are there any verified public records of Watson’s financial disclosures?
No. Watson has never made detailed public disclosures about his net worth or assets. While Cold Spring Harbor’s financial reports exist, they don’t break down individual contributions. His wealth is estimated through industry analysis of his career milestones, institutional ties, and real estate holdings (e.g., property in the Hamptons). Unlike corporate leaders, scientists aren’t required to disclose personal finances.
Q: How does Watson’s wealth accumulation compare to other Nobel laureates in science?
Watson’s net worth is modest compared to some of his peers, such as Kary Mullis (estimated at $100M+ from patents) or Craig Venter (biotech entrepreneur with a reported $300M+ fortune). However, Watson’s wealth is more institutional—tied to Cold Spring Harbor’s endowment rather than direct patents or startups. His financial strategy prioritized long-term influence over short-term gains, making his net worth a product of institutional stewardship rather than personal entrepreneurship.
Q: Could Watson’s net worth decrease in the future?
It’s possible, though unlikely to be dramatic. His primary assets—Cold Spring Harbor’s endowment and real estate—are stable but not liquid. If the lab faces funding challenges or if his remaining properties lose value, his net worth could decline. However, given his age and reduced public profile, his financial focus appears to be on preservation, not further accumulation. Major declines would likely stem from external factors (e.g., institutional mismanagement) rather than personal spending.
Q: Has Watson ever discussed his financial philosophy in public?
Watson has rarely spoken about money in detail, but his actions reveal a pragmatic approach. Early in his career, he invested in prestige and networks; later, he prioritized stability and discretion. His decision to step back from public life post-controversy suggests a belief that financial security in his later years depends on controlling risks. Unlike entrepreneurs who flaunt wealth, Watson’s strategy has been about quiet accumulation—letting institutions do the heavy lifting.
