
Common Myths About How Net Worth Is Derived from Financial Statements
The first misconception is that net worth equals liquidity. Many assume if you can’t immediately convert assets to cash, they don’t count toward net worth. This ignores the fact that how is net worth calculated from balance sheet includes both current and non-current assets—like a primary residence or long-term investments—regardless of their liquidity. A homeowner’s equity in property is still part of net worth, even if selling it takes months. The second myth treats liabilities as monolithic. Student loans, mortgages, and credit card debt are all liabilities, but their impact on net worth varies wildly. A low-interest mortgage might barely dent net worth over decades, while a high-yield credit card balance could erode it quickly. The third error assumes balance sheets are static. They’re not. Net worth fluctuates with market conditions, revaluations, and even changes in accounting policies—yet many treat it as a fixed metric.
Another persistent myth is that net worth is the same as cash flow. A billionaire with a net worth of $10 billion might have negative cash flow if their business burns capital. The balance sheet captures a snapshot of wealth, not operational health. Similarly, people often conflate net worth with income. A high earner with massive debt could have a negative net worth, while a frugal retiree might have a healthy net worth despite modest income. The fourth myth is that public disclosures are foolproof. Even regulated filings—like those from publicly traded companies—can omit critical details. For instance, a company’s "net worth" might exclude contingent liabilities (like pending lawsuits) or off-balance-sheet financing (like operating leases). These omissions create a distorted picture of true financial health.
Myth 1: Net worth is just what’s listed on a personal balance sheet
The reality is that personal balance sheets often exclude critical assets or inflate liabilities through poor categorization. For example, a freelancer might omit unreported cash income or undervalue intellectual property (like patents or copyrights). On the liability side, some people treat all debt equally—ignoring that a $500,000 mortgage at 3% interest has a vastly different net worth impact than a $50,000 credit card balance at 20%. Even professional balance sheets can be gamed. Wealth managers sometimes reclassify assets to reduce taxable net worth, or they’ll use "soft" liabilities (like estimated future legal costs) to artificially deflate reported figures. The answer to how is net worth calculated from balance sheet thus depends on who’s preparing the statement—and what their incentives are.
Accounting standards provide guidelines, but they leave room for interpretation. For instance, the fair value principle requires assets to be recorded at market value, but determining "market value" for illiquid assets (like private company shares) is subjective. A startup founder might value their stake at $50 million based on a recent funding round, while an independent appraiser could argue it’s worth $20 million. These discrepancies mean net worth isn’t an objective number—it’s a negotiated one. The myth that personal balance sheets are neutral ledgers ignores the human element: bias, omission, and strategic presentation all shape the final figure.
Myth 2: Corporate net worth reflects true economic value
Public companies often report net worth figures that bear little resemblance to their actual economic value. This happens because balance sheets use historical cost accounting for many assets—meaning a building purchased for $1 million in 1990 might still appear on the books at that value, even if it’s now worth $5 million. Meanwhile, intangible assets like brand value or customer relationships—critical to companies like Apple or Coca-Cola—are rarely captured on the balance sheet. The result? A tech giant with a $2 trillion market cap might have a net worth on paper that’s a fraction of that, because most of its value lies in unrecorded intangibles.
The disconnect worsens with financial engineering. Companies use techniques like mark-to-market accounting for derivatives or off-balance-sheet entities to manipulate reported net worth. For example, a bank might move risky assets into a separate entity to keep its balance sheet "clean," making its net worth appear healthier than it is. Even when numbers are accurate, they can be misleading. A company with a high net worth might still be insolvent if its cash flow is negative or its liabilities are due in the short term. The answer to how net worth is calculated from balance sheet in corporate contexts is less about precision and more about strategic presentation—often to appease investors, regulators, or creditors.
Myth 3: Net worth is stable over time
Market volatility, economic cycles, and personal decisions can turn a balance sheet upside down in months. A real estate investor’s net worth might surge during a housing boom but collapse in a recession. Similarly, a tech employee’s net worth could balloon overnight with a stock option grant—only to vanish if the company’s valuation plummets. Even stable assets aren’t immune. A portfolio heavy in equities might see net worth swing by 20% in a single quarter, while fixed-income assets offer more stability but lower growth. The myth that net worth is a steady metric ignores the fact that how is net worth calculated from balance sheet is a dynamic process, not a static one.
Accounting policies also introduce instability. For instance, companies that use accrual accounting recognize revenue when earned, not when cash is received—meaning net worth can fluctuate based on timing rather than actual performance. Personal balance sheets face similar issues. A freelancer’s net worth might spike at year-end when they recognize deferred income, only to drop when they pay taxes. The illusion of stability comes from treating net worth as a single data point, when in reality, it’s a moving target influenced by external forces, accounting choices, and behavioral decisions.
What Holds Up to Scrutiny
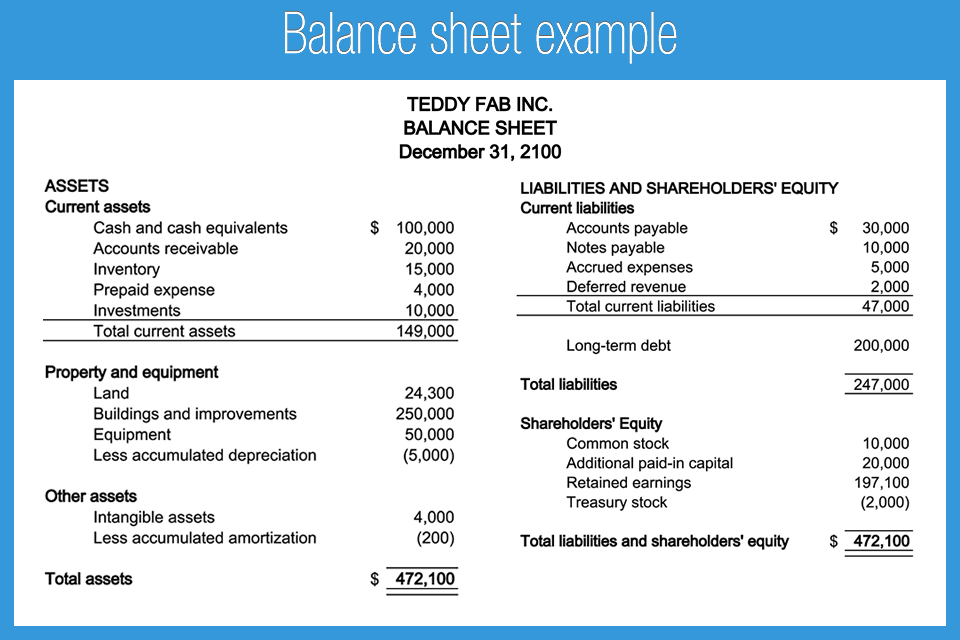
At its core, net worth is the residual claim on assets after liabilities—simple in theory, complex in practice. The most reliable balance sheets adhere to Generally Accepted Accounting Principles (GAAP) or International Financial Reporting Standards (IFRS), which require consistency in valuation, disclosure, and classification. For individuals, a well-maintained personal balance sheet should include:
- All assets: Cash, investments, real estate, personal property, and even digital assets (like cryptocurrency).
- All liabilities: Debt, taxes owed, and contingent obligations (like co-signed loans).
- Fair market valuations: Assets should be recorded at what they’d realistically sell for, not what they cost or what someone hopes they’re worth.
The key is transparency. A balance sheet that omits assets or understates liabilities is useless. For example, a high-net-worth individual might exclude a trust fund from their personal balance sheet, but if that trust is accessible, it should be included. Similarly, a company’s net worth is more credible when it discloses off-balance-sheet risks, like guarantees or commitments.
> "Net worth is a snapshot, but the real story is in the details—how assets were valued, what liabilities were acknowledged, and whether the numbers reflect reality or wishful thinking."
> — A certified public accountant specializing in wealth analysis
| Common Belief | What the Evidence Says |
|---------------------------------------|---------------------------------------------------------------------------------------------|
| Net worth = liquid assets only | Includes illiquid assets (e.g., property, private equity) if they have market value. |
| Liabilities are all equal | Some (like mortgages) have lower opportunity cost than high-interest debt. |
| Public disclosures are accurate | Often exclude intangibles, contingent liabilities, or use aggressive valuation methods. |
| Net worth is stable | Fluctuates with market conditions, revaluations, and accounting changes. |
| Personal balance sheets are optional | Critical for tax planning, loan applications, and estate management. |
Why the Confusion Persists
The gap between theory and practice stems from three factors. First, accounting is a mix of science and art. While GAAP and IFRS provide frameworks, they allow flexibility in areas like impairment testing or fair value estimation. Second, incentives distort reporting. A company might understate liabilities to attract investors, while an individual might inflate assets to secure a loan. Third, complexity obscures clarity. Terms like "goodwill," "deferred tax assets," and "non-recourse debt" are familiar to accountants but baffling to laypeople—leading to misinterpretations of net worth.
The media doesn’t help. Headlines about "billionaire net worth" often rely on speculative valuations (e.g., private company stakes) or ignore liabilities entirely. Even financial advisors sometimes oversimplify, telling clients to focus on net worth without explaining how it’s derived—or how it can be manipulated. The result? A system where how is net worth calculated from balance sheet is understood by few, yet scrutinized by many.

Conclusion
Understanding how net worth is calculated from balance sheet requires more than memorizing the assets-minus-liabilities formula. It demands a grasp of valuation methods, accounting treatments, and the strategic choices that shape financial statements. For individuals, this means tracking assets and liabilities with precision, while for corporations, it involves navigating complex reporting standards and investor expectations. The takeaway? Net worth is neither fixed nor foolproof—it’s a reflection of financial reality, filtered through human judgment and institutional rules.
The next time you see a net worth figure, ask: How was this calculated? Was it a straightforward subtraction, or did it involve estimates, omissions, or creative accounting? The answer will tell you far more about the context than the number itself.
Comprehensive FAQs
#### Q: Can I calculate my net worth without a formal balance sheet?
A: Yes, but it requires discipline. List every asset (cash, investments, property, etc.) at its current market value, then subtract all liabilities (debt, taxes, etc.). Tools like spreadsheets or apps (e.g., Mint, YNAB) can automate this. The challenge lies in accurately valuing illiquid assets—like a family heirloom or a private business stake—where market data is scarce.
####Q: Do off-balance-sheet items affect net worth?
A: Indirectly. Off-balance-sheet items (like operating leases or guarantees) don’t appear as liabilities but can impact financial health. For example, a lease obligation might not show up on a balance sheet, but it still represents a future cash outflow. True net worth should account for these "hidden" obligations, even if they’re not formally recorded.
####Q: How often should I update my net worth calculation?
A: At least annually, but more frequently if you have volatile assets (e.g., stocks, crypto). Market fluctuations, debt repayments, or new purchases can shift net worth significantly. Quarterly updates are ideal for high-net-worth individuals or those with complex financial portfolios.
####Q: Why does a company’s net worth differ from its market capitalization?
A: Market cap reflects what investors think the company is worth (based on stock price), while net worth is a book value (assets minus liabilities). The gap arises because market cap includes intangibles (like brand value) and growth potential, while net worth often excludes them. For example, a tech startup might have a net worth of $50 million but a $2 billion market cap if investors bet on future revenue.
####Q: Should I include pending lawsuits as liabilities?
A: Yes, if there’s a reasonable chance of a negative outcome. Contingent liabilities (like lawsuits or guarantees) should be disclosed in footnotes or, if probable, recorded as liabilities. Ignoring them understates true net worth and risks financial surprises. Consult an accountant to assess the likelihood and potential impact.
####Q: Can negative net worth be a good thing?
A: In some cases. A young professional with student loans and a modest home might have negative net worth, but if their income is growing and assets (like a career) are appreciating, it could be a strategic position. However, negative net worth is problematic if liabilities outweigh assets and there’s no clear path to recovery—like a business with unsustainable debt.
####Q: How do cryptocurrencies affect net worth calculations?
A: They should be included at their current market value, but the method matters. Some accountants use FIFO (first-in, first-out) for cost basis, while others mark to market daily. Volatility means net worth can swing wildly—what’s a $1 million portfolio one day might be $500,000 the next. For tax purposes, consult a CPA to ensure compliance with IRS rules on crypto reporting.
