
The Complete Overview of IRS Household Net Worth Data
The IRS’s approach to tracking household net worth is indirect but meticulous. Unlike a census that asks families to disclose every dollar, the agency infers wealth through tax returns, which report income, capital gains, property values, and deductions. High-value assets—stocks, real estate, collectibles—leave fingerprints in the form of unrealized gains, depreciation claims, or charitable contributions. The IRS doesn’t publish aggregate net worth figures by zip code or occupation, but it does release statistical estimates through the Statistics of Income division and partnerships with the Federal Reserve. These estimates, while not granular, are the gold standard for economists and policymakers. The data’s power lies in its unintended revelations. For example, the surge in passive income reported in recent tax filings suggests a shift toward asset-based wealth, while declining itemized deductions hint at middle-class financial strain. The IRS also cross-references data with other agencies—like the Social Security Administration—to detect anomalies, such as a retiree suddenly reporting $5 million in rental income. This isn’t just about catching tax evaders; it’s about calibrating a system where the rules themselves shape behavior. When a policy change (like the 2017 Tax Cuts and Jobs Act) alters how wealth is reported, the IRS’s data adapts, creating feedback loops that ripple through the economy.Historical Background and Evolution
The IRS’s modern wealth-tracking capabilities trace back to the 1913 Revenue Act, which introduced federal income taxes. Early filings were rudimentary—mostly wage earners and small business owners—but as the economy grew, so did the complexity of reporting. The post-WWII era saw the rise of capital gains taxes, forcing the IRS to develop methods for valuing appreciated assets. By the 1980s, computerization allowed the agency to flag inconsistencies, such as a taxpayer claiming a $2 million loss on a yacht while reporting a $50,000 salary. These early systems laid the groundwork for today’s data-driven enforcement. The 21st century brought two seismic shifts: the digitalization of filings and the globalization of wealth. The IRS’s Large Business and International division now scrutinizes offshore accounts through programs like FATCA (Foreign Account Tax Compliance Act), while the Taxpayer Advocate Service uses net worth analysis to resolve disputes. The pandemic accelerated these trends, as remote work and crypto investments created new reporting challenges. Today, the IRS’s data isn’t just reactive—it’s predictive, using machine learning to identify patterns before they become widespread. The agency’s ability to connect dots across decades of filings makes its household net worth insights uniquely valuable.Core Mechanisms: How It Works
At its core, IRS household net worth data is a byproduct of tax compliance. When a filer reports a $1.2 million primary residence, the IRS doesn’t verify the market value on the spot—but it does cross-check with county assessor records if discrepancies arise. Similarly, stock portfolios are tracked via brokerage statements, though the IRS doesn’t demand daily snapshots. The agency’s statistical sampling methods, however, provide broader insights. For instance, if 3% of filers in a demographic report losses on rental properties, the IRS can estimate industry-wide trends without examining every return. The real magic happens in the back office. The IRS’s Compliance Data Warehouse integrates filings with third-party data, such as mortgage records or luxury vehicle purchases, to build a holistic picture. This isn’t just about catching errors—it’s about understanding how wealth flows. A sudden drop in reported business income in a sector might signal economic trouble, while a rise in charitable deductions could indicate tax planning strategies. The data also helps the IRS set audit triggers: a filer with a net worth 50% higher than their reported income is far more likely to be flagged than one with consistent, modest assets.Key Benefits and Crucial Impact
IRS household net worth data isn’t just a tool for the taxman—it’s a barometer for the economy. When the Federal Reserve adjusts interest rates, it relies on IRS-derived wealth estimates to gauge consumer spending power. Policymakers use the data to design incentives, like the Child Tax Credit expansions, which target households based on income and asset thresholds. Even philanthropists leverage these insights to direct donations to regions where net worth growth lags. The data’s reach extends beyond government: financial advisors use IRS trends to counsel clients on asset protection, while real estate investors track property value inflation in high-net-worth areas. The most underrated impact? Behavioral economics. When taxpayers see peers in similar brackets taking advantage of deductions, they adjust their own strategies. The IRS’s data creates a silent market for compliance—where the fear of being an outlier drives decisions. This isn’t just about avoiding penalties; it’s about shaping how people think about wealth. For example, the rise of donor-advised funds correlates with IRS data showing that charitable contributions often trigger lower taxable income. The system doesn’t just reflect reality—it molds it."The IRS’s wealth data isn’t just numbers—it’s a real-time referendum on economic fairness. When you see a filer reporting $10 million in assets but claiming the Earned Income Tax Credit, you’re not just seeing a tax issue. You’re seeing a policy failure." — Jane Gravelle, Senior Specialist in Economic Policy (Congressional Research Service)
Major Advantages
- Policy precision: IRS data allows targeted legislation, such as capping deductions for high earners while preserving breaks for middle-class families.
- Economic forecasting: Fluctuations in reported business assets help predict recessions or booms before traditional indicators.
- Fraud detection: Cross-referencing filings with external records (e.g., luxury purchases) reduces evasion without invasive audits.
- Public transparency: While raw data is confidential, aggregated trends (e.g., wealth concentration by age group) inform debates on inequality.
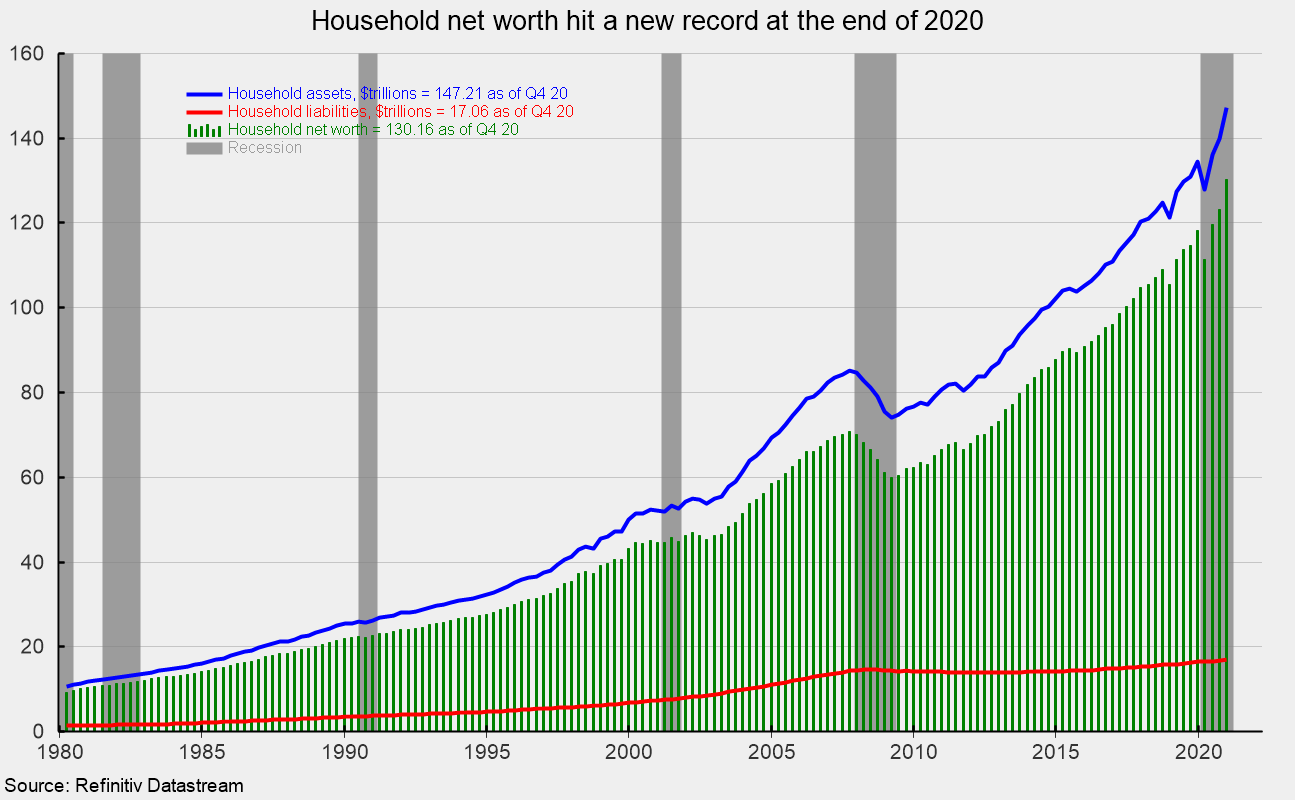
Comparative Analysis
| IRS Household Net Worth Data | Federal Reserve SCF Data |
|---|---|
| Derived from tax filings; focuses on reported assets/liabilities. | Surveys households directly; includes non-taxable wealth (e.g., Social Security). |
| Updated annually with tax cycles; reacts to legislative changes. | Triennial surveys; slower but broader (e.g., pension values). |
| Used for enforcement and policy; confidential by design. | Publicly released; used for academic and media analysis. |
| Strength: High compliance rate; covers all filers. | Strength: Captures non-financial wealth (e.g., home equity). |
Future Trends and Innovations
The next frontier for IRS household net worth data lies in artificial intelligence. Current systems flag anomalies by comparing filings to historical averages, but AI could predict evasion patterns before they occur. For example, if a filer’s reported income drops 30% but their spending on private jets rises, an algorithm might intervene before an audit. Privacy concerns will limit this, but the IRS is already testing synthetic data—artificially generated filings to train models without exposing real taxpayers. Another shift is the integration of decentralized finance (DeFi). Crypto transactions leave trails the IRS can’t ignore, and platforms like Coinbase now report user data directly. As digital assets grow, the IRS’s net worth estimates will need to account for volatile markets where a $10,000 investment could be worth $100,000 or $0 in months. The challenge? Ensuring these systems don’t become tools for overreach. The balance between transparency and privacy will define the next decade of IRS data use.
Conclusion
IRS household net worth data is more than a ledger—it’s a lens into the American economy’s pulse. From the way homeownership rates influence mortgage policies to how offshore accounts reshape tax treaties, the insights derived from these filings trickle into every financial decision. The data’s true value isn’t in its precision but in its unintended consequences: how it nudges behavior, exposes gaps in legislation, and forces hard conversations about fairness. For individuals, the takeaway is simpler: tax planning isn’t just about minimizing liabilities. It’s about understanding how your filings fit into a larger narrative. A sudden windfall in reported assets might trigger an audit, while a strategic shift in deductions could align you with peers in your bracket. The IRS’s data isn’t just watching—it’s shaping the rules of the game. Those who play by its logic gain more than just compliance; they gain a strategic edge.Comprehensive FAQs
Q: Can I see my neighbor’s net worth from IRS data?
A: No. IRS data is confidential by law, and even aggregated statistics (like zip-code-level estimates) don’t reveal individual figures. The closest public data comes from the Federal Reserve’s Survey of Consumer Finances, which samples households but doesn’t identify them.
Q: How does the IRS estimate net worth if not all assets are reported?
A: The IRS uses statistical sampling and third-party data (e.g., county property records, brokerage statements) to infer unreported wealth. For example, if a filer claims a $300,000 home but local sales suggest $800,000 values, discrepancies may trigger an audit.
Q: Does reporting high net worth increase my audit risk?
A: Yes. The IRS’s Discriminant Function System scores returns based on income-to-net-worth ratios, business deductions, and other red flags. A filer with a net worth 2–3 times their reported income is far more likely to be audited than one with modest assets.
Q: How accurate are IRS wealth estimates compared to other sources?
A: IRS data is highly accurate for taxable assets (stocks, real estate, business income) but underrepresents non-taxable wealth (e.g., retirement accounts, inheritances). The Federal Reserve’s SCF is broader but less frequent, while credit bureau data (like Equifax) captures debt but not liquid assets.
Q: Can the IRS seize assets if net worth data shows unreported income?
A: Yes. Under 26 U.S. Code § 6331, the IRS can levy bank accounts, property, or wages if it determines taxes were underreported. However, seizures require due process, and many cases are resolved through payment plans or penalties.
Q: How do IRS wealth trends affect mortgage lending?
A: Lenders use IRS-derived net worth data to assess risk. For example, if IRS filings show a rise in adjustable-rate mortgages among high-net-worth borrowers, banks may tighten underwriting standards. The data also influences loan-to-value ratios for luxury properties.
Q: Are there loopholes to protect net worth from IRS scrutiny?
A: Legitimate strategies include trusts, charitable giving, and asset location (e.g., holding investments in low-tax states). However, aggressive tactics—like transferring assets to family members—can trigger gift tax or fraud penalties. Consulting a tax attorney is critical.
Q: How does IRS net worth data influence state tax policies?
A: States like California and New York use IRS data to model progressive tax brackets and wealth taxes. For example, if IRS filings show a surge in ultra-high-net-worth residents, states may introduce additional tax tiers or cap deductions.
