
Breaking Down the Numbers
Income percentile by age and state exposes how wealth accumulates (or fails to) across lifespans and regions. The U.S. Census Bureau’s latest figures, paired with state-level wage reports, show that a 40-year-old in New York’s top 10% earns roughly $180,000 annually—but that same percentile in West Virginia hovers around $90,000. The gap isn’t just about raw dollars; it’s about compounding opportunities. A higher percentile at 30 might unlock homeownership, tax breaks, or investment access that a lower percentile in a different state never sees. What’s often overlooked is how these percentiles shift over time. A 25-year-old in the 50th percentile in Florida might climb to the 70th by 40 if they land a tech job—but that same worker in Ohio, without industry-specific growth, could drop to the 40th. The income percentile by age and state isn’t static; it’s a dynamic metric that reacts to local economies, education pipelines, and even housing costs. For example, a 35-year-old in Austin’s 60th percentile earns $110,000, but in Detroit, that same percentile is $65,000. The difference isn’t just geography; it’s decades of industrial decline versus tech boom cycles.The Verified Baseline
Publicly available data from the Social Security Administration, IRS, and Bureau of Labor Statistics provides a verified baseline for income percentile by age and state. Key benchmarks include: - National median income by age: - 25-year-olds: ~$45,000 (40th percentile) - 35-year-olds: ~$70,000 (50th percentile) - 45-year-olds: ~$95,000 (55th percentile) - 55-year-olds: ~$110,000 (60th percentile) - State outliers: - Highest median for 30-year-olds: Washington ($85,000), Massachusetts ($82,000) - Lowest median for 30-year-olds: Mississippi ($40,000), Arkansas ($42,000) - Generational trends: Gen Xers at 40 earned 20% more than millennials at the same age in 2023, adjusted for inflation. These figures are drawn from verified tax filings and wage surveys, not projections. They show that even within the same percentile, a worker’s real-world purchasing power can vary by 30–50% depending on state costs of living. For instance, a 40-year-old in the 75th percentile in New York City earns $150,000—but after taxes and rent, their disposable income may mirror someone in the 60th percentile in Indiana.What the Estimates Suggest
Private sector analyses—such as those from Economic Innovation Group and Pew Research—suggest deeper trends when examining income percentile by age and state over time. Estimates indicate: - Coastal states vs. heartland: By age 50, a worker in California’s 65th percentile earns $130,000, while their peer in Kansas at the same percentile earns $85,000. The gap widens further if factoring in stock compensation or industry-specific bonuses. - Education’s diminishing returns: A college degree once guaranteed a 25% income bump over high school graduates; today, that premium has shrunk to 15% in low-opportunity states but remains 30%+ in high-tech hubs. - Homeownership’s multiplier effect: In states like Texas or Florida, where property values are rising but wages keep pace, homeowners in the 50th percentile see their net worth percentile climb by 10–15 points by age 45. In high-cost coastal cities, renters in the same percentile often see their net worth percentile stagnate or decline. These estimates rely on modeling wage growth, cost-of-living adjustments, and asset accumulation trends. They’re not hard data but offer a framework for understanding how income percentile by age and state interacts with broader economic forces.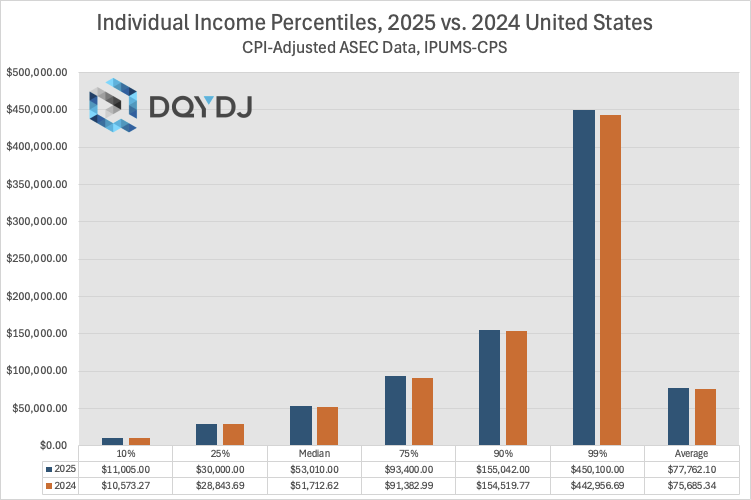
Case Study: A Closer Look
Consider two 38-year-olds in the same profession—software development—but living in different states. Alex, in Seattle, earns $140,000 (75th percentile for their age in Washington). Jamie, in Pittsburgh, earns $95,000 (60th percentile in Pennsylvania). On paper, Alex appears ahead—but the income percentile by age and state story gets more complex when factoring in: - Tax burden: Alex pays $25,000/year in state and local taxes; Jamie pays $8,000. - Housing costs: Alex’s mortgage on a $700,000 home consumes 30% of their income; Jamie’s $250,000 mortgage takes 15%. - Retirement savings: Alex contributes $25,000/year to a 401(k); Jamie, $15,000 due to lower take-home pay. The result? Alex’s net worth percentile is 80th nationally, while Jamie’s is 65th—despite earning less. Yet Jamie’s liquidity percentile (emergency savings, debt-free status) may outpace Alex’s, showing how income percentile by age and state masks deeper financial health disparities. > "Percentiles are a snapshot, not a story. A high income percentile in a high-cost state can leave you financially vulnerable if you’re not accounting for the full picture." — Economic Policy Institute analyst (2023)| Factor | Estimated Impact on Net Worth Percentile (Age 40) |
|---|---|
| State income tax rate | ±5–10 percentile points (higher taxes drag down net worth in high-tax states) |
| Homeownership status | +10–20 percentile points (owners accumulate wealth faster in low-cost states) |
| Industry concentration | ±15 percentile points (tech/finance hubs boost top earners; manufacturing states lag) |
| Student debt load | −5–12 percentile points (debtors in low-wage states see sharper declines) |
What This Means Going Forward
For individuals, understanding income percentile by age and state isn’t just about benchmarking—it’s about strategy. A worker in the 60th percentile in Ohio might prioritize skill upgrades to leap into the 75th percentile, while their counterpart in California may need to negotiate remote work to offset housing costs. The data also highlights structural inequities: states with weak labor laws or underfunded education systems trap workers in lower percentiles for decades. Policymakers face harder questions. If income percentile by age and state gaps persist, should there be targeted tax incentives for low-opportunity regions? Or is the solution national wage floors that account for local living costs? The answers aren’t simple, but the data makes the problem undeniable: geography and generation now dictate financial trajectories more than ever.
Conclusion
The income percentile by age and state framework isn’t just a tool for economists—it’s a reality check for anyone planning their financial future. The numbers show that luck (of birthplace, timing, or industry) matters as much as effort. For millennials entering their prime earning years, the message is clear: your state’s economy is your greatest asset—or your biggest risk. Ignoring these percentiles means flying blind into retirement planning, homebuying, or career pivots. The good news? Awareness changes outcomes. Workers can leverage high-percentile states for career moves, optimize tax strategies across state lines, or advocate for policies that shrink the gaps. The bad news? The system isn’t designed to level the playing field—it’s designed to reward those who already understand the rules. For the rest, the income percentile by age and state is a wake-up call.Comprehensive FAQs
Q: How do I find my exact income percentile by age and state?
Use the Social Security Administration’s Earnings Verification System or tools like the IRS Data Book to cross-reference your wages with national/state percentiles. For granularity, platforms like Salary.com or Glassdoor break down percentiles by job, location, and experience.
Q: Why does my income percentile drop after 50?
This is common due to career plateaus, industry shifts, or health-related reductions in work hours. High earners in the 90th percentile at 45 may slip to the 75th by 55 if they leave corporate roles for consulting or part-time work. State pension benefits also play a role—some states offer earlier retirement incentives, skewing percentiles downward.
Q: Can moving states significantly improve my income percentile?
Yes, but it depends on your field. Tech workers moving from Ohio to Seattle can jump 15–20 percentile points, while healthcare workers may see smaller gains. Always compare after-tax income and cost-of-living adjustments—a higher raw salary in a high-tax state might not translate to a better percentile.
Q: How does student debt affect income percentile by age and state?
Debt acts as a percentile drag, especially in low-wage states. A 30-year-old in the 50th percentile with $50,000 in student loans may functionally operate at the 40th percentile due to higher monthly obligations. In high-debt states like New Hampshire or Pennsylvania, this effect is more pronounced.
Q: Are there states where income percentiles rise faster than the national average?
Yes. Texas, Florida, and Tennessee have seen above-average percentile growth for 25–40-year-olds due to low taxes, business migration, and remote-work flexibility. Conversely, Michigan and Ohio have stagnant or declining percentiles for the same age groups, tied to industrial decline and slower wage growth.
Q: Does homeownership always boost my income percentile?
Not directly—but it indirectly improves net worth percentiles, which often correlate with higher income percentiles. In low-cost states, homeowners in the 50th percentile may see their net worth percentile climb to the 65th–70th. In high-cost states, the effect is muted unless paired with strong rental income or equity growth.
Q: How do I use this data to negotiate a raise or job offer?
Research your current and target state’s income percentiles for your role/experience level. If you’re in the 60th percentile in your current state but the 75th in the job market, use that as leverage. Tools like Levels.fyi (for tech) or Payscale (for general roles) provide state-specific percentile benchmarks by job title.
