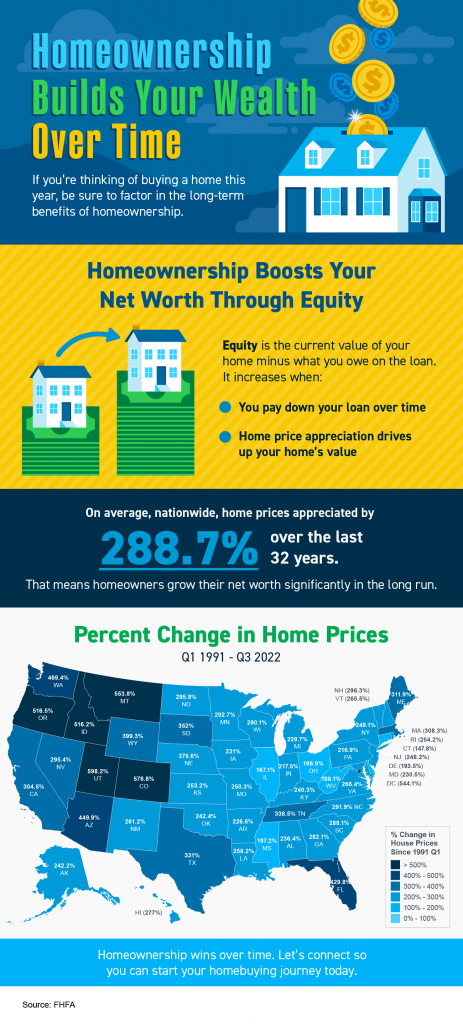
The Complete Overview of Home Ownership as Part of Net Worth
Home ownership as part of net worth operates on two parallel tracks: forced appreciation and tax-advantaged growth. The first is mechanical—every mortgage payment reduces debt while the property’s value (hopefully) rises. The second is structural—mortgage interest deductions, property tax exemptions, and capital gains exclusions (up to $500,000 for primary residences) create a de facto subsidy for homeowners. Yet these benefits are often overlooked because they’re buried in tax code rather than highlighted in personal finance literature. The real leverage comes when home ownership is integrated with other assets. For example, a homeowner with $300,000 in equity could tap into it via a HELOC to invest in stocks or a rental portfolio, effectively amplifying their net worth through compounding. This strategy—sometimes called "home equity recycling"—was popularized by economists like Karl Case and Robert Shiller, who noted that homeowners who reinvest proceeds from sales or refinancing outperform non-homeowners by 1.5x to 2x over 30 years. The catch? Timing, risk tolerance, and avoiding over-leveraging. What’s often missing from the conversation is the psychological dimension. Studies from the Urban Institute show that homeowners report higher financial confidence and lower stress levels than renters, even when their net worth is identical. The reason? Ownership creates a tangible sense of progress—a physical asset that builds equity month over month, unlike liquid investments that fluctuate on screens. This isn’t just emotional; it’s behavioral economics in action. People who feel wealthier tend to make better financial decisions, which further accelerates net worth growth.Historical Background and Evolution
The modern concept of home ownership as part of net worth traces back to post-WWII America, when the GI Bill (1944) explicitly tied homeownership to wealth accumulation. The program provided veterans with low-interest mortgages, effectively subsidizing equity growth for an entire generation. By the 1960s, homeownership rates had surged to 62%, and the link between real estate and generational wealth became entrenched. Policymakers reinforced this by making mortgage interest deductible (1913 Tax Act) and later introducing FHA loans (1934), which lowered barriers to entry. The 1980s marked a turning point. Deregulation and the rise of subprime lending expanded access to homeownership, but it also distorted the relationship between property values and net worth. The dot-com bubble and subsequent housing crash exposed the risks—homeowners who treated their homes as liquid assets (via cash-out refinancing) faced catastrophic losses when markets corrected. This era forced a reckoning: home ownership as part of net worth is not risk-free. It requires understanding that equity growth isn’t linear and that leverage can cut both ways. Today, the narrative is shifting again. The 2008 crisis led to stricter lending standards, but it also spurred a cultural reset in how millennials view homeownership. No longer is it seen as a default life milestone; it’s a calculated financial move. This generation is more likely to delay buying until they’ve built a cushion of liquid savings, recognizing that home ownership as part of net worth is most powerful when paired with emergency funds and diversified investments. The result? A more strategic approach to real estate as an asset class.Core Mechanisms: How It Works
At its core, home ownership as part of net worth functions through three interlocking mechanisms: equity accumulation, tax advantages, and forced savings. Equity grows in two ways—appreciation (market-driven) and amortization (mortgage paydown). For example, a $350,000 home with a $70,000 down payment and 4% annual appreciation gains $14,000 in value the first year. Meanwhile, the mortgage principal reduces by roughly $2,000 (assuming a 30-year loan at 6% interest). Combined, that’s $16,000 in net worth growth without any additional effort. Tax advantages further amplify this effect. The mortgage interest deduction alone can reduce taxable income by thousands annually, depending on the loan size and local rates. Property tax exemptions (e.g., the $250,000 capital gains exclusion for primary residences) mean that when homeowners sell, they avoid paying taxes on decades of appreciation. This isn’t just a windfall—it’s a built-in return on the investment. For high-income earners, these benefits can translate to hundreds of thousands in deferred taxes over a lifetime. The forced savings aspect is often the most underrated. Every mortgage payment is, in essence, a mandated investment into an appreciating asset. Renters, by contrast, have no such guarantee—their monthly payments vanish into a landlord’s pocket. This is why homeownership rates correlate strongly with long-term wealth disparities. According to the Brookings Institution, homeowners in the top 20% of wealth hold 90% of all residential equity, while the bottom 40% hold just 4%. The system isn’t neutral; it rewards those who participate in home ownership as part of net worth.Key Benefits and Crucial Impact
The primary appeal of home ownership as part of net worth lies in its dual role as both a hedge and a growth engine. During inflationary periods, real estate tends to outperform cash and bonds, acting as a natural inflation hedge. Meanwhile, in low-interest environments, mortgage rates lock in fixed payments, creating predictable cash flow. This duality is why homeowners historically recover faster from economic downturns—their asset appreciates while their liabilities remain stable. The data supports this. A 2022 study by the National Association of Realtors found that homeowners aged 65+ have a median net worth 40x higher than renters of the same age. The reason? Compound equity growth over 30+ years, combined with tax advantages and the ability to downsize or tap into equity in retirement. Even in stagnant markets, the forced savings aspect ensures that homeowners build wealth passively—something no other asset class offers with the same reliability. > "Homeownership isn’t just about owning a house; it’s about owning a piece of the future. The equity you build isn’t just an asset—it’s a foundation for everything else: education, retirement, legacy." — Robert Shiller, Nobel laureate and Yale economistMajor Advantages
- Forced equity growth: Every payment reduces debt while the property’s value (ideally) rises, creating automatic wealth accumulation.
- Tax deferral and exemptions: Mortgage interest deductions, capital gains exclusions, and property tax breaks reduce the effective cost of ownership.
- Leverage with collateral: Home equity can be accessed via HELOCs or refinancing to fund other investments, amplifying net worth.
- Inflation resistance: Real estate historically outperforms cash and bonds during inflation, protecting purchasing power.
- Legacy planning: Home equity can be passed to heirs tax-free (up to $11.7M per person under current estate tax laws).
- Psychological and behavioral benefits: Ownership fosters long-term financial discipline and confidence, leading to better investment decisions.
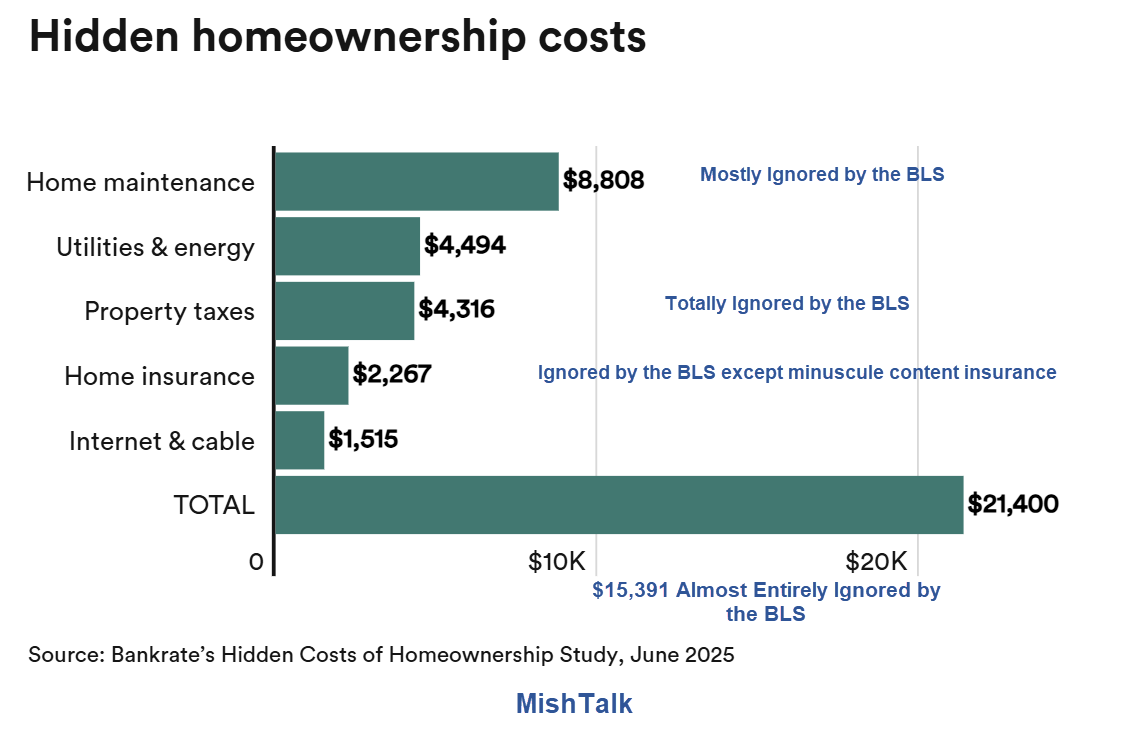
Comparative Analysis
| Home Ownership as Part of Net Worth | Renting + Investing Equivalent Portfolio |
|---|---|
| Equity grows via appreciation + amortization | Equity grows via market returns (volatility-dependent) |
| Tax advantages (deductions, exclusions) | Taxed on capital gains, dividends, interest |
| Forced savings via mortgage payments | Requires disciplined manual investing |
| Leverage via HELOCs/refinancing | Leverage via margin accounts (higher risk) |
Future Trends and Innovations
The next decade will likely see three major shifts in how home ownership functions as part of net worth. First, alternative financing models—such as shared equity agreements and rent-to-own programs—will make entry easier for younger buyers, though they may dilute long-term equity growth. Second, climate resilience will become a key differentiator; homes in flood zones or wildfire-prone areas may see depreciation risks, while sustainable properties could command premiums. Finally, digital asset integration—like blockchain-based property titles or tokenized real estate—could unlock new ways to fractionalize ownership, making home equity more liquid. The biggest wild card? Monetary policy. If central banks maintain high interest rates for extended periods, mortgage costs could suppress homeownership rates, particularly among millennials. This would force a reevaluation of whether home ownership as part of net worth remains viable for younger generations—or if they’ll need to adopt hybrid strategies (e.g., buying smaller homes earlier, renting with options to purchase later). One thing is certain: the relationship between real estate and net worth will continue evolving, driven by demographics, technology, and economic cycles.
Conclusion
Home ownership as part of net worth isn’t a relic of the past—it’s a dynamic financial tool that demands strategy, not just sentiment. The data is clear: those who treat their homes as integral to their wealth-building plan outperform those who view them as mere expenses. Yet the key lies in balance. Over-leveraging, ignoring market risks, or treating a home as a liquid asset can backfire. The sweet spot? Using home equity as collateral for growth, while maintaining liquidity and diversification. The future belongs to those who optimize home ownership—not just own it. That means leveraging tax advantages, timing refinances, and integrating real estate with other assets. It also means recognizing that home ownership as part of net worth is not one-size-fits-all. For some, it’s the cornerstone of wealth; for others, it’s a complementary piece. The critical question isn’t whether to own, but how to own—strategically, patiently, and with an eye on the long game.Comprehensive FAQs
Q: Does home ownership always increase net worth?
A: No. Net worth growth depends on appreciation exceeding debt service. In stagnant or declining markets, homeowners may see little equity gain, especially if they over-leveraged. The safest approach is to buy in areas with historical appreciation trends and maintain a buffer for downturns.
Q: Can renting ever be a better net worth strategy?
A: Yes, if you invest the difference between rent and a mortgage payment. Studies show that in high-cost cities (e.g., San Francisco, NYC), renting and investing the savings can sometimes outperform buying—but only if you achieve consistent market returns (7%+ annually). Most renters, however, fail to invest aggressively enough to match home equity growth.
Q: How does home ownership affect retirement planning?
A: Home equity can be a critical retirement asset. Options include downsizing (selling for cash), reverse mortgages (HECM), or tapping equity via HELOCs. The key is planning ahead—many retirees discover too late that their home is their largest asset but lack liquidity. Financial advisors recommend keeping 20-30% of home equity accessible for emergencies.
Q: Are there tax risks I should know about?
A: Yes. While primary residences enjoy capital gains exclusions, rental properties and second homes are taxed differently. Short-term rentals (e.g., Airbnb) may trigger ordinary income tax on profits. Additionally, if you sell a home and don’t meet the 2-year ownership rule, you could owe taxes on gains. Always consult a tax professional before selling or refinancing.
Q: How does home ownership compare to other assets (stocks, crypto, etc.)?
A: Real estate offers lower volatility than stocks but also lower liquidity. Crypto and stocks can yield higher returns but require active management. The best approach? Diversify. Home ownership as part of net worth should complement, not replace, other investments. A common rule: 30-50% of investable assets in real estate, with the rest in stocks, bonds, and cash.
Q: What’s the biggest mistake people make with home equity?
A: Treating it as an ATM. Cash-out refinancing or HELOCs can fund vacations, cars, or speculative investments—but if the market dips, you’re left with negative equity. The smarter move? Use home equity to debt-consolidate high-interest loans or fund low-risk income streams (e.g., rental properties). Always ask: Will this move preserve or grow my net worth?
Q: How can millennials optimize home ownership for net worth?
A: Start by buying early—even a modest home—and holding long-term. Prioritize low-cost areas with job growth. Use house hacking (renting rooms) to offset mortgage costs. Finally, automate savings from home equity (e.g., setting aside 10% of annual appreciation) to reinvest elsewhere. Patience is key—millennials who buy in their late 20s/early 30s can outpace those who wait until their 40s.
