
The Short Answers
- High-net-worth wealth management firms typically require a minimum asset threshold—often $1 million to $10 million, though elite firms target $100 million+.
- Fees vary by structure: private banks charge 0.5%–1.5% annually on assets under management, while family offices may take a flat retainer or performance-based cut.
- Top firms offer bespoke services—from art advisory to space investments—tailored to clients’ risk appetites and non-financial goals.
- Regulatory compliance is non-negotiable; firms must navigate anti-money-laundering laws, tax treaties, and cross-border reporting (e.g., CRS, FATCA).
- Client retention hinges on personalized service—many firms assign dedicated relationship managers who act as trusted advisors, not just transactional providers.
Deep Dive: The Full Picture
Wealth management for the ultra-affluent isn’t a product—it’s a relationship industry. The firms that dominate this space don’t sell mutual funds or robo-advice; they offer strategic partnerships where the client’s life goals (education, philanthropy, legacy) dictate the financial roadmap. Consider the case of a tech founder with concentrated stock options: a standard wealth manager might diversify holdings, but a high-net-worth wealth management firm would also model exit strategies, tax-lot optimization, and succession plans for heirs who may lack industry expertise. The difference isn’t just in the portfolio—it’s in the psychology of preservation. The landscape has fragmented in recent decades. Traditional private banks like UBS and Credit Suisse still command respect, but they now compete with independent wealth managers, single-family offices, and even fintech-adjacent platforms targeting younger high-net-worth individuals (HNWIs). The shift reflects a generational divide: older clients prioritize discretion and legacy, while younger ones demand transparency, impact investing, and digital integration. Firms that fail to adapt risk becoming irrelevant. Those that succeed often blur the line between banking and concierge services—think private jet logistics, cybersecurity for digital assets, or even personal security assessments for clients in high-risk industries.The Context You Need
The industry’s evolution mirrors the rise of global capital. In the 1990s, wealth management was dominated by European private banks catering to aristocrats and old-money families. Today, the center of gravity has shifted to Asia and the Americas, where new wealth is being created in tech, real estate, and commodities. A 2023 Capgemini report estimated that high-net-worth wealth management firms now manage over $100 trillion in assets worldwide, with the fastest growth in China, India, and the Gulf states. This isn’t just about more money—it’s about different money: illiquid assets (private equity, real estate), alternative investments (wine, vintage cars), and cross-border complexities (e.g., a Singaporean client with properties in Dubai and Monaco). The regulatory environment has also tightened. The Common Reporting Standard (CRS), enforced by the OECD since 2017, forces banks to share client data across jurisdictions, eliminating tax havens’ anonymity. Meanwhile, the Dodd-Frank Act and MiFID II in Europe impose stricter fiduciary duties, pushing firms to justify fees and conflicts of interest. For high-net-worth wealth management firms, compliance isn’t a cost—it’s a competitive differentiator. Clients increasingly demand firms that can navigate jurisdictional arbitrage while avoiding reputational risks.The Mechanics
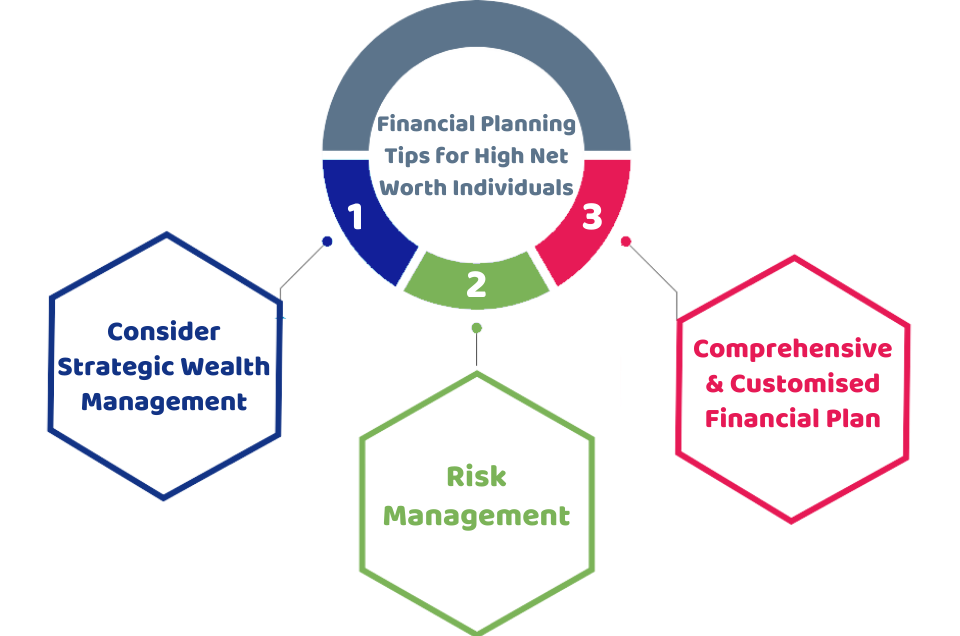
At the core, these firms operate on three pillars: asset allocation, risk management, and client service. Asset allocation isn’t a one-size-fits-all exercise. A client with a $1 billion endowment might allocate 30% to private equity, 20% to hedge funds, 15% to real assets, and 10% to cash—while a family with $50 million might prefer a 60/30/10 split between equities, bonds, and alternatives. The key variable? Liquidity needs. A family office might hold illiquid assets for decades, whereas a private bank client may require quarterly distributions. Risk management goes beyond diversification. Elite firms employ scenario modeling—simulating crises like hyperinflation, geopolitical conflicts, or market crashes—to stress-test portfolios. Some even offer insurance-linked securities (ILS) or parametric reinsurance to hedge against tail risks. The service layer is where firms distinguish themselves. Top-tier high-net-worth wealth management firms provide: - Tax optimization across 50+ jurisdictions. - Estate planning with trusts, dynastic vehicles, and charitable foundations. - Philanthropic advisory to align giving with legacy goals. - Digital asset custody for crypto and NFTs (a growing demand post-2020). The fee structures reflect this complexity. Private banks typically charge 0.75%–1.5% AUM, with tiered discounts for larger balances. Family offices may operate on flat retainers ($250K–$1M/year) or performance fees (10–20% of gains). The highest-end firms, like Lazard’s private wealth division or Brown Brothers Harriman, combine both models—charging for discretionary management while offering separately managed accounts for clients who prefer hands-off control.Details That Change the Picture
Not all high-net-worth clients are created equal. A first-generation wealth creator (e.g., a tech CEO) has different needs than a multi-generational heir (e.g., a European aristocrat). The former may require liquidity planning for IPO proceeds or succession strategies for non-family executives. The latter might focus on preserving bloodlines through trusts and cultural asset management (art, wine, rare manuscripts). Firms that miscategorize clients risk misaligned advice. For example, a private bank might push a conservative bond portfolio to an heiress, only to see her fortune erode due to inflation—while a high-net-worth wealth management firm would have layered in inflation-linked securities and real assets. The rise of alternative investments has also reshaped the industry. In 2022, alternatives (private equity, hedge funds, real assets) accounted for 40% of HNWI portfolios, up from 25% in 2010. This shift demands specialized expertise. A firm like BlackRock’s private wealth group can offer access to its $9 trillion AUM for tailored strategies, while boutique managers like Moore Capital focus on distressed assets and special situations. The challenge? Due diligence. A single bad investment can wipe out years of gains. Top firms employ in-house analysts to vet managers, negotiate terms, and monitor performance—often at a fraction of the cost clients would pay independently."Wealth management at this level isn’t about beating the S&P 500—it’s about never losing the principal while achieving the client’s non-financial objectives. The firms that understand this don’t just manage money; they preserve legacies." — Mark Weinberger, former CEO of EY and advisor to ultra-high-net-worth families
| Client Segment | Key Service Differentiators |
|---|---|
| First-Generation Wealth Creators | Exit planning, concentrated stock management, cybersecurity for digital assets |
| Multi-Generational Families | Dynastic trusts, cultural asset preservation, philanthropic structuring |
| Global Nomads (Expatriates) | Cross-border tax optimization, residency planning, multi-currency cash management |
Conclusion
The high-net-worth wealth management firms of tomorrow will be defined by agility and specialization. As wealth becomes more concentrated in alternatives and younger generations demand impact and transparency, firms that cling to traditional models risk obsolescence. The winners will be those that combine deep institutional expertise with personalized service—whether that means advising a sovereign wealth fund on infrastructure investments or helping a family office structure a space tourism venture. The barrier to entry isn’t just capital; it’s trust. Clients don’t just want returns—they want peace of mind. The industry’s future hinges on three trends: technology integration (AI for portfolio modeling, blockchain for settlements), geographic expansion (especially in Asia and the Middle East), and purpose-driven investing. Firms that can navigate these shifts while maintaining discretion and fiduciary rigor will define the next era of wealth management. For the ultra-affluent, the question isn’t how much they earn—it’s how they endure.Comprehensive FAQs
Q: What’s the minimum asset requirement to work with a top high-net-worth wealth management firm?
A: It varies by firm. Boutique managers often start at $10 million–$50 million, while elite private banks like Julius Baer or Lombard Odier target clients with $100 million+. Family offices typically require $500 million+ in assets to justify the overhead.
Q: How do fees compare between private banks and independent wealth managers?
A: Private banks charge 0.5%–1.5% AUM, with discounts for larger balances. Independent managers may take 1%–2% AUM but offer more flexibility. Family offices often operate on flat retainers ($250K–$1M/year) or performance fees (10–20% of gains).
Q: Can high-net-worth wealth management firms help with non-financial goals like philanthropy?
A: Absolutely. Many firms have dedicated philanthropic advisory teams that help structure charitable foundations, donor-advised funds, and impact investments. For example, Bank of America’s Private Bank offers philanthropic planning as a core service.
Q: What’s the biggest mistake clients make when choosing a wealth manager?
A: Prioritizing fees over fit. A client might select a firm based on low AUM charges, only to realize the manager lacks expertise in their specific needs (e.g., concentrated stock, real estate, or crypto). The best firms conduct in-depth discovery sessions to align services with goals.
Q: How do high-net-worth wealth management firms handle estate planning for families?
A: They use dynastic trusts, generation-skipping trusts, and private foundations to minimize taxes and preserve wealth across generations. Some firms, like Wilmington Trust, specialize in complex estate structures for ultra-high-net-worth families.
Q: Are there any red flags when evaluating a wealth management firm?
A: Yes:
- High turnover in client-facing staff (sign of poor training or culture).
- Vague fee structures (e.g., hidden performance fees).
- Lack of transparency on conflicts of interest (e.g., pushing proprietary products).
- No clear succession plan for the client’s wealth.
Q: How do firms ensure confidentiality for ultra-high-net-worth clients?
A: They use multi-layered security protocols, including encrypted communications, private banking units, and strict access controls. Some firms, like Lazard’s private wealth group, operate under separate legal entities to shield client data from corporate scrutiny.
Q: What’s the role of technology in modern high-net-worth wealth management?
A: Firms now use AI for portfolio optimization, blockchain for secure transactions, and cybersecurity tools to protect digital assets. For example, Northern Trust offers digital vaults for crypto and predictive analytics to flag market risks before they materialize.
