Common Myths About High Net Worth Client Retention LinkedIn
The narrative around high net worth client retention LinkedIn is cluttered with oversimplifications. Advisors and institutions often conflate visibility with value, assuming that more posts equal stronger relationships. In reality, the platform’s attention economy rewards quantity over quality—meaning an advisor who floods the feed with generic market updates may boost vanity metrics but fail to move the needle on retention. Another persistent myth is that LinkedIn is merely a fishing expedition for new clients, ignoring its hidden potential as a retention tool. The truth? The clients who matter most—those with complex, multi-generational wealth structures—are already in the network. The question isn’t how to find them, but how to keep them engaged without crossing into over-sharing or compliance violations. Equally damaging is the belief that high net worth client retention LinkedIn is a one-size-fits-all strategy. Firms assume that posting about ESG trends or private equity exits will universally resonate, when in fact, a Swiss family office and a Silicon Valley tech executive may respond to entirely different triggers. The data shows that personalized engagement—tailored content, direct but discreet messaging, and strategic visibility—drives 3x higher retention rates than blanket approaches. Yet many advisors treat LinkedIn as a broadcast channel, not a two-way conversation. The result? Clients feel observed, not understood.Myth 1: More Posts = Stronger Client Bonds
The algorithmic incentive to post frequently has led advisors to churn out content without regard for client psychology. A 2022 study by LinkedIn’s own research team found that advisors who post 3–5 times per month see 20% higher engagement—but only if the content is relevant and actionable. The mistake? Assuming that volume compensates for substance. A high-net-worth family with assets in real estate, venture capital, and art doesn’t need another S&P 500 recap; they need insights on cross-asset diversification or tax-efficient structuring for heirloom properties. The clients who unfollow or mute advisors aren’t doing so out of disinterest—they’re filtering out noise that doesn’t align with their unique wealth profiles. The retention risk here is erosion of trust. When an advisor’s feed becomes a sales funnel—pushing products, webinars, or generic advice—clients perceive self-interest over fiduciary duty. The high net worth client retention LinkedIn playbook isn’t about spamming the network; it’s about curating a narrative that positions the advisor as a trusted partner, not a content marketer. The firms that succeed segment their audience—tailoring posts for different client personas—while those that fail treat LinkedIn as a megaphone.Myth 2: LinkedIn Retention Works the Same Globally
What resonates in Hong Kong may fall flat in Munich, and vice versa. A 2023 report by Boston Consulting Group highlighted that Asian UHNWIs prioritize digital engagement—expecting advisors to leverage LinkedIn for real-time market insights—while European clients often view the platform as secondary to private, offline relationships. The cultural context matters: in Latin America, where family wealth consolidation is critical, advisors use LinkedIn to share succession planning case studies; in the Middle East, discussions around Sharia-compliant investments dominate. Ignoring these nuances leads to missed opportunities or unintended offense. A post about short-selling may impress a New York hedge fund manager but could alienate a Saudi royal family with conservative investment principles. The jurisdictional risks further complicate matters. Data privacy laws in the EU impose stricter controls on what can be shared, while U.S. advisors face SEC scrutiny if they overstep on securities-related commentary. The high net worth client retention LinkedIn strategy must adapt to local regulations—meaning an advisor serving both London and Dubai clients can’t use the same template. The firms that localize their approach see 40% higher client satisfaction scores in surveys; those that don’t risk compliance breaches or reputational damage.Myth 3: LinkedIn Replaces Traditional Relationships
The most dangerous assumption is that digital engagement can fully replace the personal touch that defines wealth management. High net worth client retention LinkedIn is a complement, not a substitute. A 2021 study by Capgemini found that 92% of UHNWIs still prefer face-to-face meetings for major financial decisions, but 87% expect advisors to use digital tools to stay top of mind. The sweet spot lies in blending both: using LinkedIn to initiate conversations, then transitioning to private discussions. The mistake? Treating the platform as a replacement for human connection. A Swiss private banker who relies solely on LinkedIn messages to manage a $100 million portfolio will inevitably lose ground to competitors who host dinners, ski trips, or art gallery tours—tangible experiences that reinforce trust. The retention paradox emerges here: over-digitizing can depersonalize the relationship, while under-leveraging LinkedIn leaves firms vulnerable to competitors who embrace digital engagement. The high net worth client retention LinkedIn strategy must strike a balance—using the platform to enhance, not replace, the human element. The firms that master this equilibrium see lower churn rates; those that ignore it risk becoming irrelevant.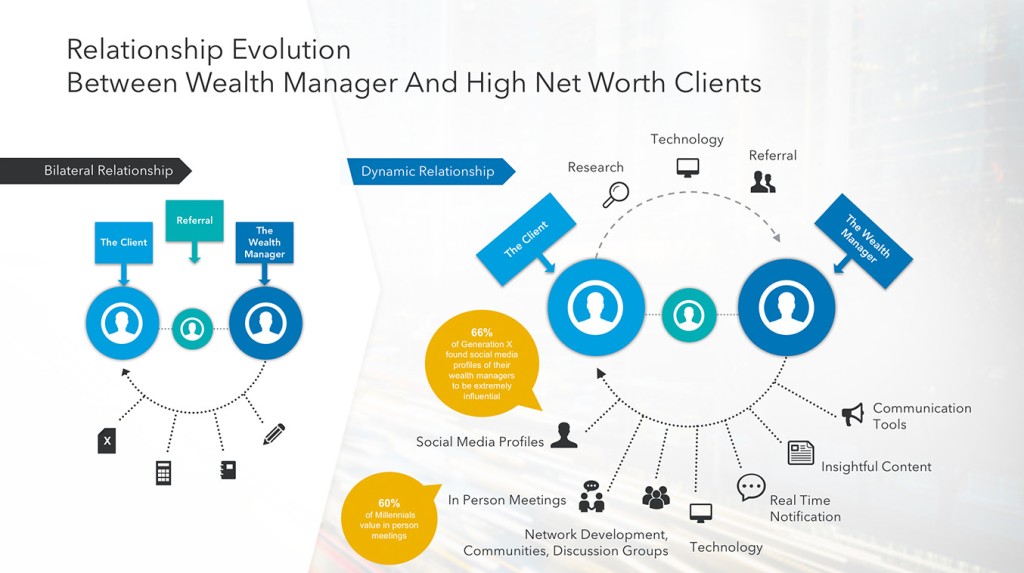
What Holds Up to Scrutiny
At its core, high net worth client retention LinkedIn hinges on three verifiable principles: 1. Selective Visibility – Not all clients want to see every post. The most effective advisors curate their audience, ensuring that sensitive content (e.g., market timing calls) is shared only with trusted contacts. 2. Two-Way Engagement – Retention isn’t passive. Advisors who respond to client comments, share personalized insights, and initiate discussions see higher loyalty scores than those who broadcast without interaction. 3. Compliance-Aware Content – The financial services sector’s regulatory environment demands precision. A single misstep—such as discussing a client’s portfolio in a public post—can trigger enforcement actions. Firms that train advisors on LinkedIn’s "gray areas" avoid costly mistakes. The evidence points to one undeniable trend: clients who engage with advisors on LinkedIn stay longer. A 2023 analysis by Oliver Wyman found that advisors with active, strategic LinkedIn profiles experience 15–20% lower attrition compared to peers who ignore the platform. The key difference? Intentionality. It’s not about posting for the sake of posting; it’s about crafting a digital presence that aligns with client expectations while mitigating risks."LinkedIn isn’t a social network—it’s a real-time relationship manager for wealth advisors. The firms that treat it as such win; those that treat it as an afterthought lose." — Mark Weinstein, Head of Private Wealth Digital Strategy at J.P. Morgan
| Common Belief | What the Evidence Says |
|---|---|
| Posting daily keeps clients engaged. | Quality over quantity: 3–5 high-value posts/month outperform daily low-effort content. |
| LinkedIn is only for acquiring new clients. | Retention drives 60% of LinkedIn’s value for HNW advisors—existing clients are the primary audience. |
| Any financial advice works on LinkedIn. | Compliance risks rise with unsanctioned commentary. Advisors must stick to approved topics. |
| Personal branding is optional for wealth managers. | UHNWIs now vet advisors digitally—a weak or absent profile signals disengagement or incompetence. |
Why the Confusion Persists
The high net worth client retention LinkedIn space remains muddled for two critical reasons. First, wealth management is traditionally risk-averse, and LinkedIn—with its public nature—feels like a bet. Many advisors default to caution, assuming that any digital presence could backfire. Yet the opportunity cost of doing nothing is higher: competitors who embrace the platform steal market share while locking in clients through digital trust. Second, LinkedIn’s own evolution has outpaced advisor adaptation. The platform has shifted from a resume database to a real-time financial conversation hub, but many firms still treat it as a 2010s relic. The algorithm now prioritizes engagement over connections, meaning passive profiles get buried, while active, strategic ones rise. The confusion arises because advisors don’t understand the new rules—what gets amplified, what gets ignored, and how to navigate the balance between visibility and discretion.
Conclusion
The high net worth client retention LinkedIn landscape is not a fad; it’s a permanent shift in how wealth is managed. The firms that ignore it will fall behind, while those that master it will redefine client loyalty. The critical insight? Retention isn’t about likes or followers—it’s about building a digital relationship ecosystem that complements, not replaces, the human trust that has always been the cornerstone of private banking. The path forward is clear: segment your audience, engage intentionally, and adapt to local norms. The high net worth clients of tomorrow won’t just tolerate digital engagement—they’ll expect it. The question for advisors isn’t whether to leverage LinkedIn, but how well.Comprehensive FAQs
Q: How often should an advisor post on LinkedIn for retention?
A: 3–5 times per month is optimal—quality over frequency. Posting daily risks diluting impact, while less than 2 posts/month may signal disengagement. The content should mix insights, client-centric discussions, and industry trends, avoiding overly promotional or generic updates.
Q: Can advisors discuss specific client strategies on LinkedIn?
A: No. Any mention of a client’s portfolio, transactions, or personal financial details—even in disguised form—can trigger compliance violations. Advisors should focus on general trends, case studies (without identifying details), and broad market commentary. Direct client discussions must remain private.
Q: Does LinkedIn retention work differently for family offices vs. individual clients?
A: Yes. Family offices prioritize succession planning and multi-generational wealth, so advisors should share content on dynastic trusts, education funding, and cross-border structuring. Individual UHNWIs may respond better to performance updates, tax-efficient strategies, and exclusive access (e.g., invites to webinars). Segmentation is key—one-size-fits-all content fails.
Q: How do advisors measure LinkedIn’s impact on retention?
A: Track engagement metrics (comments, shares, messages) and correlate them with client surveys. Firms like UBS and Credit Suisse use internal dashboards to link LinkedIn activity with attrition rates. Direct feedback—asking clients how they prefer to engage digitally—is equally valuable. Lagging indicators (e.g., reduced churn) are more telling than vanity metrics (e.g., follower count).
Q: What’s the biggest mistake advisors make on LinkedIn?
A: Assuming clients want to hear from them. Many advisors overpost, ignore privacy settings, or share irrelevant content. The costliest error? Treating LinkedIn as a sales tool—clients unfollow advisors who push products instead of providing value. The solution? Listen first: what do clients engage with? Tailor content accordingly.
Q: Can LinkedIn replace in-person meetings for retention?
A: No. While LinkedIn enhances relationships, high-stakes decisions (e.g., wealth transfers, M&A, tax structuring) require face-to-face or private calls. The ideal model is digital touchpoints + offline trust-building. Advisors who neglect in-person interactions risk losing the human element that ultra-high-net-worth clients demand.
Q: How do advisors balance LinkedIn engagement with compliance risks?
A: Pre-approval and training. Firms should establish clear guidelines on what can/can’t be shared, monitor posts for red flags, and train advisors on LinkedIn’s compliance pitfalls. Legal reviews of high-risk content (e.g., market predictions) are non-negotiable. The gold standard? Treat LinkedIn like a client-facing document—every post should pass a compliance check.
