
Breaking Down the Numbers
Grameen Bank’s financials are a study in contradictions. On paper, it’s one of the most transparent microfinance institutions in the world, with annual reports that detail everything from loan portfolios to social performance metrics. Yet, the Grameen Bank net worth remains a moving target, subject to interpretations that vary by stakeholder. For regulators, it’s a measure of systemic risk; for development economists, it’s evidence of a working alternative to traditional banking. The bank’s total asset base has grown exponentially, but translating that into a single net worth figure requires navigating layers of debt, equity, and intangible social value. The challenge lies in defining what “net worth” means for an institution like Grameen. In conventional banking, it’s a straightforward calculation of assets minus liabilities. But Grameen’s financial model is built on principles that defy conventional metrics. Its loans aren’t collateral-backed; they’re underpinned by trust and community accountability. This makes traditional valuation methods unreliable. The bank’s reported profitability—consistently high repayment rates (often cited above 98%)—has attracted institutional investors, but it hasn’t immunized Grameen from the volatility of emerging markets. Currency devaluations, political instability, and shifts in donor funding all cast long shadows over its long-term financial stability.The Verified Baseline
As of the latest verified disclosures, Grameen Bank’s total assets are estimated to exceed $1.5 billion, a figure that includes loan portfolios, cash reserves, and fixed assets like branches and technology infrastructure. The bank’s shareholder equity—a more precise indicator of net worth—has been consistently reported in the $300–$400 million range over the past decade, though exact figures fluctuate with currency adjustments and accounting practices. These numbers are drawn from audited financial statements, which the bank publishes annually, adhering to international accounting standards. What’s less often discussed is the composition of Grameen’s net worth. Unlike commercial banks, its balance sheet includes intangible assets: the social capital of its borrowers, the trust built over generations, and the brand recognition that allows it to operate with minimal advertising. The bank’s ownership structure is another unique feature—it’s majority-owned by its borrowers, who hold 95% of the shares. This democratic model ensures that profits (when declared) are reinvested in the system rather than extracted by shareholders. The remaining 5% is held by the government of Bangladesh, a vestige of its origins as a public-private partnership.What the Estimates Suggest
Industry analysts and development finance institutions often venture beyond verified figures to estimate Grameen Bank’s true economic impact. Some suggest its net worth, when factoring in the multiplier effect of its lending—where every loan generates secondary economic activity—could be two to three times higher than reported equity. These estimates rely on models that attribute Grameen’s operations to broader GDP growth in rural Bangladesh, where its borrowers are concentrated. For example, studies have linked Grameen’s microenterprise loans to increased household incomes, which in turn drive local spending and tax revenues. However, such estimates are speculative. Grameen’s financial health is also tied to its ability to access low-cost capital. The bank has historically relied on donor funds, concessional loans from multilateral institutions, and deposits from its borrowers. In recent years, it has explored Islamic finance instruments, which align with the religious preferences of many of its clients. These financing mechanisms introduce new variables—sharia compliance costs, liquidity risks—that aren’t captured in traditional net worth calculations. Additionally, the depreciation of the Bangladeshi taka against the US dollar has eroded the real value of Grameen’s foreign-currency-denominated debt, adding another layer of uncertainty to any estimate of its net asset value.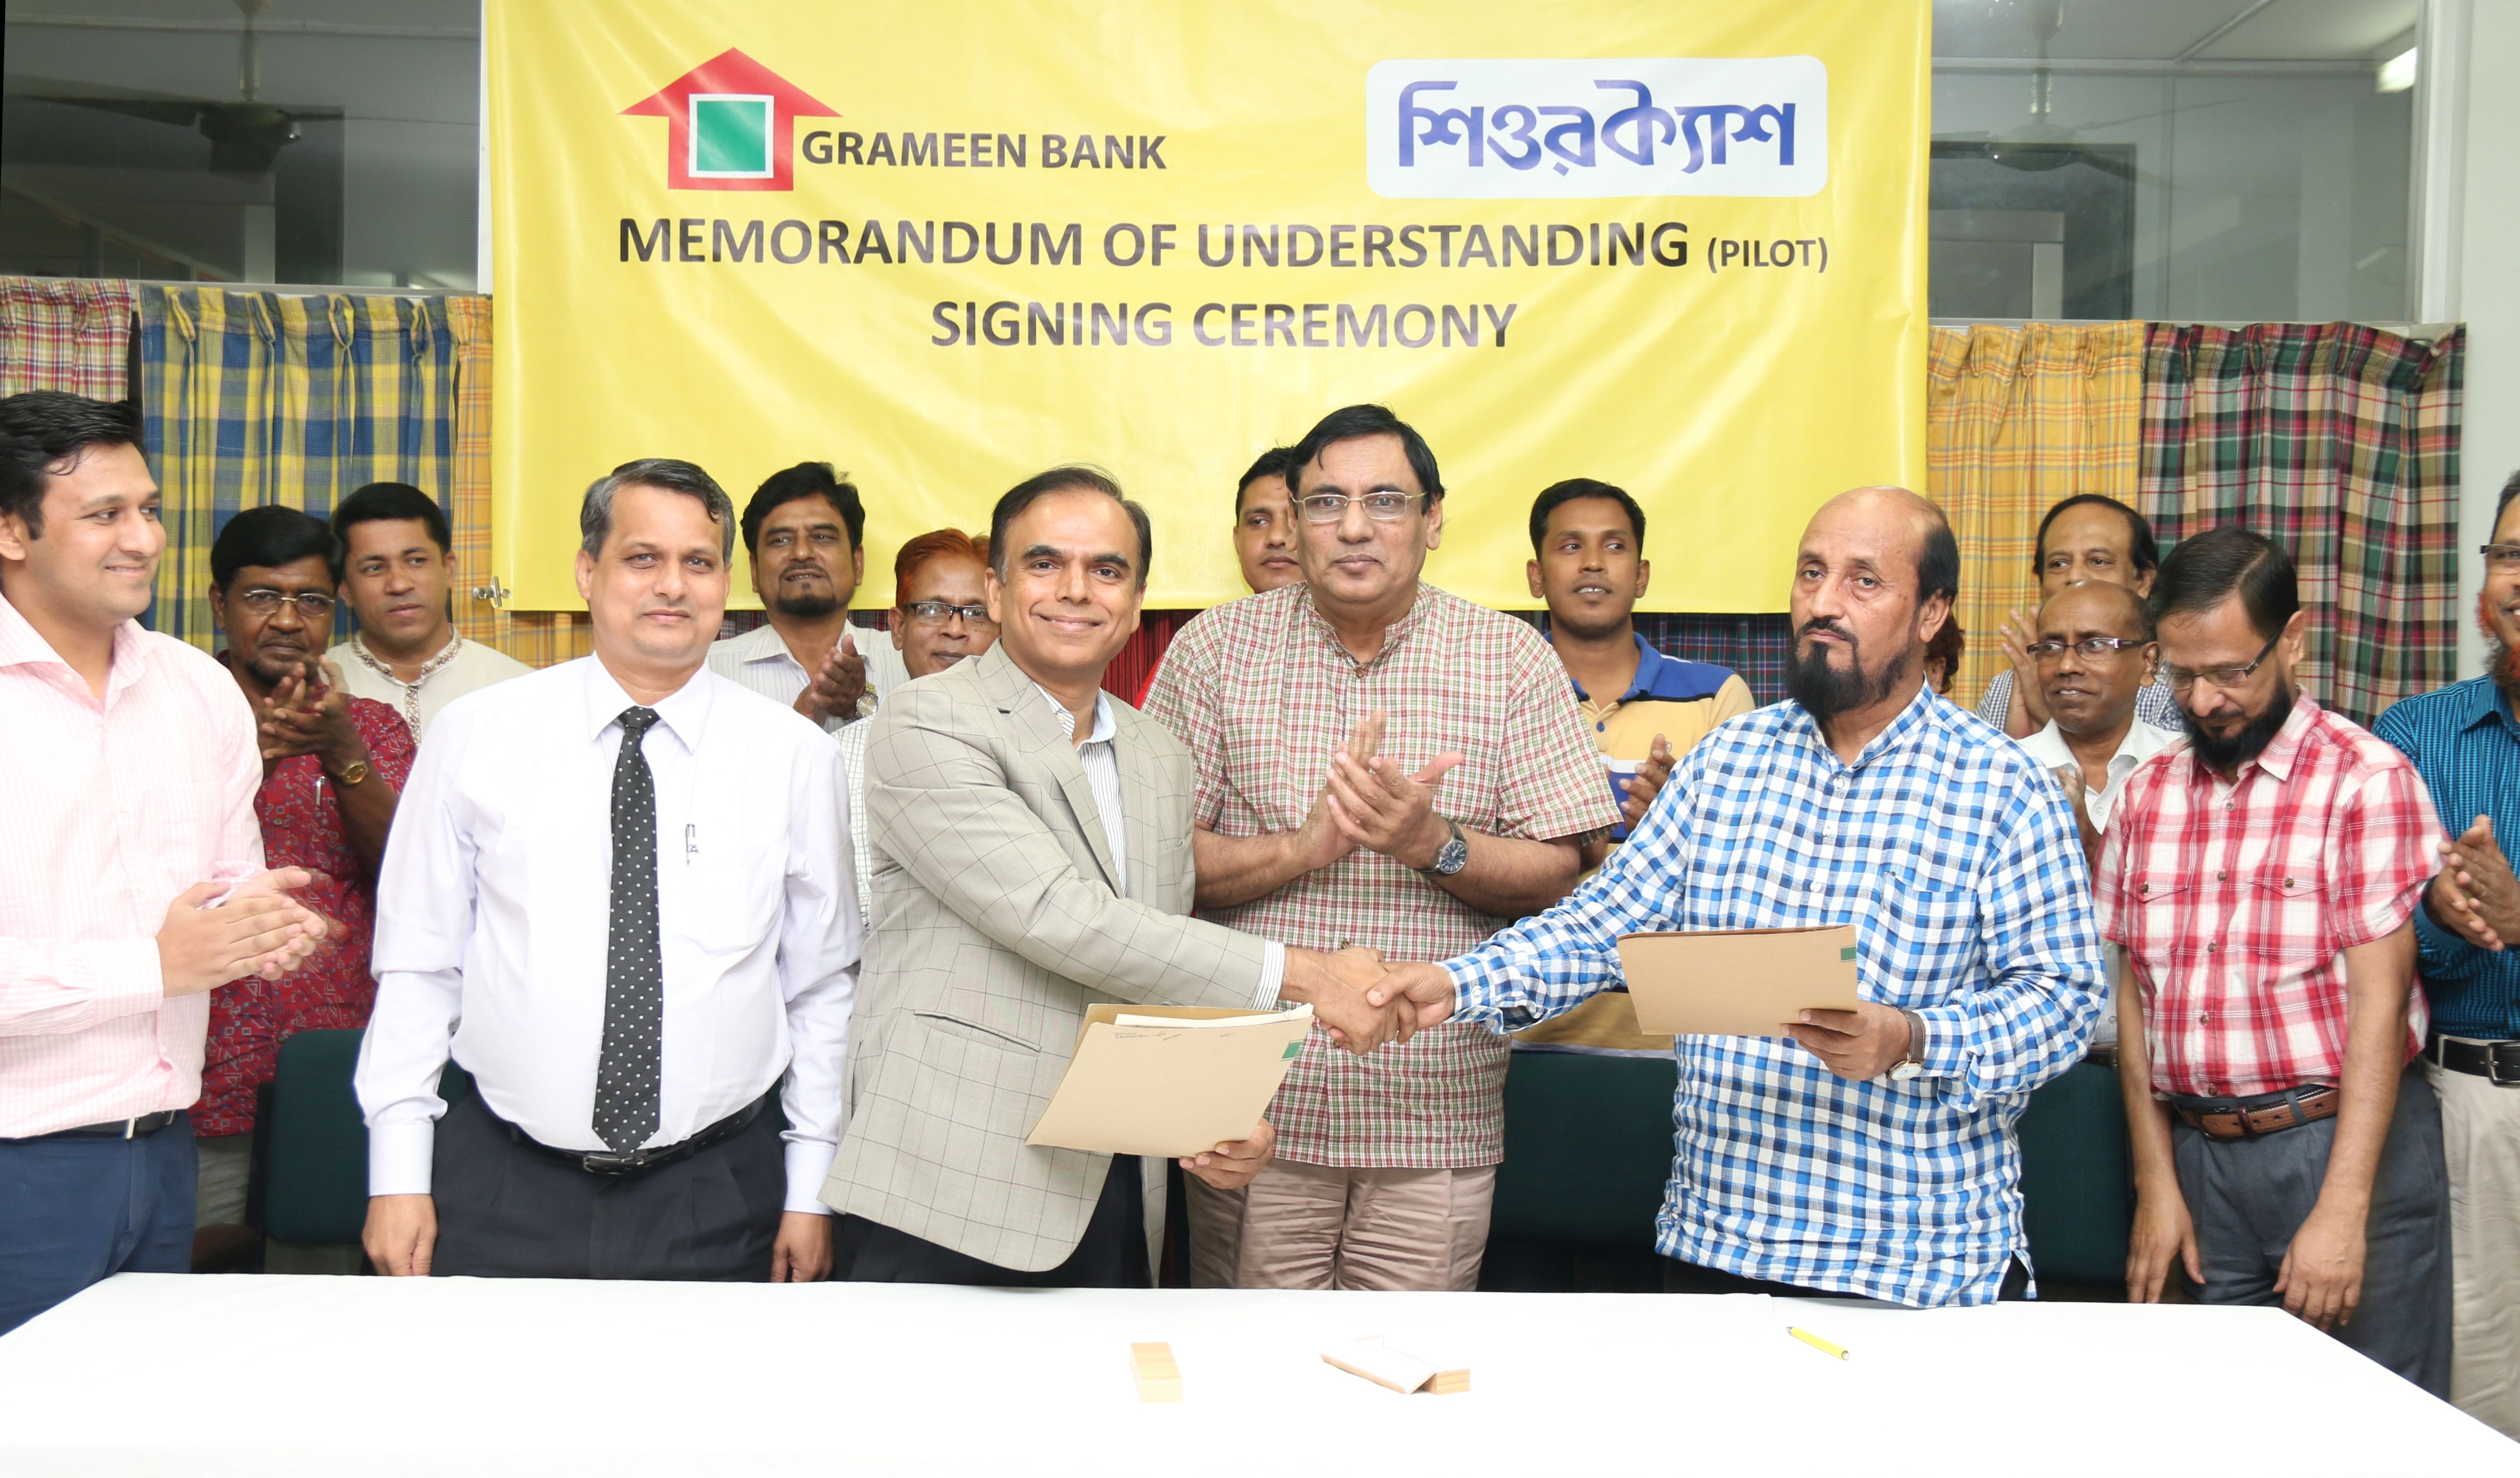
Case Study: A Closer Look
No discussion of Grameen Bank’s net worth is complete without examining its 2010–2013 crisis—a period when the bank’s financial sustainability was publicly questioned. The controversy centered on allegations of predatory lending practices, high interest rates (though still below commercial benchmarks), and the bank’s expansion into for-profit ventures, such as Grameen Phone. Critics argued that these moves diluted Grameen’s social mission, while supporters maintained that diversification was necessary to sustain its net worth amid rising operational costs. The turning point came in 2013, when the government of Bangladesh nationalized Grameen Bank and appointed a new managing director. The move was framed as a corrective measure, but it also raised questions about the long-term viability of Grameen’s financial model. The bank’s loan portfolio quality came under scrutiny, with some analysts suggesting that its non-performing loan ratio had crept higher than previously disclosed. The government’s intervention, however, also highlighted a broader truth: Grameen’s net worth was no longer just a financial matter—it had become a geopolitical asset, tied to Bangladesh’s ambitions to position itself as a leader in social entrepreneurship.“Grameen Bank’s financial success is not an end in itself; it’s a means to an end. The real measure of its net worth lies in whether it can continue to serve the poor without compromising its principles.” — Muhammad Yunus, 2014
| Factor | Estimated Impact on Grameen Bank Net Worth |
|---|---|
| Government Intervention (2013) | Short-term volatility in equity valuation; long-term uncertainty over operational autonomy. |
| Diversification into Telecom (Grameen Phone) | Reportedly added $500M–$700M to consolidated assets, but diluted focus on core microfinance. |
| Currency Depreciation (BDT vs. USD) | Eroded real value of foreign debt by 15–20% over five years, affecting reported equity. |
| Borrower-Owned Equity Structure | Ensures 95% of profits remain within the system, reinforcing social capital but limiting external investment. |
| Repayment Culture & Trust Model | Sustains >98% repayment rates, reducing default risks and stabilizing asset quality. |
What This Means Going Forward
Grameen Bank’s financial trajectory will be shaped by three critical forces: regulatory pressure, technological disruption, and the evolving expectations of its borrowers. The government’s continued oversight—while stabilizing the bank—has also created tensions between its social mandate and commercial realities. If Grameen is forced to prioritize profitability over outreach, its net worth may grow, but at the cost of its original purpose. Conversely, if it remains true to its roots, it risks financial instability in an era where digital banking and fintech are reshaping microfinance. The rise of mobile money platforms in Bangladesh presents both a threat and an opportunity. Grameen Phone’s dominance in the telecom sector has given the bank a first-mover advantage in financial inclusion, but it also faces competition from newer players offering lower-cost, digital-first services. The bank’s ability to leverage its brand while adapting to fintech innovations will determine whether its net worth remains a symbol of social impact or becomes just another balance sheet in the global financial system.
Conclusion
The story of Grameen Bank’s net worth is more than a ledger entry—it’s a reflection of the tensions between capitalism and compassion. The bank’s financial success has been undeniable, but its true value lies in whether it can reconcile profitability with its founding principles. As Bangladesh’s economy matures, Grameen faces a crossroads: double down on its social mission and risk financial marginalization, or embrace commercialization and risk losing its soul. What’s clear is that Grameen’s financial model has already changed the game. Other microfinance institutions now benchmark themselves against its asset growth, repayment rates, and borrower ownership structure. The question isn’t whether Grameen Bank will remain relevant—it’s how it will redefine relevance in an era where financial inclusion is no longer a niche experiment but a global imperative.Comprehensive FAQs
Q: How does Grameen Bank’s net worth compare to other microfinance institutions?
Grameen Bank’s net asset value is among the highest in the sector, largely due to its scale and borrower-owned equity structure. Institutions like BRAC Bank in Bangladesh or Compartamos in Mexico have comparable assets but operate under different ownership models. Grameen’s unique advantage is its social capital, which traditional banks cannot replicate.
Q: Is Grameen Bank profitable, and how does that affect its net worth?
Yes, Grameen Bank has been consistently profitable for decades, with repayment rates above 98%. Its profitability is a key driver of its net worth, as it allows reinvestment in lending and infrastructure. However, profitability alone doesn’t guarantee long-term stability—regulatory changes, currency risks, and competition remain critical factors.
Q: What role does the Bangladeshi government play in Grameen Bank’s financial health?
The government holds 5% of Grameen’s shares, a remnant of its original public-private partnership. Its intervention in 2013—including the appointment of a new managing director—was aimed at restructuring governance but introduced uncertainty. The government’s stance on Grameen’s future could significantly impact its operational autonomy and, by extension, its net asset growth.
Q: Can Grameen Bank’s model be replicated globally?
Grameen’s financial and social model has inspired microfinance institutions worldwide, but replication faces challenges. Cultural differences, regulatory environments, and local economic conditions make direct adoption difficult. Success stories exist—such as Kiva’s peer-to-peer lending—but none have matched Grameen’s scale or borrower ownership structure.
Q: How does Grameen Bank’s net worth affect its borrowers?
A strong net worth translates to greater lending capacity, lower default risks, and more stable interest rates for borrowers. However, if Grameen prioritizes financial returns over social impact, borrowers—especially in rural areas—could face higher costs or reduced access. The bank’s borrower-owned equity ensures some alignment of interests, but governance reforms remain critical.
