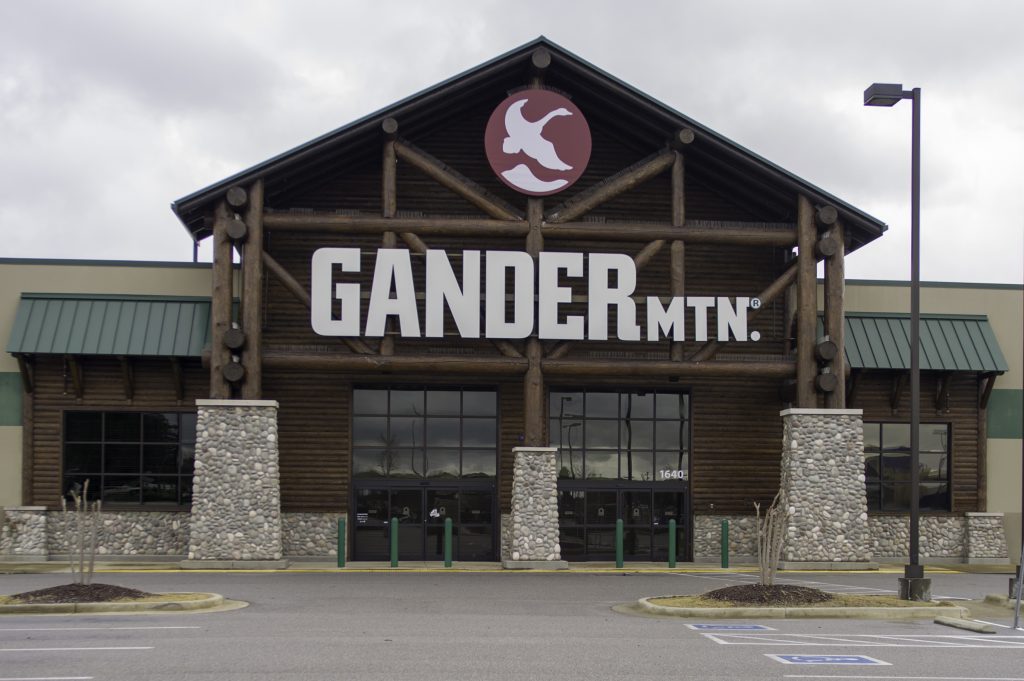
Where It All Began
Cabela’s trace its origins to 1961, when Jim and Richard Cabela opened a single hunting and fishing shop in Sidney, Nebraska. What started as a family-run operation grew into a retail empire, fueled by a countercultural appeal: the brand didn’t just sell gear—it sold an experience. The net worth of Cabela’s when Gander Mountain bought them would later be tied to this legacy, but the early years were about grit. The company pioneered mail-order catalogs in the 1970s, a bold move that predated Amazon’s dominance by decades. By the 1990s, Cabela’s had expanded into superstores, complete with indoor shooting ranges and taxidermy workshops, creating a destination retail experience that competitors couldn’t replicate. The brand’s financial trajectory in the 2000s was nothing short of meteoric. Cabela’s went public in 1999, and by 2010, its market cap hovered around $1.5 billion. The company was profitable, with margins that envy even the most efficient retailers. Its valuation when private equity interest peaked made it a prime target. But beneath the surface, cracks were forming. The rise of e-commerce was eroding foot traffic, and the company’s debt levels were climbing. By the time Gander Mountain came calling, Cabela’s was a high-value asset—but one with structural challenges.The Early Signs
The first red flags appeared in 2014, when Cabela’s reported its first quarterly loss in decades. The blame was laid at the feet of a failed e-commerce pivot and overinvestment in store expansions. Analysts at the time noted that while Cabela’s still commanded premium prices, its growth was stagnant. The company’s financial health when Gander Mountain approached was a mix of strength and vulnerability: strong brand equity, but thinning margins and a balance sheet that couldn’t support aggressive expansion. Gander Mountain, meanwhile, was on a different trajectory. Founded in 1982 as a single store in Minnesota, the chain had grown into a discount-oriented competitor, focusing on volume over brand prestige. Its 2012 IPO valued the company at $1.2 billion, but by 2016, it was struggling with its own debt load. The acquisition of Cabela’s was supposed to be the solution—a way to combine Gander’s operational efficiency with Cabela’s brand power. Yet the synergy assumptions behind the deal were built on shaky ground. Industry reports suggested that Gander’s discount model would cannibalize Cabela’s higher-margin sales, while Cabela’s legacy customers resisted Gander’s aggressive pricing tactics.The Turning Point
The turning point came in 2017, when Cerberus Capital Management orchestrated the merger. The private equity firm saw an opportunity to create a retail giant that could outmaneuver competitors like Bass Pro Shops and Dick’s Sporting Goods. The net worth of Cabela’s when Gander Mountain bought them was a key variable in the equation—high enough to justify the debt, but only if the combined entity could deliver on cost savings. The deal was structured with $1.8 billion in debt, leaving the new company leveraged to the hilt. What followed was a clash of cultures. Gander’s cost-cutting measures—store closures, layoffs, and a shift toward private-label products—alienated Cabela’s longtime employees and customers. The brand’s reputation for quality took a hit as Gander pushed discount promotions that undercut Cabela’s premium positioning. By 2018, the combined company was already facing downgrades from credit rating agencies, signaling that the financial assumptions of the acquisition were unraveling."Gander Mountain thought they could turn Cabela’s into a Walmart for outdoor gear. What they didn’t account for was that Cabela’s customers don’t shop at Walmart." — Retail analyst, 2019The misalignment became glaringly obvious when the company reported a $1.1 billion loss in 2020. The pandemic exacerbated the problem, as foot traffic plummeted and e-commerce struggles persisted. The valuation of Cabela’s at acquisition had been based on the assumption that the two brands could coexist under one roof. Instead, they became liabilities.
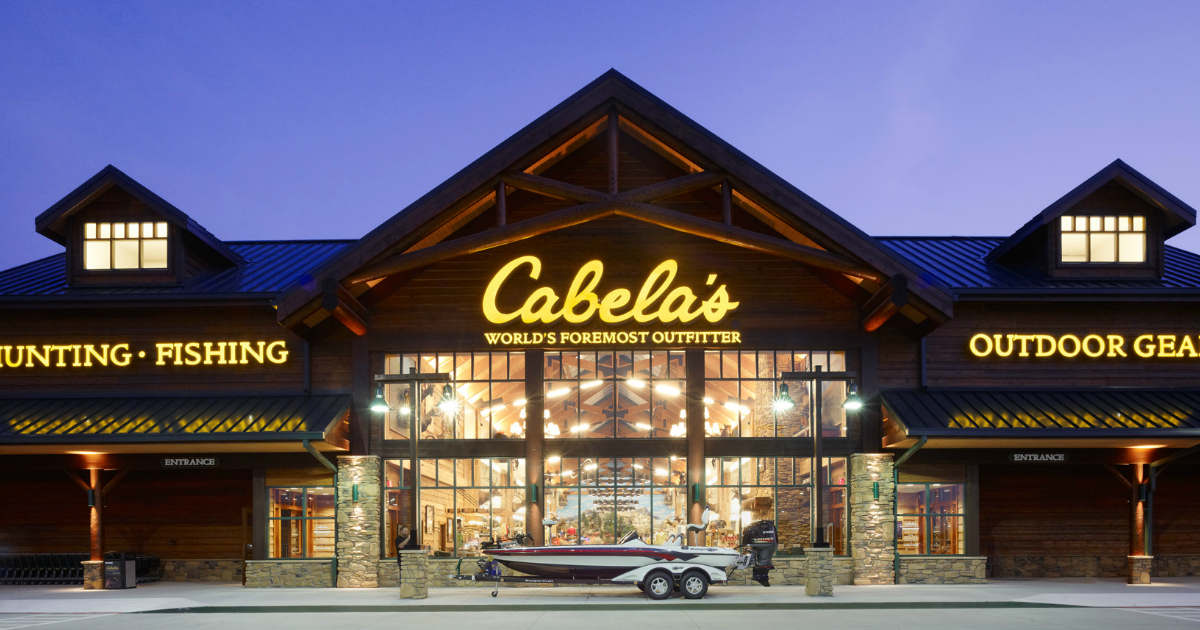
The Build-Up, Year by Year
| Period | Key Events |
|---|---|
| 2014–2016 | Cabela’s reports first quarterly loss; Gander Mountain explores strategic options. Private equity firms begin circling. |
| 2017 | Cerberus-backed Gander Mountain acquires Cabela’s for $2.1 billion. Debt-fueled merger announced. |
| 2018 | First signs of integration struggles: store closures, layoffs, and declining same-store sales. Credit ratings downgraded. |
| 2019 | Company misses earnings estimates; e-commerce losses widen. Analysts question the logic of the merger. |
| 2020 | $1.1 billion net loss reported. Pandemic accelerates decline; Gander’s discount model fails to resonate with Cabela’s customer base. |
Lessons From the Journey
- Debt as a double-edged sword: The $1.8 billion leverage assumed synergies would materialize quickly. They didn’t.
- Brand dilution risks: Gander’s discount strategy eroded Cabela’s premium positioning without gaining new customers.
- Cultural misalignment: Cabela’s heritage employees resisted Gander’s cost-cutting measures, leading to high turnover.
- E-commerce underestimation: The company failed to adapt to digital shopping trends, leaving it vulnerable to Amazon and REI.
- Private equity timelines: Cerberus expected a 3–5 year turnaround. The reality was closer to 2 years of losses before a pivot was even attempted.
Where Things Stand Today
As of 2024, the remnants of the Gander-Cabela’s merger are a shadow of what was promised. The company, now operating under a restructured model, has shed much of its debt but at the cost of its former dominance. Cabela’s flagship stores have been scaled back, and the brand’s market position when Gander Mountain acquired it is now a fraction of its peak. The outdoor retail landscape has shifted, with REI and Bass Pro Shops emerging as the clear leaders. What was once a $2.1 billion bet has become a case study in how private equity can overreach in retail. The financial aftermath of the acquisition is still being tallied. While the company avoided bankruptcy, its net worth when Gander Mountain took over is now a footnote in retail history—a high-stakes gamble that backfired. The lessons are clear: brand equity isn’t just about logos; it’s about culture, customer loyalty, and the willingness to adapt. Gander Mountain’s playbook assumed that scale alone could overcome these challenges. It didn’t.
Conclusion
The story of Gander Mountain’s acquisition of Cabela’s is more than a financial footnote. It’s a cautionary tale about the limits of private equity in retail, the fragility of brand value, and the dangers of assuming synergies will save a struggling merger. The valuation of Cabela’s when Gander Mountain bought them was high, but the company’s intangible assets—its reputation, its customer trust, and its cultural cachet—proved harder to monetize than the balance sheet suggested. For outdoor retailers, the deal serves as a warning. The industry is consolidating, but the winners will be those who balance growth with discipline, innovation with heritage. Cabela’s and Gander Mountain’s collision shows what happens when strategy outpaces reality. The numbers may have been compelling on paper, but in the end, it was the people—the customers, the employees, and the communities tied to these brands—that dictated the outcome.Comprehensive FAQs
Q: What was the exact purchase price of Cabela’s by Gander Mountain?
A: The acquisition was valued at $2.1 billion, including debt assumptions. The deal was structured with Cerberus Capital Management providing financing, leaving the combined entity heavily leveraged.
Q: Did the merger ever achieve the projected cost savings?
A: No. Industry estimates suggested synergies of $150–200 million annually, but by 2020, the company was still burning cash. The integration failed to deliver on promised efficiencies.
Q: How did Cabela’s stock perform after the acquisition?
A: Cabela’s was a private company post-acquisition, but its parent entity’s stock (Gander Mountain) plummeted after the merger was announced. The company’s market cap eroded as losses mounted.
Q: Are there any remaining assets from the original Cabela’s brand?
A: Yes, but significantly scaled back. The company retained the Cabela’s name for select stores and e-commerce, though the brand’s footprint is a fraction of its pre-2017 size.
Q: What went wrong with the e-commerce strategy?
A: The merged entity struggled with inventory duplication, high customer acquisition costs, and a failure to unify digital and physical retail experiences. Competitors like REI and Bass Pro Shops outpaced them in online sales.
Q: Could Gander Mountain have saved the deal?
A: Possibly, but only with a radical pivot—either doubling down on Cabela’s premium positioning or fully embracing Gander’s discount model. The company lacked the time and capital to execute either path successfully.
