The Short Answers
- GAAP net worth excludes non-recognized assets (e.g., unrealized gains in private equity) but includes liabilities like deferred taxes and contingencies.
- For businesses, it’s derived from the balance sheet’s shareholders’ equity—not personal wealth—adjusted for off-balance-sheet items.
- Individuals using GAAP must classify assets as either held-for-sale (marked to market) or held-for-use (carried at cost), affecting reported value.
- GAAP net worth often understates "true" wealth due to conservative accounting (e.g., goodwill amortization, impairment charges).

Deep Dive: The Full Picture
GAAP’s framework for calculating net worth isn’t about personal affluence; it’s about financial transparency. While a high-net-worth individual might tally cryptocurrency holdings at current prices, GAAP would only recognize them if they’re traded assets—and even then, with strict valuation rules. For corporations, the calculation of net worth using GAAP hinges on the balance sheet’s shareholders’ equity, but this figure is a starting point, not an endpoint. Hidden within are deferred tax liabilities, non-controlling interests, and treasury stock—each requiring GAAP-specific adjustments to reflect economic reality. The tension arises when GAAP’s conservatism clashes with market perceptions. A private equity firm might hold a portfolio company at cost, even as its market value soars, because GAAP prohibits upward revaluation unless the asset is sold. This creates a timing mismatch: GAAP net worth lags behind economic performance until transactions occur. For individuals, the problem is simpler but no less critical—GAAP forces a binary choice: assets must be either held for trading (marked to market) or held for long-term use (carried at historical cost). The latter dominates for most investors, skewing reported net worth downward.The Context You Need
GAAP’s origins lie in the Securities Act of 1933, which demanded standardized financial reporting to curb fraud. Over time, its principles seeped into private-sector accounting, especially for entities with public exposure. Today, the calculation of net worth using GAAP is non-negotiable for: - Publicly traded companies (SEC filings mandate GAAP compliance). - Private businesses with audited financials (banks, investors, or acquirers may demand GAAP-adjusted figures). - High-net-worth individuals with business interests (e.g., family offices, where personal and corporate net worth intersect). The key distinction: GAAP net worth is not a liquidity measure. It’s a regulatory construct that prioritizes verifiability over realizability. A hedge fund’s GAAP net worth might exclude unrealized gains on illiquid assets, while a private equity portfolio’s value could be distorted by impairment rules—even if the underlying assets are thriving.The Mechanics
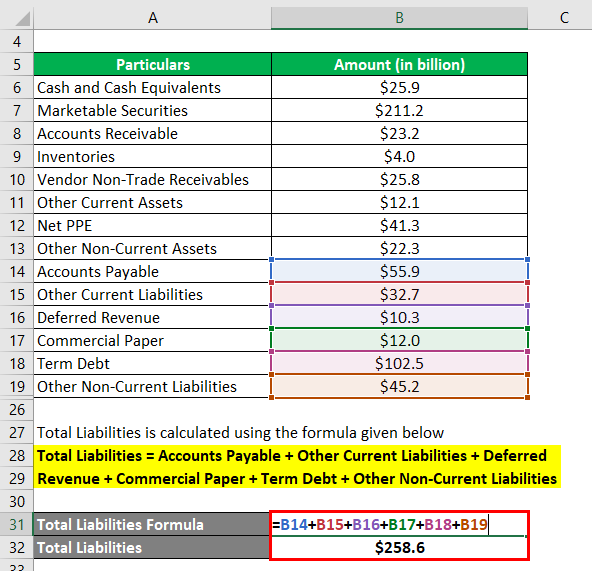
At its core, the calculation of net worth using GAAP follows this sequence: 1. Start with the balance sheet’s shareholders’ equity (Assets – Liabilities). 2. Adjust for off-balance-sheet items: - Deferred tax liabilities (future tax obligations from timing differences). - Contingent liabilities (e.g., warranties, legal claims). - Non-controlling interests (minority shareholders’ claims in subsidiaries). 3. Reclassify assets per GAAP’s hierarchy: - Current assets (cash, receivables) are marked at fair value. - Long-term assets (property, equipment) are carried at cost minus accumulated depreciation/amortization, unless impaired. - Investments (e.g., private equity stakes) are marked to market only if held for trading; otherwise, they’re carried at cost. 4. Apply industry-specific rules: - Financial institutions must use mark-to-market for securities. - Manufacturers may face lower-of-cost-or-market tests for inventory. - Tech firms often grapple with goodwill impairment, which can wipe out reported equity overnight. The result is a net worth figure that’s audit-proof but not necessarily wealth-reflective. For example, a biotech company with a $200M patent (carried at cost) might see its GAAP net worth plummet if the patent fails an impairment test—even if the patent’s market value hasn’t changed.Details That Change the Picture
GAAP’s rigidity introduces three critical distortions in net worth calculations: 1. Conservatism bias: Assets are understated (e.g., goodwill amortization), while liabilities are overstated (e.g., deferred taxes). This creates a buffer against overvaluation but obscures true economic worth. 2. Timing arbitrage: Unrealized gains on long-term assets (e.g., private equity) are excluded until sold, creating a lag between GAAP net worth and market reality. 3. Entity-specific quirks: A real estate developer’s GAAP net worth might exclude land held for future projects (carried at cost), while a retailer’s inventory is marked to the lower of cost or net realizable value—regardless of market demand. These rules matter most when comparing GAAP net worth across entities. A tech startup with no revenue might show negative GAAP net worth due to R&D expenses, while a mature manufacturer with the same cash flow could appear solvent. The calculation isn’t about fairness; it’s about standardization."GAAP net worth is a regulatory fiction—a necessary evil to ensure comparability, but one that bears little relation to economic substance." — Former SEC Chief Accountant, 2018
| Scenario | GAAP Net Worth Impact |
|---|---|
| Private equity stake held >1 year | Carried at cost; unrealized gains ignored until sale. |
| Goodwill impairment test fails | Shareholders’ equity drops by impairment charge (e.g., $50M write-down). |
| Deferred tax liability recognized | Liabilities increase; net worth declines (even if no cash outflow). |
| Hedge fund marks securities to market | Net worth fluctuates daily with market prices. |
| Family office holds real estate at cost | GAAP net worth understates appreciation until sold. |
Conclusion
The calculation of net worth using GAAP is less about personal wealth and more about financial governance. It’s the framework that ensures a publicly traded company’s balance sheet tells a consistent story—even if that story doesn’t match its private market value. For individuals, the rules become relevant when business ownership is involved, forcing a choice between GAAP’s conservatism and a more flexible (but less auditable) approach. The trade-off is clear: GAAP net worth sacrifices precision for standardization. It’s the price of trust in financial markets, where comparability outweighs individual circumstances. Yet for those who navigate both personal and corporate finance, understanding these rules isn’t optional—it’s essential to avoid missteps in valuation, taxation, or stakeholder communications.Comprehensive FAQs
Q: Can I use GAAP to calculate my personal net worth?
A: Only if you’re treating personal assets as a business entity (e.g., a family office with audited financials). For individuals, GAAP is overkill—unless you’re reporting to investors or lenders who demand it. Most personal net worth calculations use fair market value, not GAAP’s cost-based rules.
Q: How does GAAP handle cryptocurrency in net worth calculations?
A: Cryptocurrency held as a trading asset (bought/sold frequently) must be marked to market. If held as a long-term investment, it’s carried at cost—unless impaired. Public companies must disclose crypto holdings in footnotes, but private individuals have flexibility.
Q: Why does GAAP net worth differ from "book value"?
A: Book value is simply shareholders’ equity (Assets – Liabilities) from the balance sheet. GAAP net worth adjusts for off-balance-sheet items (e.g., deferred taxes, contingencies) and reclassifications (e.g., marking assets to market). The two can diverge significantly for companies with complex liabilities.
Q: Does GAAP allow for "soft" assets like brand value?
A: Only if they’re acquired and separately identifiable (e.g., a purchased trademark). Internally generated goodwill (e.g., a startup’s brand) isn’t recognized until the entity is sold, at which point it may be recorded as goodwill—subject to annual impairment tests.
Q: How often should GAAP net worth be recalculated?
A: Annually for audited financials (e.g., public companies). Private entities may recalculate quarterly if they have marked-to-market assets (e.g., hedge funds). For individuals, recalculations are ad-hoc unless tied to tax or investment reporting.
