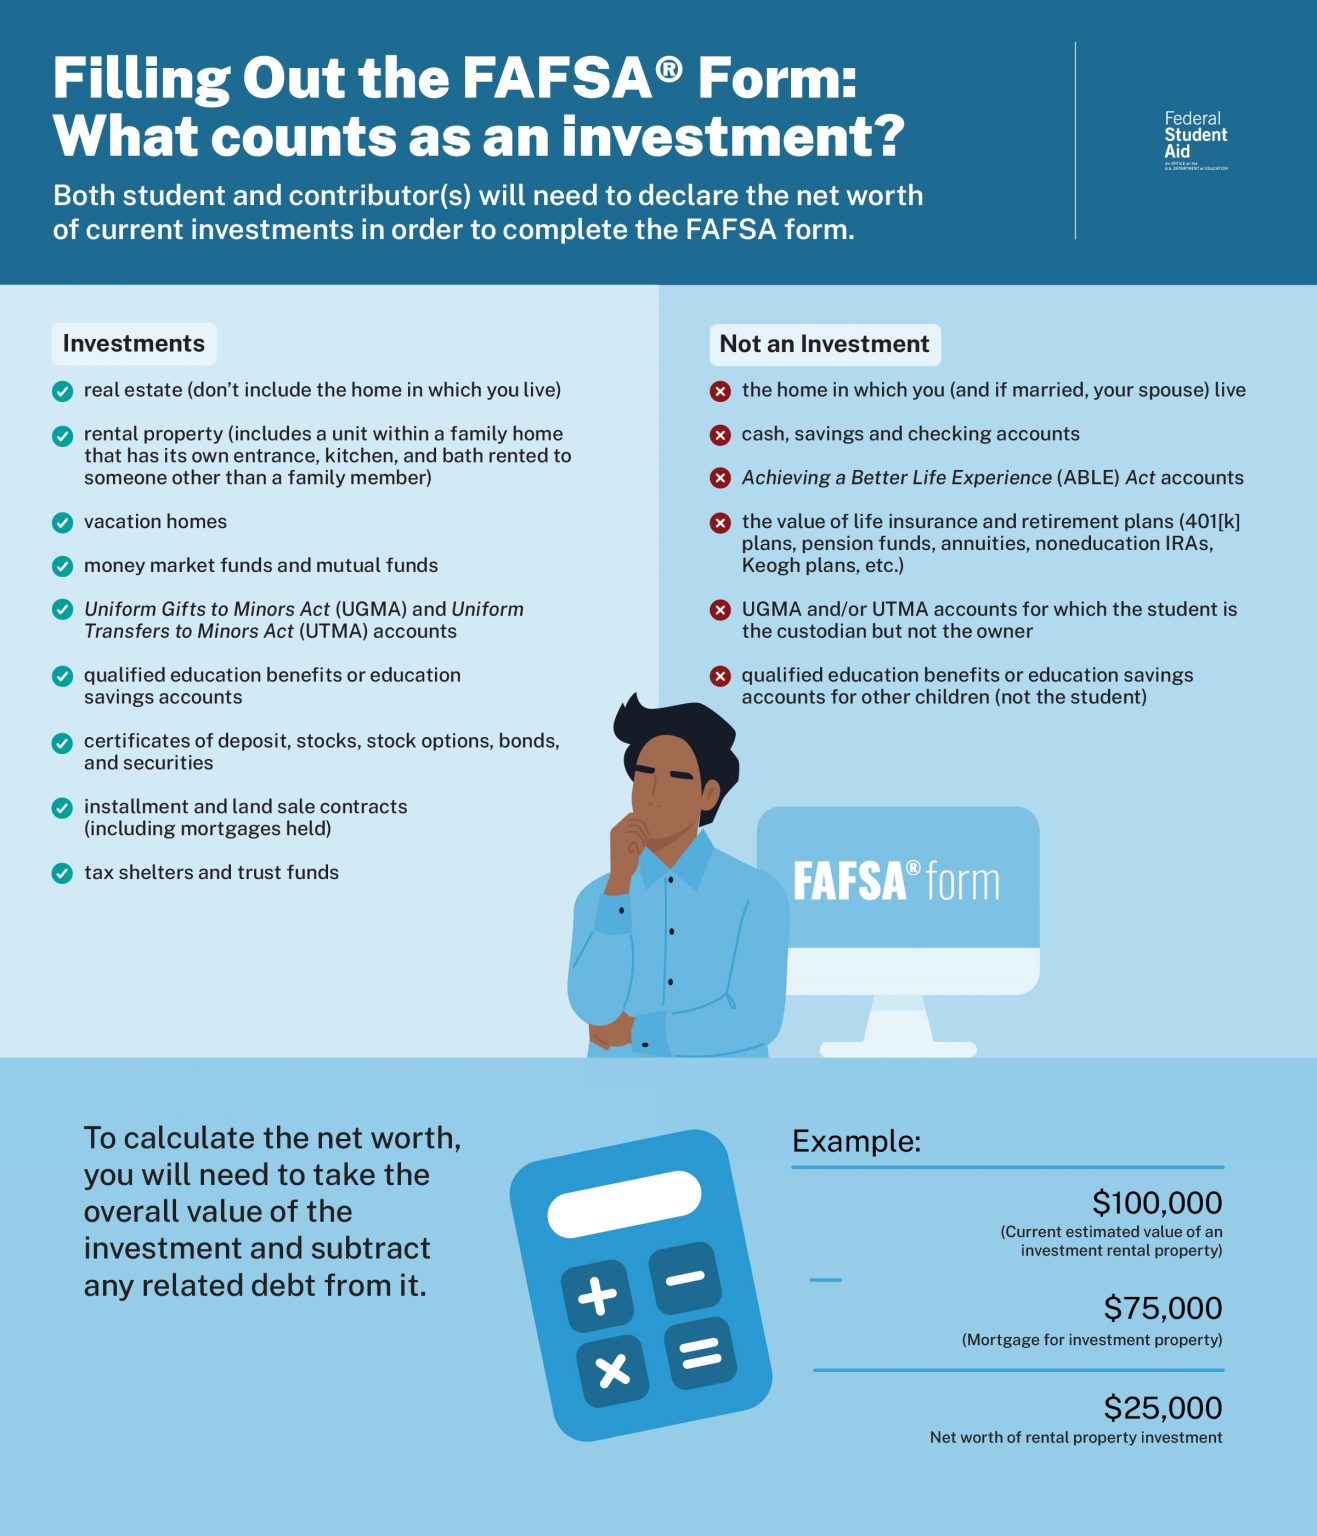
6 Things Worth Knowing About FAFSA Parents’ Net Worth of Current Investments
The FAFSA’s asset rules are designed to estimate a family’s ability to pay for college, but the reality is that parents’ net worth of current investments is treated as a monolithic block—until it isn’t. Six key dynamics explain why the way assets are held can alter aid eligibility as much as their total value.1. The FAFSA’s Asset Hierarchy: What Counts (and What Doesn’t)
Not all investments are created equal in the eyes of the FAFSA. The formula distinguishes between "countable" and "non-countable" assets, but the distinctions often defy intuition. Parents’ net worth of current investments in taxable brokerage accounts, for example, is assessed at 100% of its value, while assets in a 529 college savings plan are treated more favorably—though not always as favorably as parents assume. Retirement accounts like IRAs and 401(k)s are generally excluded from the EFC calculation, but only if they’re held by the parent (not the student) and remain untouched. The catch? Early withdrawals to pay tuition can trigger penalties and taxable distributions, turning a "non-countable" asset into a liability overnight. The FAFSA’s asset protection rules also create perverse incentives. A parent might be advised to max out a Roth IRA to avoid Required Minimum Distributions (RMDs) in retirement, only to discover that the IRA’s growth is shielded from the EFC calculation—while the same funds in a taxable account would have been fully assessed. This isn’t just about numbers; it’s about how parents’ investment strategies must adapt to the FAFSA’s arbitrary bright lines. For instance, a family with $500,000 in a brokerage account might see their EFC rise by $20,000 or more, while an identical sum in a 529 plan could reduce it—or even eliminate it, depending on the state’s matching programs.2. Liquidity Matters More Than You Think
The FAFSA’s formulas assume that all countable assets are equally accessible, but in practice, parents’ net worth of current investments tied up in illiquid assets—such as private business interests, real estate, or restricted stock—can be treated with more flexibility. The formula allows for a "business net worth exclusion" if the asset is significant and the parent can demonstrate that selling it would disrupt operations. However, the threshold for this exclusion is steep: the business must employ at least 100 full-time employees or generate at least $150,000 in annual revenue. For most families, this means that illiquid assets are still counted—just with a delay. The FAFSA assumes parents can liquidate 50% of their non-retirement investments over five years, but in reality, selling a rental property or harvesting a private equity stake takes longer, often with tax consequences. The liquidity rule also explains why some parents rush to rebalance their portfolios before filing. A family with $1 million in a mix of cash, stocks, and bonds might strategically shift funds into a 529 plan or a non-retirement account with lower assessed value, knowing that the FAFSA’s liquidity assumption will treat the remaining assets as less immediately available. This tactic isn’t about hiding wealth; it’s about optimizing the presentation of parents’ net worth of current investments to match the FAFSA’s outdated liquidity models.3. The Retirement Account Loophole (and Its Limits)
Retirement accounts are the FAFSA’s most generous exclusion, but the rules are riddled with exceptions. Parents’ net worth of current investments in traditional IRAs or 401(k)s is ignored unless the parent (or student) takes early distributions to pay for college. Even then, the penalty-free withdrawal rules for education expenses apply only to IRAs—not 401(k)s—adding another layer of complexity. The result? A parent with $1 million in a 401(k) might see no impact on their EFC, while a parent with the same sum in an IRA could face penalties if they withdraw funds before age 59½, even for education. The loophole narrows further for parents who are self-employed or own small businesses. Contributions to Solo 401(k)s or SEP IRAs are treated like any other retirement account, but the FAFSA’s asset rules don’t distinguish between pre-tax and Roth contributions. This means a parent could have $500,000 in a Roth IRA (countable only if withdrawn) and $500,000 in a traditional IRA (fully excluded), yet the FAFSA’s formulas would treat both as identical in terms of liquidity and accessibility. The takeaway? Parents’ net worth of current investments in retirement accounts is a double-edged sword: it’s shielded from the EFC calculation, but accessing it for college can trigger tax bombs.4. The 529 Plan Paradox: A Tool That Can Backfire
529 plans are marketed as the gold standard for college savings, but their impact on the FAFSA depends on ownership. If a parent owns the 529 plan, its assets are counted as a parental asset—meaning only 5.64% of the balance is assessed toward the EFC (a rule that dates back to the 1992 FAFSA overhaul). However, if the student or a grandparent owns the plan, the full balance is counted. This creates a perverse incentive: a grandparent gifting $50,000 to a 529 plan could increase the student’s EFC by the entire amount, while a parent contributing the same sum would see minimal impact. The 529 plan’s treatment also varies by state. Some states, like California and New York, offer tax deductions for contributions, while others, like Texas, do not. A family in a high-tax state might prioritize 529 contributions to reduce state income taxes, only to find that the FAFSA’s asset rules negate some of those savings. The paradox deepens when parents consider that 529 plans are subject to market risk—unlike scholarships or grants, which don’t fluctuate with the S&P 500. A family with a 529 plan worth $100,000 one year might see its value drop to $80,000 the next, yet the FAFSA’s formulas still assess the higher balance if it was reported in a prior year.5. Home Equity: The Asset That’s Both Visible and Invisible
Home equity is one of the most misunderstood components of parents’ net worth of current investments when it comes to the FAFSA. The formula excludes the primary residence’s value entirely, but only if it’s the family’s primary home and the equity is below a certain threshold. For most families, this means the home’s value doesn’t factor into the EFC—unless the family owns multiple properties. A second home or rental property, however, is treated as an investment asset and assessed at full value. This creates a scenario where a family with a $1 million primary home and a $500,000 rental property might see the rental’s value counted toward their EFC, while the primary home’s equity is ignored. The home equity exclusion also interacts poorly with reverse mortgages. A parent who takes out a reverse mortgage to supplement retirement income might see their home’s value decline, but the FAFSA’s formulas don’t account for the reduced equity in real time. Instead, the home’s original appraised value is used, leading to an overestimation of liquidity. For families nearing retirement, this can create a Catch-22: tapping home equity to cover college costs might increase the EFC by reducing other liquid assets, while leaving the home untouched could mean missing out on aid due to overstated equity.6. The "Asset Protection" Myth: Why Some Strategies Don’t Work
Many parents assume that moving assets into trusts, LLCs, or offshore accounts can shield them from the FAFSA’s scrutiny. In reality, the FAFSA’s asset rules are designed to penetrate these structures. Parents’ net worth of current investments held in revocable trusts are counted as parental assets, while irrevocable trusts may be excluded—but only if the parent has no control over the assets. This means that a parent who sets up a trust to reduce their EFC could still be penalized if they retain any influence over the funds. Similarly, offshore accounts are treated as countable assets unless they’re held in a qualifying foreign trust, which requires complex legal structuring and ongoing compliance. The myth of asset protection extends to life insurance policies. Permanent life insurance with a cash value is counted as an asset if the policy’s cash value exceeds the total premiums paid. Term life insurance, however, is excluded. This creates a scenario where a parent might be advised to convert term policies to whole life for estate planning, only to discover that the cash value is now subject to the FAFSA’s asset rules. The lesson? Parents’ net worth of current investments can’t be hidden from the FAFSA’s formulas—only restructured within the system’s narrow parameters.
How These Facts Connect
The FAFSA’s treatment of parents’ net worth of current investments isn’t just about numbers; it’s about forcing families into a financial contortionist’s act. The system’s rigid asset classifications—where retirement accounts are sacred, 529 plans are conditional, and home equity is both visible and invisible—create a patchwork of rules that prioritize simplicity over fairness. The result is a process where financial planning for college aid becomes an exercise in navigating arbitrary bright lines, rather than optimizing for long-term wealth. What emerges is a paradox: the FAFSA’s formulas are designed to estimate a family’s ability to pay, but the way they treat parents’ net worth of current investments often punishes families for making sound financial decisions. A parent who diversifies into real estate or private equity might see their EFC rise, while another who hoards cash in a brokerage account could benefit from the FAFSA’s liquidity assumptions. The system’s lack of flexibility means that families with identical incomes can end up with vastly different aid packages, all because of how their assets are structured. The FAFSA doesn’t just calculate need; it rewards certain types of wealth and penalizes others, often without clear justification. | Asset Type | FAFSA Treatment | Key Consideration | Example Impact | |------------------------------|-----------------------------------------------|-----------------------------------------------|----------------------------------------| | Taxable brokerage accounts | 100% of value counted | High liquidity assumption | $1M account → ~$20K+ EFC increase | | 529 college savings plans | 5.64% of value counted (parent-owned) | State tax benefits vs. FAFSA assessment | $50K plan → ~$2.8K EFC impact | | Retirement accounts (IRA/401k)| Excluded unless withdrawn early | Penalty risks for education withdrawals | $500K IRA → $0 EFC (but tax hit if withdrawn) | | Primary home equity | Excluded (up to appraised value) | Secondary homes counted fully | $1M home + $500K rental → rental counted | | Private business interests | Partial exclusion if meets revenue/employee thresholds | Illiquidity doesn’t always reduce EFC | $300K business → may still be assessed |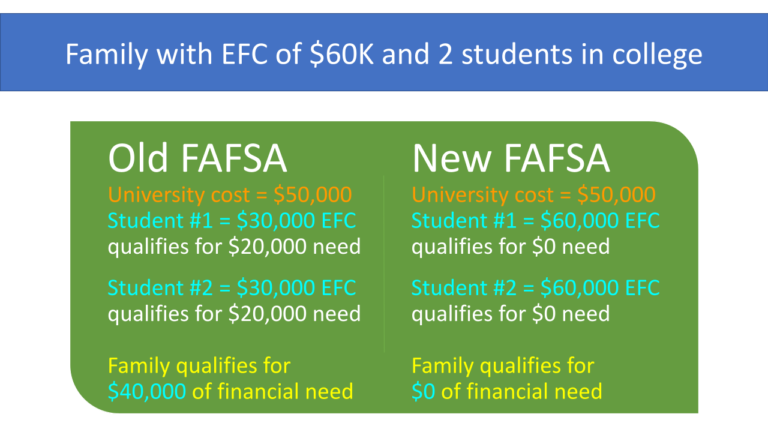
Conclusion
The FAFSA’s net worth rules are a relic of a simpler financial landscape, where most families had modest investments and liquidity was less of a concern. Today, parents’ net worth of current investments spans from 401(k)s to private equity, and the FAFSA’s one-size-fits-all approach fails to account for the realities of modern wealth. The system’s rigid asset classifications force families into a game of financial whack-a-mole, where every adjustment—whether shifting funds into a 529 plan or taking a reverse mortgage—has unintended consequences for aid eligibility. The irony is that the FAFSA’s formulas are supposed to ensure that aid goes to those who need it most, yet they often achieve the opposite by penalizing families for making prudent financial moves. Parents who follow standard advice—diversifying investments, maximizing retirement contributions, or leveraging home equity—can find themselves at a disadvantage when it comes to college funding. The solution isn’t to game the system but to understand its quirks and plan accordingly. For families navigating this landscape, the key is to align their investment strategies with the FAFSA’s arbitrary rules—not the other way around.Comprehensive FAQs
Q: Does the FAFSA count my parents’ investments in a non-retirement brokerage account fully?
A: Yes. The FAFSA assesses parents’ net worth of current investments in taxable brokerage accounts at 100% of their value, with no exclusions. This includes stocks, bonds, mutual funds, and other liquid assets. The formula assumes parents can access 50% of these assets over five years, which is why aggressive rebalancing before filing can sometimes lower the Expected Family Contribution (EFC).
Q: Are assets in a 529 plan counted differently if my parents own it vs. a grandparent?
A: Absolutely. If parents’ net worth of current investments includes a 529 plan they own, only 5.64% of the balance is counted toward the EFC. However, if a grandparent owns the plan, the full balance is assessed. This creates a significant incentive for parents to own the account themselves, even if it means sacrificing some state tax benefits or flexibility in contributions.
Q: Can I exclude my parents’ home equity from the FAFSA entirely?
A: Only if it’s their primary residence and they meet the FAFSA’s asset protection rules. The value of the home itself is excluded, but any equity above the home’s appraised value (or if it’s a secondary property) is counted. Additionally, if your parents take out a reverse mortgage or have a high-equity home, the FAFSA may still assess liquidity based on the home’s original value, not its current market worth.
Q: Will withdrawing from a retirement account to pay for college affect my parents’ FAFSA eligibility?
A: It depends. Parents’ net worth of current investments in traditional IRAs or 401(k)s are excluded from the EFC calculation, but withdrawing early for education expenses can trigger penalties and taxable distributions. For IRAs, penalty-free withdrawals are allowed under the "qualified education expense" rule, but 401(k)s don’t offer the same flexibility. The key is to avoid reducing retirement savings unnecessarily, as the FAFSA’s formulas don’t account for the long-term impact of early withdrawals.
Q: Does the FAFSA treat private business assets differently from public stocks?
A: Yes, but with caveats. The FAFSA allows for a partial exclusion of private business assets if the business meets specific revenue or employee thresholds (e.g., $150,000+ in annual revenue or 100+ full-time employees). However, even if excluded, the business’s value is still considered in the EFC calculation over time, assuming liquidity. Public stocks, by contrast, are fully assessed immediately because they’re considered highly liquid.
Q: Can trusts or LLCs protect my parents’ investments from the FAFSA?
A: Generally, no. The FAFSA’s asset rules are designed to penetrate most legal structures. Parents’ net worth of current investments held in revocable trusts are counted as parental assets, while irrevocable trusts may be excluded—but only if the parent has no control over the funds. Offshore accounts are also counted unless held in a qualifying foreign trust, which requires complex compliance. The takeaway: trusts and LLCs offer little protection against the FAFSA’s asset rules.
Q: How does the FAFSA’s liquidity assumption affect my parents’ investment strategy?
A: The FAFSA assumes parents can liquidate 50% of their non-retirement investments over five years, which means holding cash or highly liquid assets can inflate the EFC. To mitigate this, some families rebalance portfolios before filing—shifting funds into 529 plans or other assets assessed at lower rates. However, this strategy requires careful timing, as market fluctuations can alter the assessed value. The goal isn’t to hide wealth but to optimize the presentation of parents’ net worth of current investments within the FAFSA’s outdated liquidity models.
Q: Are there any assets the FAFSA never counts, regardless of value?
A: Yes, but with strict conditions. Parents’ net worth of current investments in the following are generally excluded: the family’s primary home (up to its appraised value), retirement accounts (if not withdrawn early), and certain life insurance policies (if the cash value doesn’t exceed total premiums paid). However, exceptions apply—such as secondary homes or early withdrawals from retirement accounts—which can turn excluded assets into countable liabilities.
