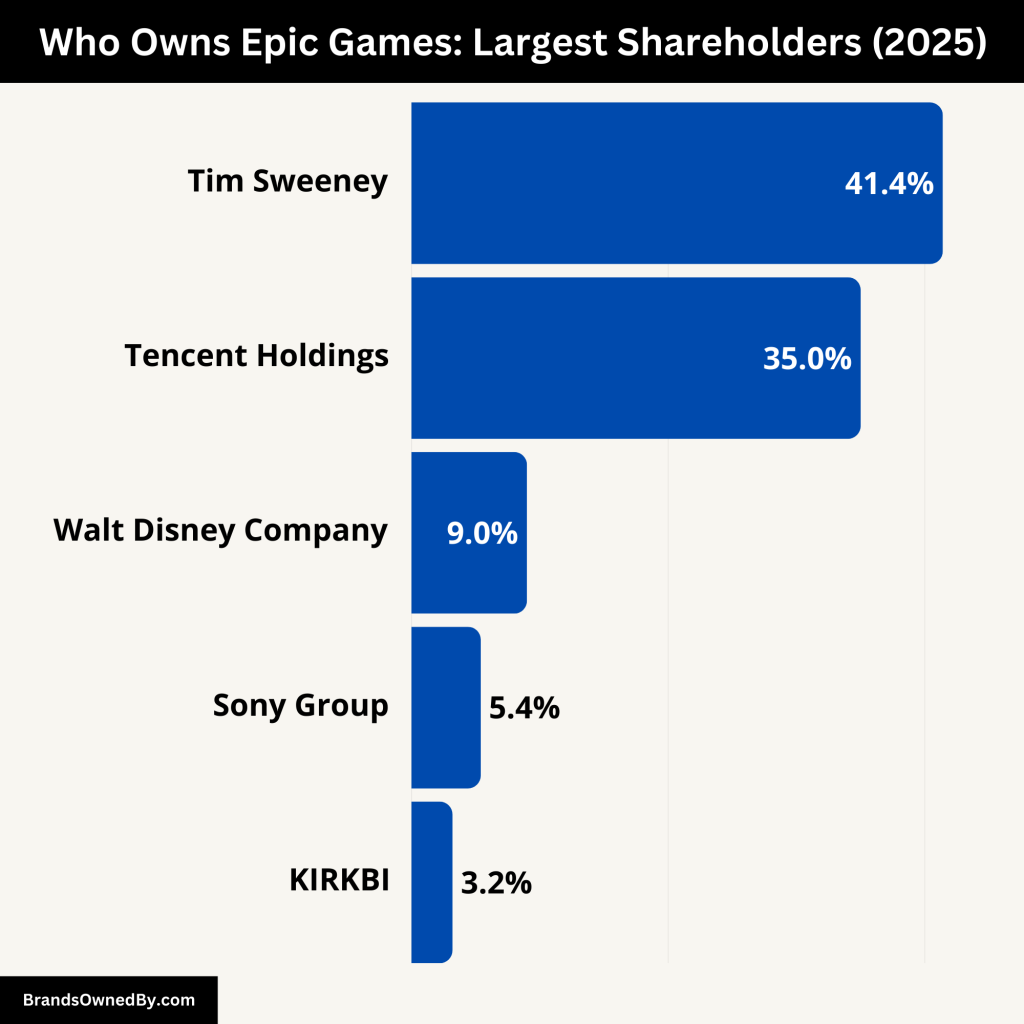
Common Myths About Epic Games’ Financial Dominance
The first myth is that Epic’s valuation is solely tied to Fortnite’s revenue. While the battle royale phenomenon undeniably drives a significant portion of its income—generating billions annually—Epic’s financial health isn’t monolithic. The company’s diversification into Unreal Engine, cloud gaming (via Epic Games Store), and even film production (through its acquisition of Skydance Interactive) spreads risk. Yet, the narrative often collapses these ventures into a single Fortnite-centric story, ignoring how Unreal Engine’s licensing and tools contribute to steady, long-term revenue streams. The second misconception is that Epic’s high net worth is purely a result of traditional gaming metrics. In reality, its valuation is inflated by speculative private-market valuations (peaking at $31.5 billion in 2021 before corrections) and its aggressive use of debt to fuel expansion. These factors are rarely discussed in mainstream analyses, which tend to focus on surface-level revenue figures. Another persistent myth is that Epic’s legal battles—most notably its antitrust lawsuit against Apple and Google—are purely altruistic. While the company framed its lawsuit as a fight for developers, the financial stakes were undeniable: Epic’s direct payment model (cutting out middlemen) was a direct threat to Apple’s App Store dominance. The settlement, which included a $400 million fund for developers and a 15% commission for apps over $1 million, was a strategic move to solidify Epic’s position as a payments processor in gaming. Critics argue this was less about fairness and more about Epic positioning itself as an alternative to Apple’s ecosystem—a gambit that paid off in visibility and market share, even if the long-term financial impact remains debated.Myth 1: Epic’s valuation is stable and predictable
Private-market valuations are notoriously volatile, and Epic’s is no exception. The company’s valuation has swung dramatically: from a high of $31.5 billion in 2021 (post-Fortnite boom and pre-IPO rumors) to a more conservative $15–$18 billion range in recent years, as growth slowed and investor sentiment shifted. This isn’t just about revenue—it’s about perception. When Epic announced its Unreal Engine 5 launch in 2021, its valuation spiked temporarily, but the effect was short-lived. The reality is that private valuations are often driven by hype cycles, not fundamentals. For instance, Epic’s 2023 funding round at a lower valuation didn’t reflect a decline in revenue but rather a recalibration of expectations in a tighter market. The lesson? Epic games net worth ranking high isn’t a fixed number—it’s a moving target influenced by external factors like regulatory wins, new product launches, and even macroeconomic trends. What’s often overlooked is how Epic’s financials are tied to its aggressive (and sometimes risky) expansion. The company’s $1.8 billion acquisition of Skydance Interactive in 2022, for example, was framed as a diversification play into film and TV—but it also diluted Epic’s focus on core gaming revenue. Meanwhile, its foray into blockchain via NFTs (like the Fortnite skins debacle) drew regulatory scrutiny and alienated some investors. These moves aren’t just operational; they’re bets on future growth, and their success isn’t guaranteed. The valuation isn’t just about current profits but about projected potential—something that’s hard to pin down in a company that reinvests heavily into unproven ventures.Myth 2: Fortnite is the sole driver of Epic’s financial success
Fortnite is undeniably Epic’s cash cow, but it’s not the only engine. Unreal Engine, the company’s 3D creation tool, generates hundreds of millions annually through licensing, subscriptions, and marketplace sales. In 2022, Epic reported that Unreal Engine’s revenue exceeded $1 billion for the first time, a figure that doesn’t get enough attention in discussions about Epic games net worth ranking high. The tool’s adoption in industries beyond gaming—automotive, film, architecture—provides a steady income stream that’s less cyclical than Fortnite’s seasonal updates. Then there’s the Epic Games Store, which, despite its controversial launch (and the subsequent Apple lawsuit), has carved out a niche in PC gaming with a revenue-sharing model that competes directly with Steam. The mistake is treating Fortnite as Epic’s only asset. The company’s financial resilience comes from its ability to pivot. When Fortnite’s growth plateaued in 2022–2023, Epic doubled down on Unreal Engine’s enterprise applications and expanded its cloud gaming infrastructure. Even its failed experiments—like the Epic MegaGrants program, which saw a fraction of the expected developer adoption—provided valuable data for future strategies. The reality is that Epic’s net worth isn’t a single-peaked graph tied to one product; it’s a portfolio play where each segment reinforces the others.Myth 3: Epic’s high valuation is purely organic
Epic’s financial trajectory has been fueled by debt, not just organic growth. The company’s aggressive use of leverage—including a $1 billion credit facility in 2021—allowed it to make high-risk acquisitions and fund expansion during a period of high valuation. This isn’t unusual in tech, but it’s rarely acknowledged in discussions about Epic games net worth ranking high. The Skydance deal, for instance, was financed partly through debt, a move that increased Epic’s liabilities but also its potential upside if the media division succeeds. Similarly, its investment in cloud gaming infrastructure required significant upfront capital, much of which was borrowed. The other factor is Epic’s relationship with investors. The company has historically been private, which means its valuation is determined by a small group of stakeholders rather than public market forces. This lack of transparency creates room for speculation. When Epic raised $1 billion in 2022 at a lower valuation, it wasn’t a sign of weakness but a recalibration—one that allowed it to avoid a dilution-heavy public offering. The message was clear: Epic would grow on its own terms, even if it meant operating with more debt. For a company often portrayed as a scrappy underdog, its financial strategy is anything but.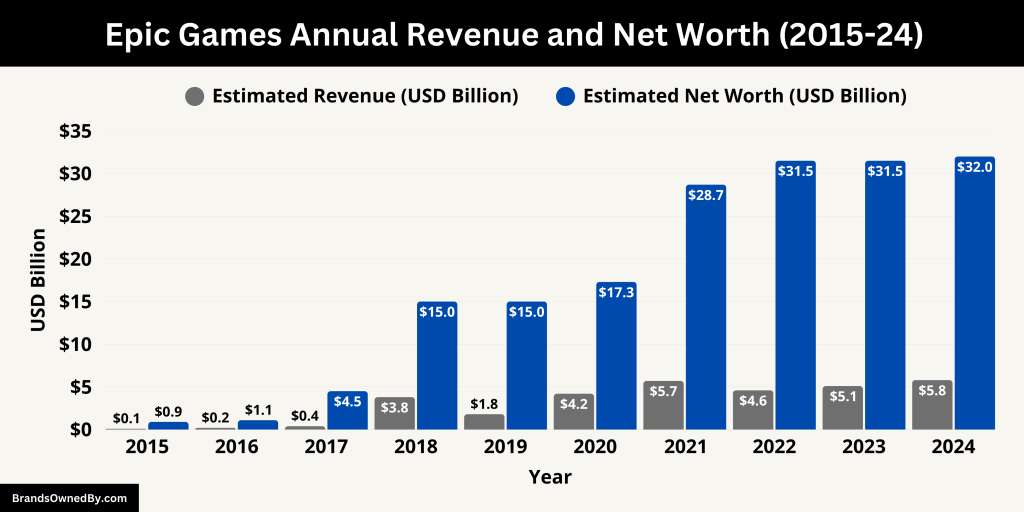
What Holds Up to Scrutiny
At its core, Epic’s financial dominance rests on three pillars: Fortnite’s unmatched cultural and commercial reach, Unreal Engine’s enterprise-grade utility, and a relentless focus on direct consumer relationships. Fortnite isn’t just a game—it’s a platform that generates ancillary revenue through microtransactions, cross-promotions, and even real-world events (like the virtual Fortnite concert with Travis Scott). The game’s ability to adapt—from battle royale to creative modes, concerts, and even film tie-ins—keeps it relevant in a market where player fatigue is a constant threat. Meanwhile, Unreal Engine’s adoption in industries beyond gaming (think automotive simulations or virtual production in Hollywood) provides a countercyclical revenue stream. When Fortnite’s growth slows, Unreal Engine’s enterprise deals can offset some of the volatility. The third pillar is Epic’s control over its distribution. By bypassing traditional retailers and selling directly to consumers (via its store or Fortnite’s in-game marketplace), Epic captures a larger share of each dollar spent. This model isn’t just about margins—it’s about data. Epic’s direct relationship with players gives it unparalleled insights into consumer behavior, which it leverages to refine monetization strategies. The company’s willingness to take risks—like its early bet on live-service games or its legal battle with Apple—has paid off in brand recognition and market share, even if the financial returns aren’t always immediate.“Epic’s valuation isn’t just about games—it’s about controlling the entire pipeline, from creation to consumption. That’s why their net worth isn’t just high; it’s structurally defensible.” — Industry analyst, 2023
| Common Belief | What the Evidence Says |
|---|---|
| Epic’s valuation is solely tied to Fortnite. | Unreal Engine and the Epic Games Store contribute meaningfully to long-term revenue. |
| Epic’s high net worth is stable. | Private valuations fluctuate based on market sentiment, debt levels, and strategic bets. |
| Epic’s growth is purely organic. | Debt-fueled acquisitions and investor funding play a significant role in expansion. |
| Epic’s legal battles hurt its finances. | Regulatory wins (e.g., Apple settlement) enhanced its brand as a developer-friendly alternative. |
Why the Confusion Persists
Part of the confusion stems from Epic’s dual identity: it’s both a gaming company and a tech platform. This blur creates ambiguity in how its financials are interpreted. To traditional gaming analysts, Epic is a publisher with a hit franchise. To tech investors, it’s a payments processor and cloud infrastructure provider. Reconciling these perspectives is difficult, especially when Epic itself resists clear categorization. The company’s refusal to go public until it’s ready (despite years of speculation) only adds to the mystery. Private valuations are opaque by nature, and Epic’s aggressive reinvestment strategy means profits aren’t always visible on a balance sheet. Another factor is the speed of Epic’s evolution. The company that started with Gears of War and Unreal Engine has transformed into a media conglomerate with fingers in gaming, film, and even metaverse-adjacent ventures. Keeping up with its pivots—from NFTs to AI tools in Unreal Engine—requires constant recalibration of expectations. Investors and analysts are often playing catch-up, leading to a lag between Epic’s actual performance and public perception. The result? A narrative that’s more about potential than proven returns, where epic games net worth ranking high is less about today’s profits and more about tomorrow’s possibilities.
Conclusion
Epic Games’ financial ascent isn’t just about hitting a high valuation—it’s about redefining what a gaming company can be. The company’s ability to leverage Fortnite’s cultural dominance, Unreal Engine’s enterprise potential, and its direct-to-consumer model has created a financial ecosystem that’s both resilient and adaptable. Yet, the focus on epic games net worth ranking high often overshadows the risks: debt levels, regulatory uncertainties, and the challenge of sustaining growth in a maturing market. Epic’s story isn’t just about money—it’s about power. Power over distribution, over developer relationships, and over the narrative of what gaming can achieve in the digital economy. The confusion around Epic’s finances will persist as long as the company continues to blur the lines between gaming, tech, and media. But one thing is clear: Epic didn’t just climb the ranks—it redrew the map. Whether its net worth stays high depends on whether it can keep innovating, keep its investors patient, and keep its competitors guessing.Comprehensive FAQs
Q: How does Epic’s valuation compare to other gaming companies?
A: Epic’s private-market valuation has historically outpaced many public gaming peers, though exact comparisons are tricky due to its private status. For context, Take-Two Interactive (publisher of Grand Theft Auto) has a market cap around $20–25 billion, while Activision Blizzard’s pre-merger valuation was similar. Epic’s peak private valuation ($31.5 billion in 2021) briefly surpassed both, but recent corrections have narrowed the gap. The key difference is Epic’s lack of public scrutiny—its valuation is influenced by a smaller pool of investors and strategic bets rather than quarterly earnings reports.
Q: Is Epic’s revenue primarily from Fortnite, or are other products contributing?
A: While Fortnite remains Epic’s largest revenue driver—generating an estimated $5–6 billion annually at its peak—other segments play critical roles. Unreal Engine’s revenue exceeded $1 billion in 2022, and the Epic Games Store (despite its smaller user base) captures a growing share of PC gaming sales. Even smaller ventures, like the Rocket Racing esports league or experimental projects (e.g., The Matrix Awakens), contribute to brand diversification. The mistake is assuming Fortnite is the only engine; Epic’s financial health is a composite of multiple, albeit unevenly weighted, revenue streams.
Q: Why did Epic’s valuation drop after its 2022 funding round?
A: The valuation adjustment reflected a combination of market conditions and Epic’s strategic recalibration. Gaming valuations broadly softened in 2022–2023 as investor sentiment shifted from growth-at-all-costs to profitability. Epic’s decision to raise funds at a lower valuation ($15–$18 billion range) was a pragmatic move to avoid dilution in a tighter funding environment. Additionally, Fortnite’s growth had slowed, and the company’s high-profile bets (like Skydance) required time to yield returns. The drop wasn’t a failure—it was a reset, signaling Epic’s willingness to prioritize control over rapid expansion.
Q: How does Epic’s direct payment model (bypassing Apple/Google) affect its net worth?
A: Epic’s legal battle with Apple and Google wasn’t just about fees—it was about positioning itself as an alternative payments processor in gaming. The settlement (including a 15% commission for large apps) gave Epic a foothold in a lucrative space, potentially increasing its long-term revenue from transactions. However, the immediate financial impact is mixed: while Epic captures more per sale, it also bears more risk (e.g., fraud, chargebacks). The bigger play is strategic—Epic’s model reduces dependency on third-party stores, giving it more control over monetization and user data, which indirectly supports its net worth by improving margins and retention.
Q: Are there risks to Epic’s high net worth that aren’t widely discussed?
A: Yes. Beyond the obvious—market saturation for Fortnite or regulatory backlash—Epic faces less-discussed risks like talent retention (key executives have left amid rapid scaling) and the challenge of monetizing Unreal Engine’s enterprise growth without alienating its creative user base. Another risk is its reliance on live-service games, which require constant content updates to retain players—a model that’s capital-intensive and prone to burnout. Additionally, Epic’s aggressive debt usage could become a liability if growth stalls, forcing it to refinance at higher rates. The company’s financial strength is a double-edged sword: it enables bold moves but also magnifies downside risks.
Q: Could Epic’s net worth be higher if it went public?
A: Possibly, but not necessarily. Public markets often inflate valuations based on hype, but they also introduce volatility and short-term pressure. Epic’s private status allows it to focus on long-term plays (like Unreal Engine or cloud gaming) without quarterly earnings scrutiny. That said, a public offering could unlock more capital for acquisitions or R&D, potentially accelerating growth. However, Epic’s current strategy—controlling its own narrative and avoiding dilution—has served it well so far. The trade-off is liquidity for investors versus flexibility for Epic, and the company has shown no urgency to change that dynamic.
Q: What’s the most underrated factor in Epic’s financial success?
A: Its ability to turn controversy into leverage. From the Apple lawsuit to its NFT experiments, Epic has repeatedly used public friction to reinforce its brand as a disruptor. The Apple case, for example, positioned Epic as a developer advocate, even though the financial stakes were clear. This narrative stickiness has helped it attract talent, retain users, and justify high valuations in a crowded market. It’s not just about the money—it’s about the perception of being the underdog that’s reshaping an industry, which in turn supports its net worth by making it an attractive partner for developers, investors, and even competitors.
