
Where It All Began
Jeffrey Skilling’s story starts in the 1970s, when he was a young analyst at the accounting firm KPMG, where he developed a reputation for spotting financial trends before anyone else. His early career was marked by a relentless focus on data—less on human intuition, more on cold, hard metrics. By the time he joined Enron in 1990, he had already made a name for himself as a turnaround specialist, helping companies streamline operations with an almost surgical precision. Enron, under CEO Ken Lay, was a different beast. It was a pioneer in deregulating energy markets, using complex trading strategies to profit from volatility. Skilling saw potential in the company’s chaos. Where others saw risk, he saw opportunity. His first major move? Convincing Enron to abandon its traditional energy business and bet everything on trading—where profits could be magnified overnight. The early signs of Skilling’s influence were subtle but telling. He introduced rank-and-yank, a performance review system borrowed from General Electric, where the bottom 10% of employees were fired annually. The message was clear: loyalty was optional, results were everything. Under Skilling’s leadership, Enron’s trading desks became a high-stakes casino, where traders bet millions on energy prices with little oversight. The company’s financial statements began to reflect this aggressive growth, but the risks were hidden behind a veil of off-balance-sheet entities. By 1997, Enron’s revenue had surged to $101 billion, and its stock price was soaring. Skilling, now CFO, was the architect of this transformation. He had turned Enron into a financial juggernaut, but the foundation was built on sand.The Early Signs
Even as Enron’s stock price hit record highs, cracks were appearing. In 1998, the company’s first quarterly loss in a decade sent shockwaves through Wall Street. Skilling dismissed concerns, insisting the dip was temporary. But the truth was more troubling: Enron’s profits were being inflated by dubious accounting practices, including the use of mark-to-market valuation, which allowed the company to recognize future profits as current revenue. Critics, including analysts at firms like Merrill Lynch, began questioning whether Enron’s growth was sustainable. Skilling’s response was characteristic: he doubled down. If the market didn’t like the story, he would change the story. By 2000, Enron’s market cap had ballooned to $80 billion, but the company’s debt was spiraling out of control. The early signs weren’t just warnings—they were screams. And Skilling wasn’t listening. The final straw came in August 2001, when The Wall Street Journal published an article questioning Enron’s accounting practices. Skilling’s reaction was telling. Instead of addressing the concerns, he accelerated the company’s expansion into new markets, including broadband and water services—ventures that had little to do with energy but everything to do with masking Enron’s true financial health. By the time the article ran, Skilling had already positioned himself as Lay’s successor. The transition was seamless, almost predestined. But the company’s house of cards was about to collapse.The Turning Point
The turning point came in October 2001, when Fortune magazine named Enron "America’s Most Innovative Company" for the second time. The timing was ironic. Just weeks earlier, Skilling had sold $30 million in Enron stock, netting a profit of nearly $10 million. He was at the peak of his power, but the company’s financial health was deteriorating. The real turning point wasn’t the magazine cover—it was the internal memos that began circulating among Enron’s executives. Sherron Watkins, a vice president, sent a now-infamous memo to Lay warning of an impending collapse. "I am incredibly nervous that we will implode in a wave of accounting scandals," she wrote. Skilling, who had been groomed to replace Lay, was copied on the memo. His response? Silence. The final nail in the coffin was Enron’s decision to reveal its off-balance-sheet partnerships in October 2001. The disclosure sent shockwaves through the market. Investors panicked. The stock price plummeted. By December, Enron filed for bankruptcy, wiping out $63 billion in shareholder value. Skilling, who had once boasted that he could "see around corners," was blind to the disaster he had helped create. His downfall wasn’t just personal—it was systemic. The collapse of Enron Jeffrey Skilling exposed the rot at the heart of Wall Street’s culture of greed and unchecked ambition."Enron was a place where people were encouraged to take risks, but the risks were never truly measured. Skilling believed in the power of data, but he ignored the data that didn’t fit his narrative." — Sherron Watkins, Enron Vice President

The Build-Up, Year by Year
| Period | Key Events |
|---|---|
| 1990–1995 | Skilling joins Enron as a consultant, later becomes CFO. Introduces rank-and-yank and pushes for aggressive trading strategies. Enron’s revenue grows to $101 billion. |
| 1996–2000 | Enron’s stock price soars as it expands into new markets. Skilling’s use of mark-to-market valuation inflates profits. Critics begin questioning the company’s accounting practices. |
| 2001 | Enron’s first quarterly loss in a decade. The Wall Street Journal questions accounting practices. Skilling sells $30 million in stock. Watkins sends her infamous memo to Lay. |
| December 2001 | Enron files for bankruptcy, wiping out $63 billion in shareholder value. Skilling is indicted on fraud charges in 2004. |
Lessons From the Journey
- Unchecked ambition can blind even the sharpest minds. Skilling’s reliance on data didn’t account for human behavior—or the ethical implications of his strategies.
- Corporate culture matters. Enron’s "win at all costs" mentality created an environment where fraud was not just tolerated but encouraged.
- Regulation has limits. Even with oversight, complex financial instruments can be used to obscure risk until it’s too late.
- The fallout from Enron Jeffrey Skilling reshaped corporate governance, leading to stricter accounting rules like the Sarbanes-Oxley Act.
Where Things Stand Today
Jeffrey Skilling spent over a decade in prison, serving his 24-year sentence at the Federal Correctional Institution in Englewood, Colorado. He was released in 2019 after a judge reduced his sentence, citing his cooperation with authorities and his age. Today, Skilling is a reclusive figure, largely absent from public life. He has not given interviews or written memoirs, leaving his side of the story untold. The legacy of Enron Jeffrey Skilling endures, however, as a cautionary tale about the dangers of unchecked corporate power. The collapse of Enron led to sweeping reforms in financial regulation, including the Sarbanes-Oxley Act, which aimed to prevent similar scandals. Yet the culture of greed that enabled Skilling’s rise persists in many corners of Wall Street. The broader impact of the Enron scandal is still being felt. The company’s bankruptcy triggered a wave of lawsuits, investigations, and reforms that reshaped corporate America. The Sarbanes-Oxley Act, passed in 2002, imposed stricter accounting rules and penalties for fraud. Yet the spirit of Enron—where short-term gains outweigh long-term consequences—remains alive in today’s financial markets. Skilling’s case serves as a reminder that systemic failures often require systemic solutions. While he may no longer be a household name, his story is a permanent fixture in the annals of corporate history—a stark example of how far ambition can take a man, and how quickly it can bring him down.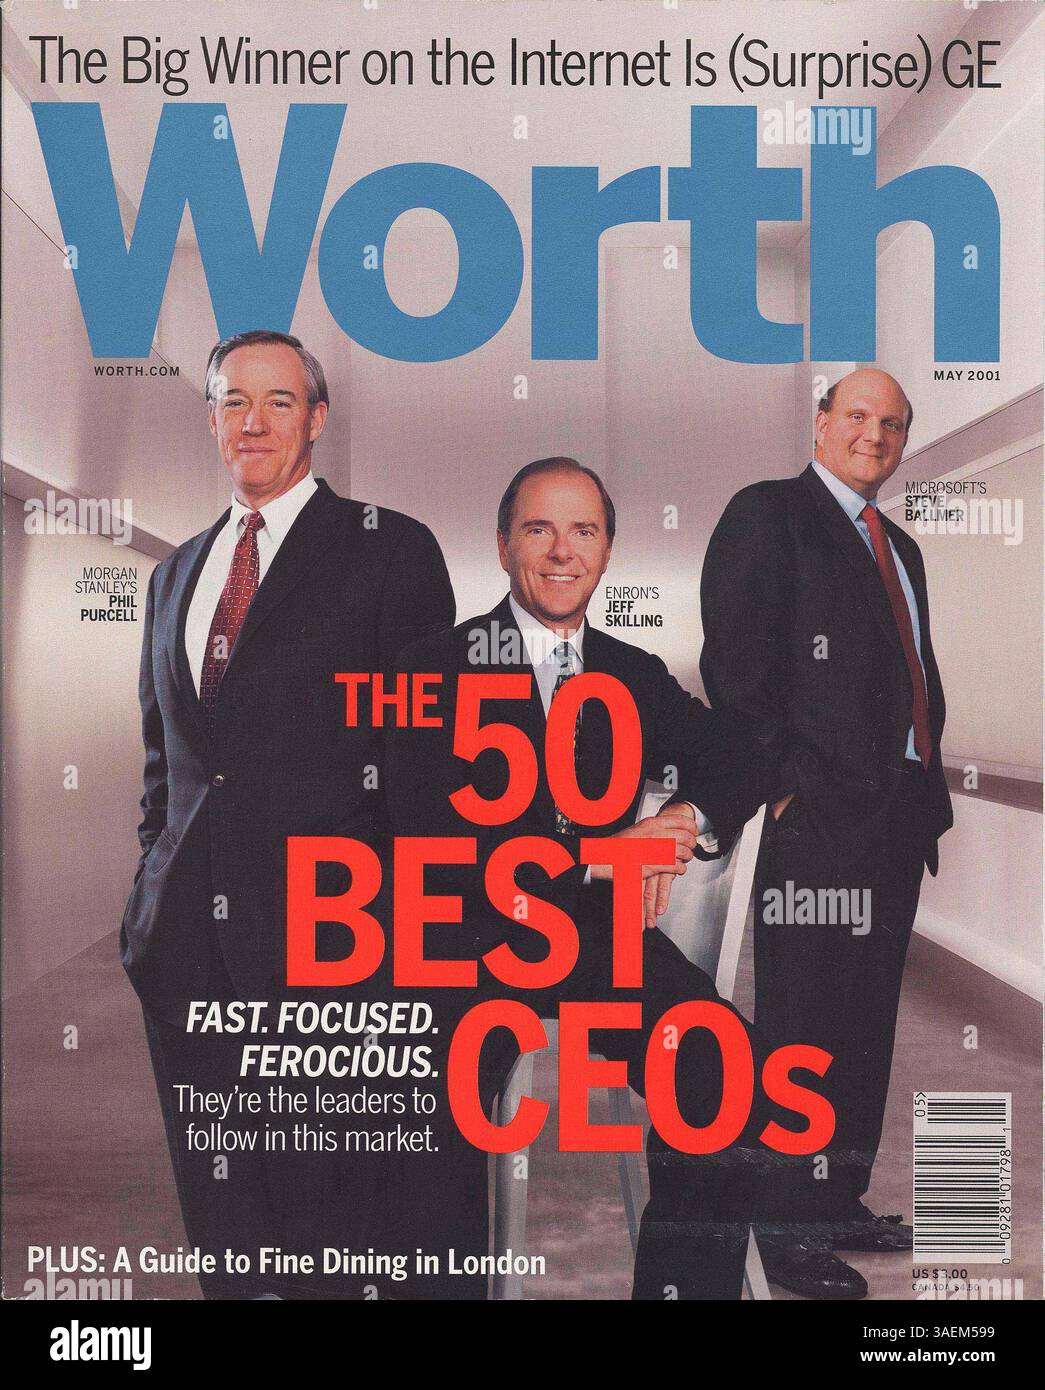
Conclusion
The story of Enron Jeffrey Skilling is more than a tale of corporate fraud—it’s a study in human psychology. Skilling believed in the power of systems, but he underestimated the power of human greed. He saw himself as a visionary, but his vision was clouded by ambition. The collapse of Enron wasn’t just a financial disaster; it was a moral failure. The lessons from his rise and fall are still relevant today, as companies grapple with the same tensions between innovation and ethics, growth and sustainability. Skilling’s legacy is a warning: in the pursuit of success, no one is above the law—and no system is foolproof. Yet there is also a strange symmetry to his story. Skilling’s downfall was as much a product of his era as it was of his own choices. The 1990s and early 2000s were a time when Wall Street rewarded risk-taking above all else. Enron’s collapse was a symptom of a larger cultural shift, one that prioritized short-term gains over long-term stability. In that sense, Skilling wasn’t just a villain—he was a product of his time. But history doesn’t forgive such men for their failures, only for their lessons. And the lesson of Enron Jeffrey Skilling is clear: when the system fails, it’s not just the individuals who pay the price—it’s the entire society that bears the cost.Comprehensive FAQs
Q: What was Jeffrey Skilling’s role in Enron’s collapse?
Skilling was Enron’s CEO when the company collapsed. He oversaw the use of mark-to-market accounting, off-balance-sheet entities, and aggressive trading strategies that inflated profits and hid debt. His leadership created a culture where fraud was tolerated, if not encouraged.
Q: How did Skilling’s accounting practices contribute to Enron’s downfall?
Skilling pushed for mark-to-market valuation, which allowed Enron to recognize future profits as current revenue. This practice, combined with the use of off-balance-sheet partnerships, obscured the company’s true financial health until it was too late.
Q: What was Skilling’s sentence, and where is he now?
Skilling was sentenced to 24 years in prison in 2006 but was released in 2019 after his sentence was reduced. He now lives in seclusion, avoiding public interviews or commentary on his past actions.
Q: Did Skilling cooperate with authorities after his release?
There is no public record of Skilling cooperating with authorities post-release. His legal team has not issued statements, and he has maintained a low profile since his release.
Q: How did the Enron scandal change corporate governance?
The collapse of Enron Jeffrey Skilling led to the Sarbanes-Oxley Act, which imposed stricter accounting rules, CEO certifications of financial statements, and penalties for fraud. The scandal also sparked debates about executive compensation and corporate ethics.
Q: Were there whistleblowers who tried to stop the fraud?
Yes. Sherron Watkins, an Enron vice president, sent a memo to CEO Ken Lay in August 2001 warning of impending disaster. Her warnings were ignored, but her actions became a key piece of evidence in later investigations.
Q: What is Skilling’s net worth today?
Exact figures are not publicly available, but Skilling reportedly sold Enron stock worth millions before the collapse. His current net worth is estimated to be in the low hundreds of millions, though much of his wealth was lost in the scandal.
