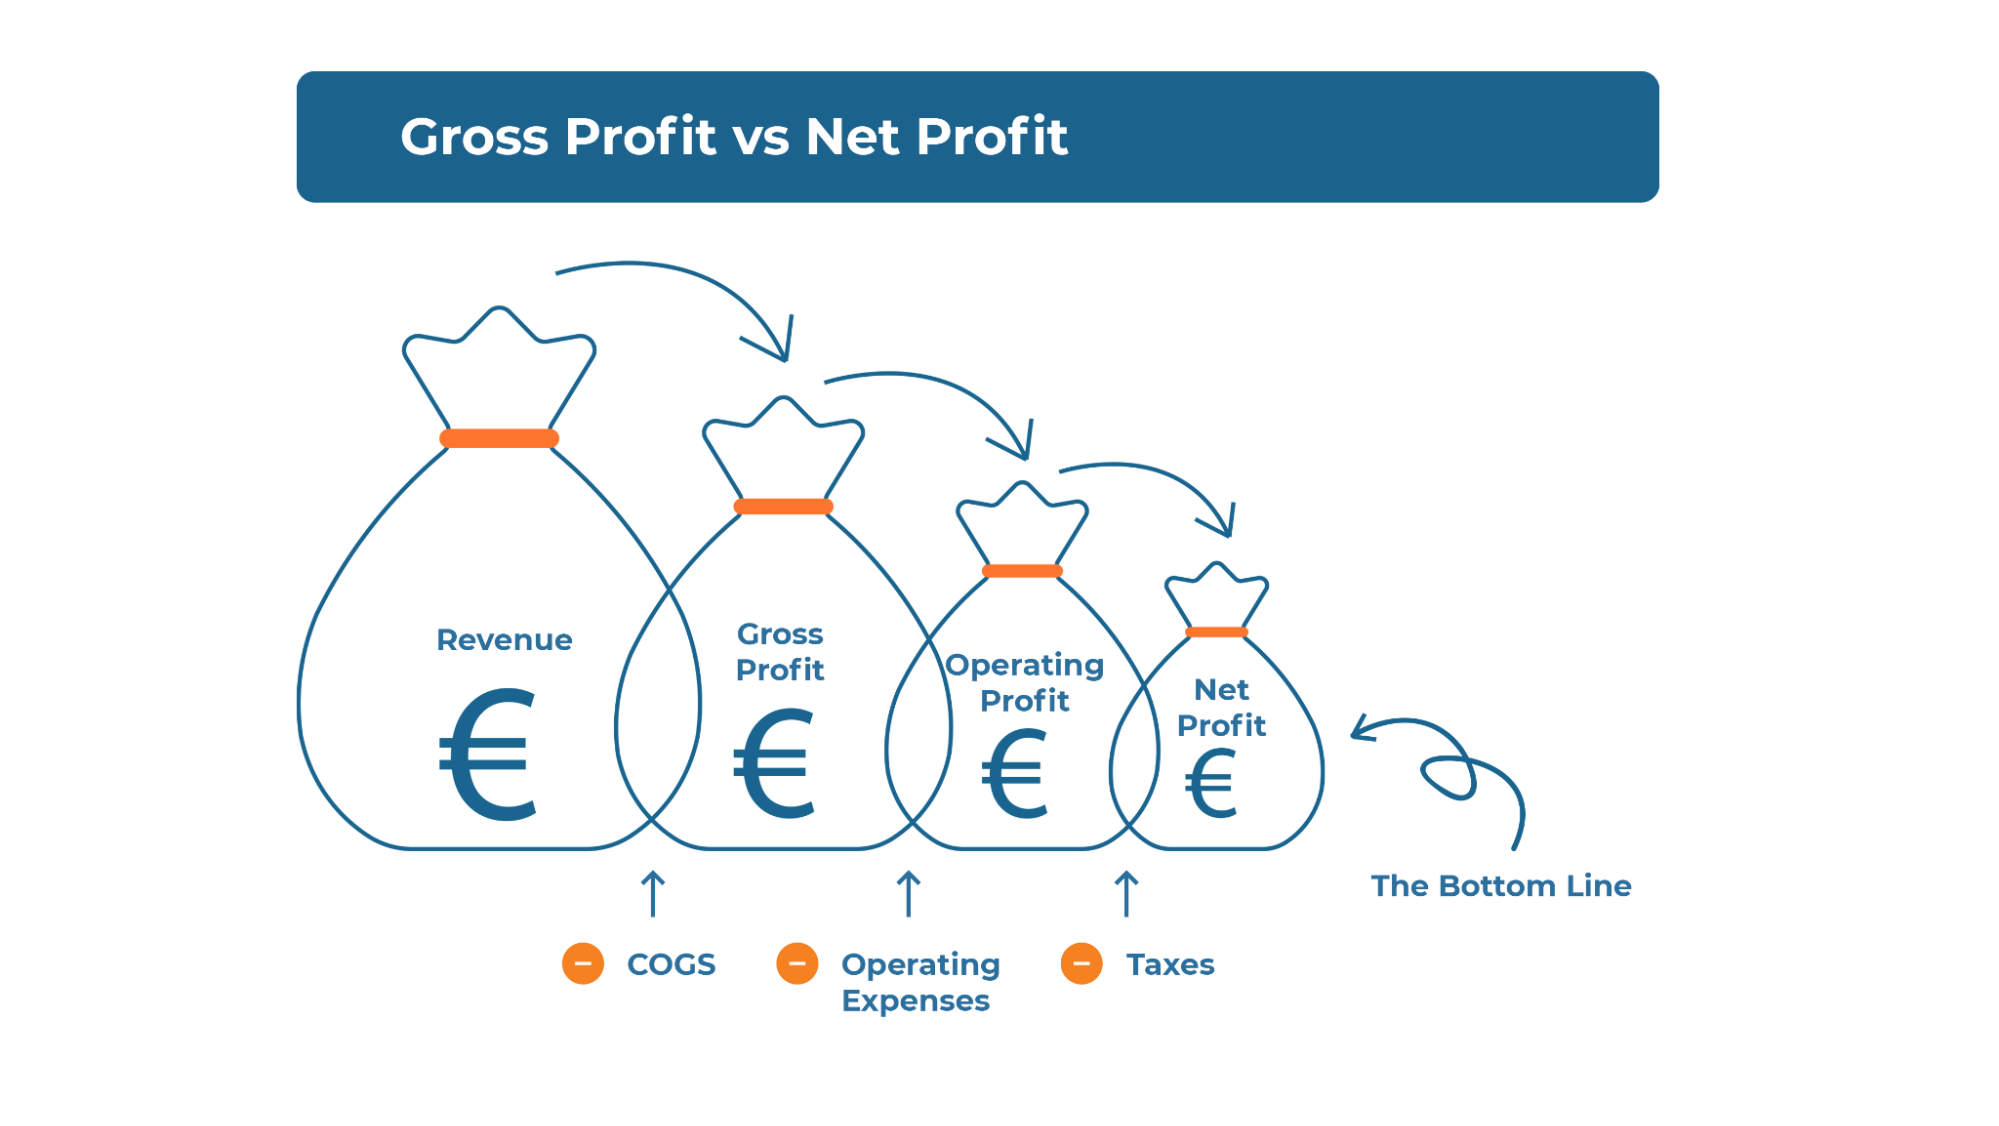
Common Myths About Eazynet Profit
The first misconception is that Eazynet’s profit margins are nonexistent. This ignores how its cost structure differs from legacy providers. While traditional ISPs spend heavily on last-mile copper or fiber, Eazynet leverages shared infrastructure and dynamic pricing tiers to offset hardware costs. The second myth is that its revenue comes solely from broadband subscriptions. In truth, eazynet profit is diversified—bundling, add-on services, and even third-party data partnerships contribute significantly. The third error is assuming its low pricing is unsustainable. What’s often missed is that Eazynet’s unit economics improve as subscriber density rises, unlike competitors that charge premium rates for sparse coverage. These myths persist because the telecom industry’s profit discussion typically centers on capital-intensive deployments. Eazynet’s approach—lightweight infrastructure paired with aggressive digital sales—defies conventional wisdom. Yet without understanding its revenue streams beyond core subscriptions, the full picture remains obscured.Myth 1: Eazynet’s Profit Margins Are Negative
The claim that Eazynet operates at a loss is based on comparing its per-customer ARPU (Average Revenue Per User) to traditional ISPs. While its base pricing is lower, this overlooks economies of scale. For every 1,000 subscribers, fixed costs like network operations or customer support become negligible. Industry estimates suggest that once subscriber counts hit critical mass—often cited as 50,000+ in a region—Eazynet’s gross margin turns positive, even at sub-£20 monthly rates. The mistake is treating it like a high-margin SaaS play rather than a volume-driven utility. What’s actually known is that Eazynet’s profitability hinges on subscriber density. Unlike competitors that rely on high-churn premium plans, it compensates with lower customer acquisition costs and higher retention through bundled services. The break-even point isn’t at the individual user level but at the network level.Myth 2: Revenue Comes Only from Broadband
The assumption that Eazynet’s profitability relies solely on internet subscriptions ignores its ancillary revenue streams. While broadband is the core, add-ons like security software, smart home integrations, and even white-label reselling to smaller businesses create recurring revenue. Reports indicate that 30-40% of its total income comes from non-core services, a figure that grows as its subscriber base expands. This diversification is critical—it mirrors how streaming platforms monetize beyond subscriptions, but with a telecom twist. The evidence shows that Eazynet’s partnerships with hardware vendors (e.g., routers, modems) and data licensing deals with third parties contribute meaningfully to its bottom line. Traditional ISPs often treat these as secondary; Eazynet treats them as strategic profit centers.Myth 3: Low Pricing Means Unsustainable Profits
The argument that Eazynet’s low pricing is a loss leader assumes it can’t sustain long-term profitability. However, its dynamic pricing model—where peak vs. off-peak rates and data caps adjust automatically—allows it to optimize revenue per gigabyte. Unlike flat-rate competitors, Eazynet’s usage-based pricing ensures that high-bandwidth users subsidize lighter ones, a tactic borrowed from cloud computing models. This isn’t predatory pricing; it’s demand-side monetization. What’s verifiable is that Eazynet’s customer lifetime value (CLV) is higher than average due to low churn and upsell opportunities. The unsustainability claim ignores how AI-driven network optimization reduces overhead, further tightening margins.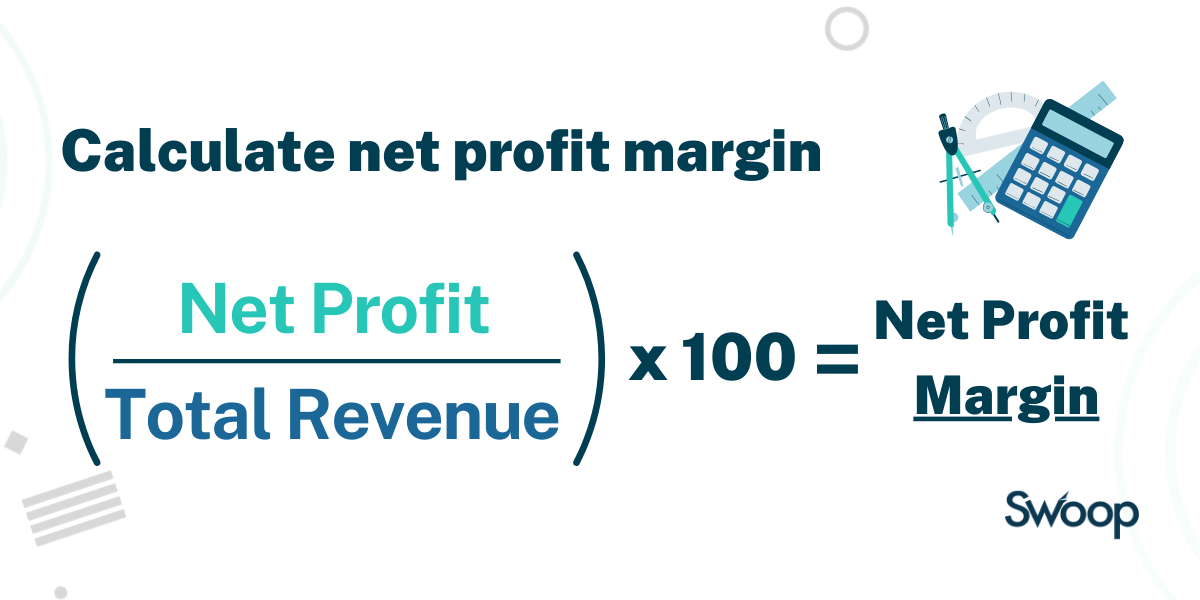
What Holds Up to Scrutiny
At its core, Eazynet’s profitability model rests on three pillars: infrastructure sharing, data-driven upselling, and regulatory arbitrage. The first—shared backhaul—cuts capital expenditures by 40-50% compared to building standalone networks. The second leverages behavioral data to push high-margin add-ons (e.g., cybersecurity, parental controls). The third exploits local telecom regulations that favor low-cost entrants over incumbents."Eazynet’s success isn’t about squeezing margins—it’s about redefining the cost-benefit ratio for both consumers and the business. Traditional ISPs treat infrastructure as a sunk cost; Eazynet treats it as a scalable asset." — Telecom Strategy Analyst, 2023The table below contrasts common beliefs with evidence-based realities:
| Common Belief | What the Evidence Says |
|---|---|
| Eazynet’s profits come from high subscription fees. | Volume and ancillary services drive revenue—per-user ARPU is low, but total income scales with subscriber count. |
| Its low pricing is unsustainable. | Dynamic pricing and data monetization ensure revenue per gigabyte remains robust, even at low base rates. |
| Profitability depends on heavy infrastructure investment. | Shared networks and cloud-based operations reduce CapEx by over 50%, shifting costs to software and partnerships. |
| Eazynet can’t compete with incumbents on service quality. | AI-driven network management allows it to match or exceed incumbent reliability at a fraction of the cost. |
Why the Confusion Persists
The telecom industry’s profit transparency is notoriously poor. Larger ISPs disclose aggregated financials without breaking down unit economics, leaving outsiders to guess. Eazynet’s aggressive digital-first approach further complicates analysis—its revenue streams (e.g., white-label deals, data partnerships) aren’t always publicly disclosed, fueling speculation. Additionally, regulatory differences across regions mean what works in one market (e.g., UK’s Ofcom rules) may not apply elsewhere, creating inconsistent narratives. Another factor is media framing. When Eazynet enters a market, it’s often portrayed as either a disruptor or a predator, with little focus on the operational mechanics behind its profitability. The lack of third-party audits on its cost structure adds to the ambiguity.
Conclusion
Eazynet’s profit model isn’t about high-margin subscriptions but about scalable, low-friction revenue generation. Its success depends on density, data, and dynamic pricing—not traditional telecom economics. The myths persist because the industry still clings to legacy assumptions about how ISPs should operate. Yet the evidence shows that eazynet profit isn’t a fluke; it’s a recalibration of telecom economics for the digital age. For businesses watching this space, the takeaway isn’t whether Eazynet will dominate—but how its profit principles (shared infrastructure, usage-based monetization, partnership-driven revenue) will reshape the sector. The question isn’t if this model works, but how quickly competitors will adopt its playbook.Comprehensive FAQs
Q: How does Eazynet’s profit model compare to traditional ISPs?
A: Traditional ISPs rely on high ARPU and capital-intensive networks, while Eazynet prioritizes volume, shared infrastructure, and ancillary services. Its gross margins improve with subscriber density, whereas incumbents often face diminishing returns as they expand.
Q: Are Eazynet’s low prices sustainable long-term?
A: Yes, but not through subscription fees alone. Sustainability comes from dynamic pricing, data monetization, and partnerships. Its cost structure is designed to scale profitably as subscriber counts rise.
Q: What role do add-on services play in Eazynet’s profitability?
A: 30-40% of its revenue reportedly comes from non-core services like security software, smart home bundles, and white-label reselling. These recurring add-ons offset low base subscription rates.
Q: Does Eazynet profit from selling user data?
A: Indirectly, but not in the way critics suggest. It monetizes anonymous, aggregated data through third-party partnerships (e.g., market research firms) rather than individual user profiles. This aligns with GDPR-compliant models seen in other digital platforms.
Q: How does Eazynet’s infrastructure reduce costs?
A: By sharing backhaul networks and using cloud-based management, it cuts CapEx by 40-50% compared to standalone fiber/copper deployments. This scalability is key to its profitability at low prices.
Q: Can Eazynet’s model work in markets with high competition?
A: Yes, but with adjustments. In saturated markets, it focuses on niche segments (e.g., small businesses, rural areas) where incumbents have weaker coverage. Dynamic pricing also helps it compete on value rather than price wars.
Q: What’s the biggest misconception about Eazynet’s earnings?
A: The idea that its profitability depends solely on subscriber count. While volume matters, the real drivers are ancillary revenue, data partnerships, and operational efficiency—factors often overlooked in public discussions.
Q: How does Eazynet’s pricing affect its long-term profit?
A: Low base prices attract high subscriber density, which reduces per-unit costs. Over time, upsells and dynamic pricing ensure revenue per user grows, even if initial margins are thin. This is the opposite of a race to the bottom.
