Common Myths About e.g. daily net worth
The allure of e.g. daily net worth tracking has birthed a host of misconceptions, chief among them the belief that these figures are objective benchmarks of success. In reality, they’re often curated narratives—partly accurate, partly aspirational, and always context-dependent. Another persistent myth is that real-time updates lead to better financial decisions, when the opposite is frequently true. The human brain isn’t wired to process rapid-fire financial data; it’s wired to react emotionally to perceived losses or gains. Take the case of high-profile investors who publicly share their e.g. daily net worth fluctuations. The assumption is that their transparency translates to reliability, but what’s visible is rarely the full picture. Private equity stakes, deferred compensation, or even personal guarantees on business loans might not appear in a public-facing dashboard. Meanwhile, the psychological toll of monitoring wealth hourly—what researchers call "financial anxiety"—is rarely discussed alongside the metrics themselves.Myth 1: e.g. daily net worth tracking improves financial discipline
Proponents argue that seeing one’s net worth update in real time forces accountability. The logic is straightforward: if you can watch your savings grow (or shrink) daily, you’ll make smarter choices. But behavioral finance research suggests the opposite. Studies on "loss aversion" show that frequent monitoring of declines triggers impulsive reactions—selling assets at lows, for example, or taking on risky bets to recover losses. The illusion of control creates its own pitfalls. Consider the case of retail investors during the 2021 meme-stock frenzy. Platforms like Robinhood made e.g. daily net worth tracking effortless, but the result was a wave of margin calls and emotional trading. One survey found that 68% of frequent portfolio checkers admitted to making at least one regrettable trade based on short-term fluctuations. The data doesn’t lie, but neither does human psychology—and the two don’t always align.Myth 2: Publicly sharing e.g. daily net worth builds trust
Influencers and entrepreneurs often post their e.g. daily net worth as a form of social proof. The thinking goes that transparency equals credibility. Yet financial disclosures are rarely standardized, and what’s omitted can be as telling as what’s included. A celebrity might showcase a seven-figure public net worth while omitting that half of it is tied up in a struggling startup or that their primary income stream is a single endorsement deal. Worse, the practice can backfire. When a high-profile figure’s e.g. daily net worth plummets overnight—due to a market correction or a failed venture—they’re often accused of mismanagement, even if the decline was beyond their control. The public’s focus on the number obscures the bigger question: What does that number actually represent? A snapshot of liquidity? Future earning potential? Or just a moment in time?Myth 3: e.g. daily net worth is the same as spendable income
This is the most dangerous myth of all. Many assume that a high e.g. daily net worth means immediate access to cash, but illiquid assets—real estate, private equity, or even certain retirement accounts—can distort the picture. A tech executive might see their net worth spike due to stock options, only to discover those shares are restricted for years. Meanwhile, a retiree could have a seven-figure portfolio but lack the means to cover a $50,000 medical emergency. The confusion stems from how these platforms aggregate assets. A home’s appraised value might inflate net worth, but selling it could trigger capital gains taxes or leave the owner homeless. Similarly, crypto holdings fluctuate wildly, yet their value on a dashboard doesn’t account for exchange fees, security risks, or regulatory changes. The number is a starting point—not a balance sheet.
What Holds Up to Scrutiny
At its core, e.g. daily net worth tracking serves one undeniable purpose: it provides a baseline for financial self-awareness. For those who use it as a tool—not a crutch—it can highlight spending patterns, investment risks, or opportunities to optimize cash flow. The key lies in context. A hedge fund manager’s e.g. daily net worth might include complex derivatives, while a freelancer’s would focus on client payments and debt. The metric’s value depends entirely on how it’s framed. What’s verifiable is that these tools have democratized financial tracking. Where wealth management was once the domain of private bankers and CFOs, apps now put portfolio snapshots in the hands of baristas and engineers alike. The transparency isn’t perfect, but it’s a step toward breaking down the mystique of money. The challenge is ensuring users don’t mistake the map for the territory."Net worth is a snapshot, not a movie. The danger isn’t in tracking it—it’s in treating it as a destination rather than a checkpoint." — Harvard Business Review, 2022
| Common Belief | What the Evidence Says |
|---|---|
| A high e.g. daily net worth means financial security. | Liquidity, debt structure, and income stability matter more than the headline number. |
| Real-time tracking leads to better decisions. | Frequent monitoring correlates with higher emotional trading and impulsive actions. |
| Public net worth disclosures are accurate. | Most omit illiquid assets, liabilities, or future obligations. |
Why the Confusion Persists
The algorithmic nature of modern finance exacerbates the problem. Platforms like Personal Capital or Mint aggregate data from multiple sources, but their models don’t account for every variable. A sudden drop in e.g. daily net worth might trigger automated alerts, even if the cause is a temporary market blip. Users, in turn, react as if the decline were permanent, selling assets at a loss to "lock in" a higher value. Social media amplifies the confusion. When a celebrity tweets about their e.g. daily net worth hitting an all-time high, followers interpret it as a benchmark for their own lives. But that number is a product of their specific circumstances—age, industry, risk tolerance—none of which apply universally. The lack of standardized reporting only deepens the mystique, turning personal finance into a game of "guess the hidden liabilities."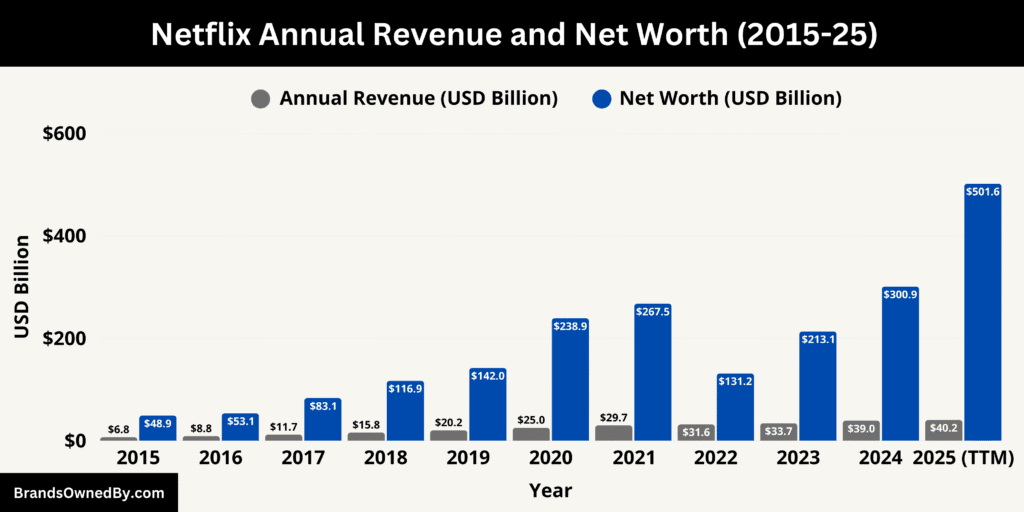
Conclusion
e.g. daily net worth tracking isn’t inherently good or bad—it’s a tool, and like any tool, its impact depends on how it’s used. The real issue isn’t the metrics themselves, but the cultural narrative that surrounds them. We’ve turned a simple financial calculation into a proxy for success, a status symbol, and sometimes even a source of shame. The result is a generation of investors who are more connected to their portfolios than ever—but also more vulnerable to the whims of the market and their own emotions. The solution isn’t to abandon tracking altogether. It’s to approach these numbers with skepticism, context, and a healthy dose of perspective. A net worth figure is just one data point among many. What matters more is understanding why it’s changing—and what that means for your long-term goals.Comprehensive FAQs
Q: Can e.g. daily net worth tracking actually help me save money?
A: Only if you use it as a diagnostic tool, not a stress trigger. Studies show that people who check their net worth monthly (not daily) are more likely to adjust spending habits without emotional reactions. The key is setting reminders to review trends, not to obsess over hourly fluctuations.
Q: Are there legal risks to publicly sharing my e.g. daily net worth?
A: Yes. In some jurisdictions, disclosing net worth can trigger tax audits, creditor scrutiny, or even identity theft risks if the data is tied to specific assets. High-profile cases—like Elon Musk’s occasional tweets about Tesla stock—have led to regulatory warnings. Always consult a financial advisor before making public disclosures.
Q: How do I know if my e.g. daily net worth is "healthy"?
A: There’s no universal standard, but financial planners suggest comparing your net worth to industry benchmarks (e.g., Fidelity’s "Save by 50" rule) and ensuring your liquid assets cover 6–12 months of expenses. A high number means little if it’s tied to illiquid or volatile assets.
Q: Do apps like Mint or Personal Capital give accurate e.g. daily net worth readings?
A: They provide estimates, not audited figures. These tools rely on user-reported data and market APIs, which can lag behind real-time valuations (especially for private equity or real estate). For precision, manual adjustments or professional valuations are often necessary.
Q: Can monitoring e.g. daily net worth improve my investment strategy?
A: Indirectly, but with caution. The most effective investors use these tools to spot trends (e.g., "My crypto allocation keeps spiking—should I rebalance?") rather than reacting to daily noise. Automated alerts can help, but they should be set for meaningful thresholds, not minor fluctuations.
Q: What’s the biggest mistake people make with e.g. daily net worth tracking?
A: Assuming the number reflects their actual financial health. Many ignore debt, future obligations (like college tuition), or the time value of money. A better approach is to track net cash flow—what you earn minus what you spend—over time, not just the static balance.
Q: Are there alternatives to e.g. daily net worth tracking for financial awareness?
A: Yes. Some prefer tracking:
- Monthly cash flow (income vs. expenses)
- Asset allocation percentages (not absolute values)
- Emergency fund reserves (liquid savings)
