
Common Myths About Wealth Comparisons
The first myth is that net worth is a reliable measure of financial health. It’s not. A young professional with $500,000 in student debt and a $1 million home might have a net worth of $500,000—but they’re house-poor, with little liquidity. Meanwhile, a retiree with $800,000 in savings and no debt could be financially secure despite a lower net worth. When people ask how does my net worth compare to others, they often assume higher is always better, ignoring the context of debt, cash flow, and risk exposure. Another persistent belief is that wealth is evenly distributed. It isn’t. The top 10% of U.S. households hold roughly 70% of all wealth, while the bottom 50% collectively own just 2.6%. This isn’t just a statistic—it’s a structural reality that distorts perceptions. Someone earning $150,000 in New York might feel "middle class," but in wealth terms, they’re likely in the bottom 20% nationally. The question how does my net worth compare often leads to frustration because the answer depends on whom you’re comparing yourself to—and most people pick the wrong reference group. A third myth is that transparency solves the problem. Publicly available wealth rankings (like Forbes’ billionaire lists) create the illusion of clarity, but they obscure more than they reveal. The ultra-wealthy are outliers; the vast majority of people fall into the "quiet middle," where net worth grows slowly and invisibly. When someone asks how does my net worth compare to others, they’re usually not thinking about the Forbes 400—they’re thinking about their neighbors, coworkers, or social media feeds. Those comparisons are rarely meaningful.Myth 1: "If I earn more, my net worth will naturally grow"
Higher income doesn’t guarantee higher net worth. In fact, for many, it’s the opposite. The higher your earnings, the more you’re often expected to spend—on housing, education, or lifestyle inflation. A doctor might earn $250,000 but have $300,000 in student loans, leaving their net worth stagnant or even negative. Meanwhile, a skilled tradesperson earning $100,000 might have no debt and a growing 401(k), putting them ahead in net worth despite lower income. The reality is that net worth growth depends on saving rate, debt management, and asset allocation—not just salary. Someone earning $80,000 who saves 30% and invests wisely will outpace someone earning $150,000 who spends aggressively and carries high-interest debt. The question how does my net worth compare should start with this: What am I actually keeping? Income is a means, not an end.Myth 2: "My peers are all doing better than me"
Social comparison is a wealth trap. Studies show that people systematically overestimate their peers’ financial success. A 2020 survey found that 60% of Americans believed their neighbors were wealthier than they were—even though the data suggested the opposite. This bias stems from visibility: people flaunt vacations, cars, and home renovations, but rarely advertise their student loans or medical bills. The truth is that most people are financially similar to their immediate social circles. If your friends are all renting modest apartments and driving used cars, their net worths are likely in the same ballpark as yours. The question how does my net worth compare to others is often answered by the wrong "others"—those who appear wealthier on the surface but may be just as constrained. The real comparison isn’t to Instagram influencers; it’s to people with similar incomes, education levels, and life stages.Myth 3: "Net worth is the same everywhere"
A net worth of $1 million in San Francisco buys a different lifestyle than $1 million in Des Moines. In high-cost cities, that sum might leave you house-poor, while in lower-cost areas, it could set you up for early retirement. The question how does my net worth compare is inherently local—yet most people treat it as a national or global metric. Even within the same country, regional disparities matter. The median net worth in Massachusetts is nearly double that of Mississippi. A teacher in Boston with $500,000 in assets might feel "rich," while an identical net worth in rural Alabama could be considered modest. The confusion persists because wealth benchmarks are rarely adjusted for cost of living. Without context, the question how does my net worth compare is like asking how tall someone is without specifying units—useless without a reference frame.
What Holds Up to Scrutiny
The only reliable way to answer how does my net worth compare is to look at age-adjusted benchmarks. A 30-year-old with $50,000 in net worth is in a different position than a 60-year-old with the same figure. The Federal Reserve’s Survey of Consumer Finances provides a baseline: the median net worth for households under 35 is around $36,000, while those 65+ average $280,000. These numbers aren’t perfect, but they ground the question in reality. Another verifiable fact is that liquid net worth matters more than total assets. A homeowner with $1 million in property but no emergency savings is in a riskier position than a renter with $300,000 in cash and investments. The question how does my net worth compare should focus on cash flow, debt-free assets, and investment flexibility—not just a balance sheet total. A retired couple with $1.5 million but $1 million tied up in a home may struggle, while a 40-year-old with $500,000 in liquid assets could be on solid ground."Most people don’t realize that wealth isn’t about how much you have—it’s about how much you can access when you need it. A high net worth number is meaningless if it’s locked in illiquid assets." — Thomas Corley, author of Rich Habits: The Daily Success Habits of Wealthy Individuals
| Common Belief | What the Evidence Says |
|---|---|
| "I’m behind because my neighbor has a bigger house." | Home size ≠ net worth. Many "luxury" homes are leveraged to the max, leaving owners vulnerable. |
| "If I earn more, my net worth will catch up." | Income ≠ net worth. Spending habits, debt, and savings rate matter more. |
| "I’m in the top 10% if I’m doing okay." | Top 10% starts at ~$170,000/year in income or ~$1.1M in net worth (U.S. data). Most people are in the bottom 50%. |
Why the Confusion Persists
The first reason is selective visibility. People broadcast their successes (new cars, vacations) but hide their struggles (medical debt, side hustles). When you ask how does my net worth compare, you’re often comparing your private numbers to someone else’s highlight reel. Social media algorithms amplify this effect by showing aspirational content, not reality. The second reason is cognitive dissonance. If someone believes they’re "middle class," they’ll interpret data to fit that narrative—even when the numbers say otherwise. A study in the Journal of Consumer Psychology found that people adjust their perceptions of wealth based on their desired self-image. This means the question how does my net worth compare is as much about psychology as it is about math. Finally, financial literacy gaps play a role. Most people don’t track net worth consistently, so they rely on vague impressions. Without a habit of calculating assets and liabilities, the question how does my net worth compare becomes a guessing game—one where the guesses are usually wrong.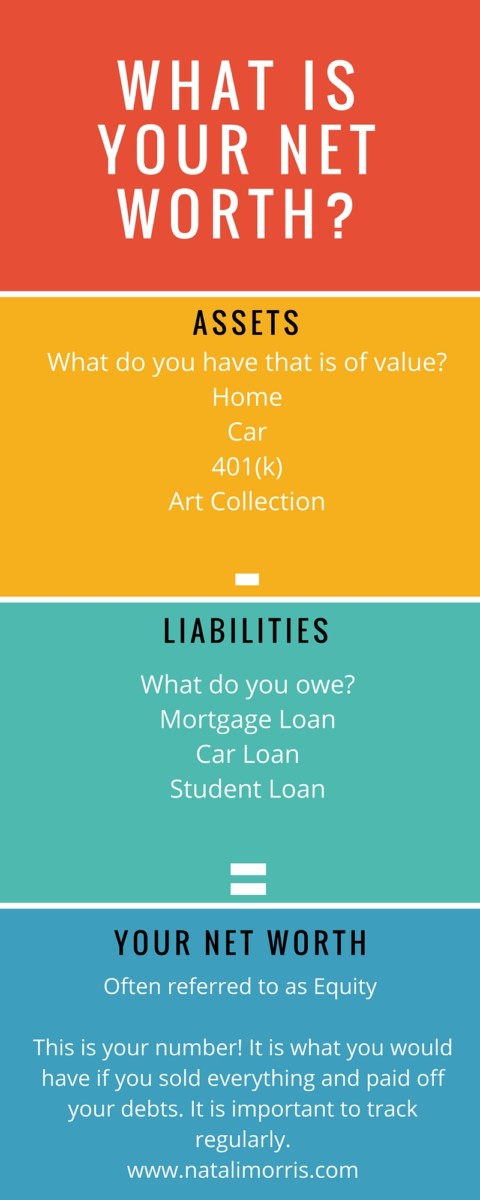
Conclusion
The question how does my net worth compare to others is less about arithmetic and more about perspective. The numbers alone won’t tell you whether you’re ahead or behind—context does. Your age, location, debt structure, and life stage all shape the answer. What’s clear is that most people overestimate their peers’ wealth and underestimate their own progress. The solution isn’t to chase a benchmark, but to focus on what you control: savings rate, debt reduction, and asset diversification. Wealth isn’t a race—it’s a marathon with no finish line. The real question isn’t how do I compare, but how do I build resilience? That’s the only comparison that matters.Comprehensive FAQs
Q: Is there a "good" net worth by age?
A: Yes, but it’s a range, not a fixed number. The Federal Reserve’s data suggests: - Under 35: Median net worth ~$36,000 - 35–44: ~$120,000 - 45–54: ~$165,000 - 55–64: ~$210,000 - 65+: ~$280,000 These are medians—half of people are above, half below. Your "good" net worth depends on your goals, not just the average.
Q: Does homeownership always boost net worth?
A: Not necessarily. A home is an asset, but if it’s your only asset and you’re leveraged (e.g., high mortgage debt), it may not improve your liquid net worth. Renters with strong investment portfolios can sometimes have higher usable net worth than homeowners with all their wealth tied up in property.
Q: Why do I feel poorer than people with less income?
A: This is the lifestyle inflation trap. If you spend aggressively to keep up with peers, a lower income can feel worse than it is. The question how does my net worth compare becomes distorted when you measure success by spending rather than savings. Focus on your savings-to-income ratio—not just absolute numbers.
Q: Can I reverse-engineer my net worth to feel better?
A: Partially. If you’re tracking assets and liabilities monthly, you’ll see progress over time. The key is to compare yourself to your past self, not others. Most people who feel "behind" are actually on track—they just don’t realize it because they’re using the wrong reference group.
Q: What’s the biggest mistake people make when comparing net worth?
A: Assuming net worth is the same as cash flow. A high net worth with no income (e.g., a retiree) is very different from a high net worth with strong earnings (e.g., a business owner). The question how does my net worth compare should always ask: Can I sustain my lifestyle? Net worth alone doesn’t answer that.
Q: Should I care about how my net worth compares to others?
A: Only if it motivates you to take action. If it leads to envy or inaction, it’s harmful. The healthiest approach is to use comparisons as a reality check, not a ruler. Ask: Are my habits aligned with my goals? If yes, the comparison is irrelevant. If no, adjust.
