
Breaking Down the Numbers
Net worth comparisons in 2024 demand context. The raw figure—assets minus liabilities—means little without framing. For instance, a $1 million net worth in Austin, Texas, implies vastly different lifestyle flexibility than the same number in New York City, where property taxes and healthcare costs eat into liquidity. The question how does my net worth compare thus requires two lenses: absolute value (what you own) and relative value (what it buys you). Industry reports suggest that by 2024, the global ultra-high-net-worth (UHNW) population—those with $30 million or more—has grown by 12% year-over-year, driven by private equity and crypto volatility. But below that threshold, the picture is murkier. A 2024 Schwab Modern Wealth Survey found that 42% of Americans with net worth between $250,000 and $1 million report feeling "financially stressed," citing student debt and healthcare expenses as primary drags. The disconnect highlights why how does my net worth compare isn’t just about the total—it’s about the frictions that distort its utility.The Verified Baseline
Publicly available data provides a foundation. The U.S. Census Bureau’s 2023 figures (the most recent complete dataset) show: - Median net worth for white households: $188,100 - Median net worth for Black households: $36,100 - Median net worth for Hispanic households: $41,500 These gaps persist despite economic recovery, with homeownership rates and inheritance patterns playing critical roles. For example, a 2024 Brookings Institution study found that home equity accounts for 60% of wealth for households over 65, but only 20% for those under 35. If you’re asking how does my net worth compare, your age and asset class matter more than the headline number. Verifiable benchmarks also extend to global comparisons. The Credit Suisse Global Wealth Report 2024 estimates the median net worth for adults in: - Switzerland: $220,000 - Australia: $200,000 - United Kingdom: $150,000 - India: $5,000 The variance underscores how how does my net worth compare shifts with currency strength and cost of living. A $100,000 net worth in India buys significantly more disposable income than the same figure in Switzerland, where healthcare and education costs inflate the baseline.What the Estimates Suggest
Beyond verified data lie the estimates—often speculative but influential. Industry analysts suggest that by mid-2024, the average net worth for a 40-year-old in the U.S. has risen to $220,000, up from $180,000 in 2020, thanks to stock market gains and remote-work-driven real estate shifts. However, these figures are highly regional. In Silicon Valley, a 40-year-old with $500,000 in net worth may own a home outright, while in Detroit, the same figure could still require a mortgage. Private wealth managers cite another trend: the "quiet millionaire" phenomenon, where individuals accumulate wealth through side hustles, rental properties, or inherited assets without traditional career trajectories. Estimates place their numbers at $1.2 million median net worth, but with only 30% holding liquid assets—the rest tied to illiquid real estate or business equity. This raises a critical question when evaluating how does my net worth compare: Is your wealth accessible, or is it locked in appreciating (but illiquid) assets?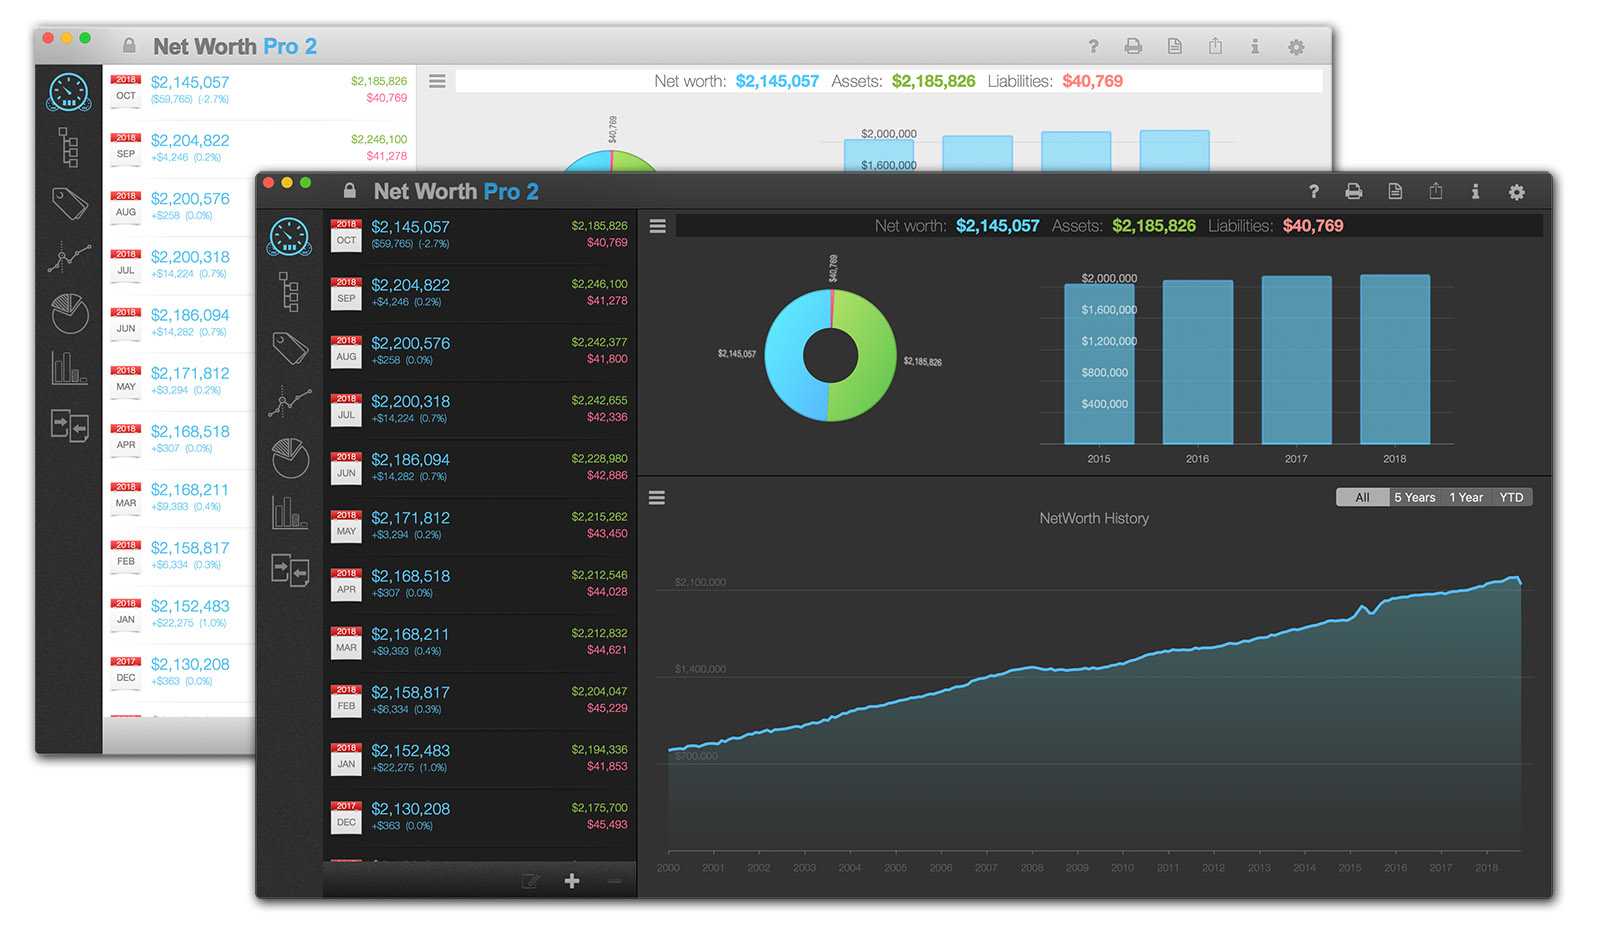
Case Study: A Closer Look
Consider the case of a 35-year-old software engineer in Seattle. In 2020, their net worth was $120,000—primarily in a condo and retirement accounts. By 2024, after a layoff and pivot to freelance consulting, their net worth sits at $350,000, but with $200,000 tied to a single-family rental property. The question how does my net worth compare here isn’t just about the total; it’s about risk exposure. A 20% drop in rental demand could strain cash flow, while a tech rebound might unlock equity. > "Net worth is a lagging indicator. What matters is the velocity of your assets—how quickly you can convert them into cash or opportunities." — Morgan Housel, behavioral finance author| Factor | Estimated Impact (2024) |
|---|---|
| Rental Property (Seattle) | Appreciation: +$150,000 (but illiquid); monthly cash flow: $1,800 |
| Tech Stocks (401k) | Growth: +$80,000 (S&P 500 rally); locked until retirement |
| Freelance Income | Liquidity: +$50,000/year; but subject to tax volatility |
| Emergency Fund | Balance: $30,000 (below 6-month benchmark for freelancers) |
What This Means Going Forward
The next 12 months will test two financial hypotheses. First, whether asset concentration (e.g., heavy exposure to real estate or a single stock) remains viable as central banks tighten policy. Second, whether passive income streams (dividends, rental yields) can offset stagnant wage growth. For those asking how does my net worth compare in 2024, the answer may hinge on diversification beyond traditional benchmarks. Consider the rise of "alternative wealth"—assets like NFTs, private credit, or even collectibles. While these hold estimated 5-10% of portfolios for the top 1%, their volatility means they skew comparisons. A $500,000 net worth with $100,000 in crypto may look robust on paper, but a 30% correction could redefine what "secure" means. The key takeaway? Net worth comparisons are becoming less about the total and more about the composition.
Conclusion
The question how does my net worth compare in 2024 has no single answer. It’s a calculus of where you are, where the economy is, and where you’re headed. The data shows that wealth isn’t distributed evenly—it’s stratified by access, timing, and risk tolerance. For the average professional, the goal isn’t to hit an arbitrary benchmark but to optimize for liquidity, resilience, and growth potential. As you evaluate your position, focus on three metrics: 1. Your peer group’s trajectory (not just their current net worth). 2. The liquidity of your assets (can you access them when needed?). 3. Your personal inflation rate (how fast are your expenses outpacing your gains?). The numbers will fluctuate. The question is whether your net worth is working for you—or just keeping pace with the market.Comprehensive FAQs
Q: How do I adjust my net worth comparison if I live in a high-cost city?
Use cost-of-living-adjusted benchmarks. For example, a $500,000 net worth in San Francisco may feel "average" because the median home price is $1.2 million, but in Dallas, the same figure could imply luxury. Tools like the EPI Cost of Living Calculator or Numbeo can normalize your numbers. Focus on relative purchasing power—can you afford healthcare, education, and retirement without stress?
Q: Does student debt significantly alter how my net worth compares?
Absolutely. Student debt acts as a wealth drag that persists long after graduation. A 2024 Federal Reserve study found that borrowers with $50,000 in student loans have 30% lower net worth than non-borrowers at the same income level. When asking how does my net worth compare, factor in debt-to-income ratios and opportunity cost—the income sacrificed to service debt could have gone toward investments.
Q: Are there industries where net worth growth outpaces the average?
Yes. Tech, healthcare, and skilled trades consistently show above-average net worth growth due to high earning potential and asset accumulation. For example, a 2024 LinkedIn report found that professionals in AI/ML engineering see net worth growth 2.5x faster than the national median, primarily through equity compensation and remote-work-driven real estate plays. However, these sectors also carry higher volatility risk—layoffs or market shifts can reset comparisons quickly.
Q: How does inheritance factor into net worth comparisons?
Inheritance is the wildcard in net worth comparisons. A 2024 Pew Research study found that 60% of wealth for the top 10% comes from inheritance, skewing benchmarks. If you’ve inherited assets, your comparison should account for: - Timing (inherited wealth at 30 vs. 50 changes liquidity needs). - Asset type (cash vs. illiquid real estate vs. private business stakes). - Tax implications (estate taxes can erode gains). Without inheritance, your trajectory may lag peers by 10-20 years—but aggressive saving can close the gap.
Q: Should I compare my net worth to my parents’ generation?
Caution is advised. Generational wealth gaps are real: a 2024 Brookings study found that Gen Xers have 50% more net worth than Millennials at the same age, largely due to lower student debt and homeownership advantages. However, Millennials and Gen Z are outpacing Boomers in asset diversification (e.g., crypto, side hustles). The comparison isn’t just about the number—it’s about how wealth is accumulated. If your parents bought a home at 25, your rental strategy or FIRE (Financial Independence, Retire Early) path may be equally valid.
Q: How do I account for non-traditional assets (e.g., crypto, art, collectibles) in net worth comparisons?
Non-traditional assets distort traditional benchmarks but can be factored in with caveats: - Volatility adjustment: Treat crypto as a separate "high-risk" bucket—only count realized gains (sold assets) toward your core net worth. - Liquidity discount: Illiquid assets (e.g., fine art) should be valued at 70-90% of market price unless you have a verified appraisal. - Peer group relevance: If your network includes collectors or traders, your comparison should reflect industry-specific benchmarks (e.g., a $100,000 art collection may be "average" among curators but outliers elsewhere).
Q: What’s the biggest mistake people make when comparing net worth?
The snapshot error—assuming a single net worth figure tells the whole story. Common pitfalls: 1. Ignoring liabilities: A $500,000 net worth with $400,000 in mortgage debt offers far less flexibility than the same figure with no debt. 2. Overvaluing paper assets: Stocks and crypto can swing ±30% in a year—compare 3-5 year averages for stability. 3. Geographic bias: A $300,000 net worth in Houston may afford a comfortable lifestyle, while the same in NYC could mean renting with no savings. Always localize your benchmark. 4. Lifestyle creep: If your expenses grew with your income but your savings rate didn’t, your effective net worth (what you can live on) may be lower than the headline number.
Q: How often should I reassess my net worth comparison?
Quarterly for active investors, annually for stable earners. Key triggers to reassess: - Major life changes (marriage, children, career shifts). - Market shifts (e.g., post-2024 election policy changes, interest rate hikes). - Personal milestones (paying off debt, hitting a savings goal). Use automated tools (Personal Capital, Mint) to track trends, but manually review at least once a year to account for illiquid assets (real estate, private equity) that platforms may undervalue.
