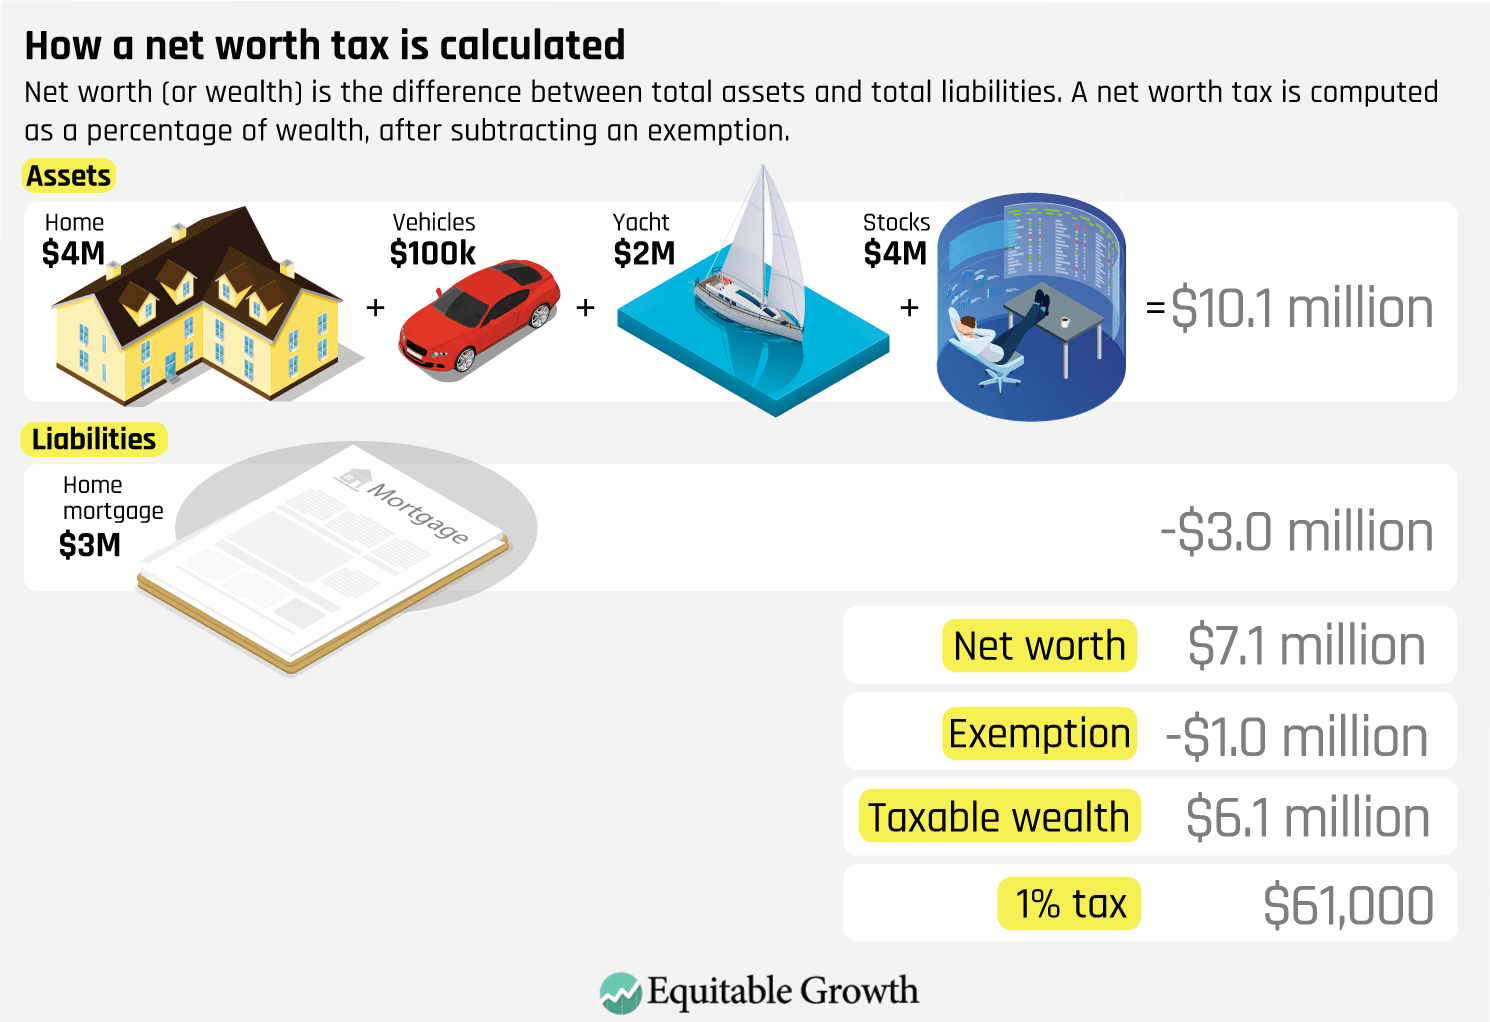
Common Myths About How Net Worth Is Taxed
The assumption that net worth taxes are a straightforward percentage of assets is one of the most persistent misconceptions. In reality, the calculation is rarely that simple. Many believe that if you’re worth £10 million, you’ll pay a flat rate—say, 2%—on that entire figure. But in jurisdictions like Spain or Belgium, the tax brackets are progressive, meaning only the amount above a certain threshold is taxed. A £10 million portfolio might see 0.5% on the first £7 million and 1.5% on the remainder, not a uniform rate. The myth of uniformity extends to liabilities: some systems deduct all debts, while others only allow certain types of loans to offset taxable wealth. This creates a false equivalence between "net worth" in personal finance and "taxable net worth" in fiscal policy. Another widespread belief is that net worth taxes apply only to the ultra-rich. While it’s true that most wealth taxes target the top 0.1% of earners, the thresholds are deceptively low in some countries. In Norway, for instance, the wealth tax kicks in at just over €1.5 million—well within reach of many high-net-worth professionals. The confusion arises because these taxes are often framed as "luxury taxes" or "inheritance levies," obscuring their broader application. Even in the U.S., where federal wealth taxes are rare, state-level property taxes and estate taxes can effectively function as net worth levies for those with modest but concentrated assets, like a single high-value home or a closely held business. The third myth is that taxing net worth is the same as taxing income. They’re fundamentally different beasts. Income taxes apply to earnings—salaries, dividends, rental yields—while net worth taxes target the accumulated value of assets minus liabilities. A software engineer earning £150,000 annually might have a net worth of £500,000 after years of saving, but their taxable income and taxable net worth are treated separately. This distinction matters because it means someone with a high income but few assets (like a consultant with no property) might pay far less in net worth taxes than a retiree with a £2 million pension fund. The interplay between the two creates a system where timing, asset allocation, and even lifestyle choices can drastically alter tax liability.Myth 1: "Net worth taxes are only for billionaires"
The idea that wealth taxes are reserved for the Forbes 400 is a convenient narrative, but it ignores the reality of progressive thresholds. In Germany, for instance, the wealth tax (Vermögensteuer) applies to individuals with assets exceeding €2 million—hardly the domain of Jeff Bezos. The confusion stems from media coverage that focuses on high-profile cases while downplaying the lower brackets. Even in Switzerland, where cantonal wealth taxes vary widely, some regions start taxing net worth at around CHF 2 million. For a family with a primary residence, a pension fund, and a small business, that threshold can be crossed surprisingly quickly. What’s often overlooked is how inflation and asset appreciation push more people into taxable brackets over time. A couple retiring in the early 2000s with a £1 million portfolio might have seen that figure triple by 2020—yet their tax liability could have remained unchanged for years if reassessments were infrequent. The myth persists because wealth taxes are politically sensitive; governments prefer to frame them as affecting only the "richest of the rich," even when the data tells a different story. In Portugal, for instance, the Imposto sobre o Património (wealth tax) was reintroduced in 2022 with a threshold of €600,000—well below the average net worth of many middle-class homeowners in Lisbon.Myth 2: "Liabilities fully offset taxable net worth"
The assumption that all debts can be deducted from assets is another oversimplification. In practice, only certain liabilities qualify for offset. Mortgages on primary residences are often excluded or partially excluded, while business loans or investment property mortgages may be deductible in full. This creates a perverse incentive: the richer you are, the more you might benefit from structuring debts in tax-efficient ways. A property developer with £50 million in assets but £40 million in mortgages could see their taxable net worth shrink dramatically—whereas a retiree with the same asset-to-debt ratio might face no deductions at all. The rules vary by jurisdiction, but the principle is consistent: tax authorities don’t want to encourage excessive leverage. In Spain, for example, only debts secured by taxable assets can be deducted, and even then, the deduction is capped. This means a £10 million property portfolio with £8 million in mortgages might still be taxed on the full £10 million, with only a portion of the debt reducing the liability. The myth that liabilities are a universal offset arises from the way personal finance advice frames net worth—where debts are always subtracted—but tax codes operate under a different set of priorities. The result? A system where financial strategy and tax strategy must align, often requiring specialized advice.Myth 3: "Net worth taxes are the same as capital gains taxes"
This is a category error. Capital gains taxes apply to the profit from selling an asset, while net worth taxes apply to the value of the asset itself—regardless of whether it’s been sold. A fine art collector who buys a Picasso for £5 million and sells it for £10 million will pay capital gains tax on the £5 million gain, but their net worth tax (if applicable) would be based on the £10 million current value. The two systems operate on entirely different timelines and triggers. Capital gains are event-driven; net worth taxes are often periodic, assessed annually or upon death. The confusion arises because both taxes target assets, but their mechanisms are distinct. In the UK, for instance, inheritance tax is levied on the net value of an estate at death, while capital gains tax is paid when assets are disposed of during life. A family that holds a portfolio of stocks for decades might owe nothing in capital gains tax if the assets are never sold—but their heirs could face a hefty inheritance tax bill when the estate is settled. The interplay between the two means that how net worth is taxed depends on whether the tax is triggered by accumulation (wealth tax) or by transaction (capital gains). Ignoring this distinction can lead to costly miscalculations in estate planning.
What Holds Up to Scrutiny
At the core of how net worth is taxed lies a simple but often overlooked principle: jurisdictions prioritize different types of assets. Real estate-heavy systems, like those in France or Italy, focus on property values, while others, like Switzerland, cast a wider net over financial assets and business equity. The most robust evidence shows that wealth taxes are most effective when they’re tied to hard-to-hide assets—like land or listed securities—and least effective when they rely on voluntary disclosures, such as offshore accounts. Studies from the OECD and IMF consistently highlight that wealth taxes work best when they’re part of a broader tax strategy, not a standalone revenue grab. The data also reveals that enforcement is the Achilles’ heel of net worth taxation. Countries with strong property registries and financial transaction records—like the Nordic nations—can tax net worth more accurately than those with opaque systems. The U.S., for example, avoids federal wealth taxes precisely because its patchwork of state and local property taxes already captures a significant portion of wealth. Meanwhile, in jurisdictions like Singapore, where wealth taxes are rare, the government relies on high income taxes and goods-and-services levies to fund public services. The lesson? How net worth is taxed depends less on ideology and more on administrative capacity."Taxing net worth isn’t about punishing success—it’s about ensuring that wealth contributes fairly to the costs of society. The challenge isn’t the principle; it’s the execution." — IMF Fiscal Affairs Department, 2023The gap between theory and practice is best illustrated by comparing two systems:
| Common Belief | What the Evidence Says |
|---|---|
| Wealth taxes are regressive. | Progressive wealth taxes (with high exemptions) are among the most equitable revenue tools, according to the World Bank. |
| Liabilities are always fully deductible. | Only secured, asset-specific debts are typically allowed, creating de facto caps on deductions. |
| Net worth taxes stifle economic growth. | Empirical studies show no consistent link between wealth taxes and GDP contraction in stable economies. |
| Offshore assets are easily taxed. | Jurisdictions with weak information-sharing (e.g., some Caribbean tax havens) still evade scrutiny for millions in wealth. |
Why the Confusion Persists
The primary reason for the enduring confusion is structural: tax codes are written in legalese, not plain language. A clause like "taxable net worth shall exclude the primary residence to the extent of its market value, less any encumbrances, but not exceeding €1.2 million" sounds straightforward until you realize it applies differently to married couples, single owners, and inherited properties. The result? Even tax professionals misinterpret rules, and the public is left guessing. Governments exacerbate the problem by releasing vague guidelines—"assets shall be valued at fair market price"—without defining what "fair market" means in practice. Cultural biases also play a role. In countries with strong privacy traditions, like Switzerland or Austria, wealth taxes are framed as exceptions rather than norms. The narrative is that only "the very rich" are affected, when in reality, the thresholds are often lower than assumed. Meanwhile, in nations with more egalitarian tax philosophies, like Sweden or Denmark, wealth taxes are presented as a civic duty—yet enforcement gaps still create uncertainty. The lack of cross-jurisdictional transparency doesn’t help. A French citizen with assets in Monaco might face conflicting rules on what’s taxable in each jurisdiction, leading to double-counting or double-exemption errors. The system isn’t just complex; it’s deliberately designed to reward those who navigate it with precision.
Conclusion
The question of how net worth is taxed isn’t just a technicality—it’s a reflection of societal priorities. Whether a government chooses to tax wealth annually, at death, or through capital gains reveals its stance on inequality, mobility, and public funding. The most effective systems combine transparency with flexibility, ensuring that wealth is taxed where it’s most visible while allowing for legitimate deductions. Yet the reality is that most people—even those with modest net worth—underestimate how quickly they might cross a taxable threshold, especially in an inflationary environment. For individuals, the takeaway is clear: how net worth is assessed isn’t a static question. It demands regular reviews, especially when assets appreciate, debts are restructured, or residency changes. The tools to mitigate tax exposure exist—trusts, holding companies, and strategic gifting—but they require foresight and often, professional guidance. The alternative? Paying more than necessary, or worse, triggering unintended tax events through poor planning. In an era where wealth is increasingly concentrated, understanding the mechanics of net worth taxation isn’t just for the ultra-rich. It’s a necessity for anyone who wants to preserve what they’ve built.Comprehensive FAQs
Q: Are net worth taxes the same as inheritance taxes?
Not necessarily. Net worth taxes (like annual wealth levies) apply during life, often based on periodic assessments, while inheritance taxes (like estate duties) trigger only at death. Some countries, such as France, combine both—imposing an annual wealth tax on high-net-worth individuals and then levying inheritance tax on their estates. The key difference is timing: net worth taxes are proactive, while inheritance taxes are reactive.
Q: Can I reduce my taxable net worth legally?
Yes, but with strict limits. Common strategies include:
- Structuring assets in trusts or family limited partnerships (subject to local laws).
- Offsetting liabilities where permitted (e.g., business loans).
- Gifting assets within annual exemption limits (e.g., £3,000 per year in the UK).
- Investing in tax-advantaged accounts (e.g., ISAs in the UK or 401(k)s in the U.S.).
Q: Do net worth taxes apply to pensions or retirement accounts?
It depends on the jurisdiction. In the UK, most pensions are exempt from inheritance tax during life but may be taxed upon death if the estate exceeds the nil-rate band. In Switzerland, pension funds are often excluded from cantonal wealth taxes, but lump-sum withdrawals can trigger income tax. The general rule: how net worth is taxed regarding pensions hinges on whether the tax is levied on assets (exempt) or on distributions (taxable).
Q: What happens if I move countries—do I still pay net worth taxes?
This is where things get complicated. Many jurisdictions tax residents on their worldwide net worth, while others (like the U.S.) tax citizens on global assets regardless of residency. Moving to a low-tax country (e.g., Portugal’s Non-Habitual Resident regime) can defer taxes, but selling assets or triggering capital gains may still create liabilities. Always consult a cross-border tax advisor—some treaties prevent double taxation, but others impose exit taxes on unrealized gains.
Q: Are art, jewelry, or collectibles taxed as part of net worth?
Yes, but valuation is the sticking point. Most tax authorities require professional appraisals for high-value items, and some (like Italy) tax art collections annually if they exceed a certain threshold. The challenge? Proving fair market value without selling the asset. In the U.S., heirs can use a stepped-up basis for inherited art, but during life, the IRS may scrutinize gifts or sales to related parties for undervaluation.
Q: Can a business owner reduce taxable net worth by taking on debt?
Partially, but with caveats. Business loans secured by company assets may be deductible, but personal guarantees or unsecured debt often aren’t. The tax authority’s goal is to prevent artificial inflation of liabilities—common in cases where a business owner takes out a loan just before a wealth tax reassessment. Some jurisdictions, like Spain, cap deductions at a percentage of taxable assets, limiting the strategy’s effectiveness.
Q: What’s the most common mistake people make with net worth taxes?
Assuming their personal net worth calculation matches the tax authority’s. Many overlook:
- Excluded assets (e.g., primary residences in some countries).
- Non-deductible liabilities (e.g., credit card debt).
- Timing differences (e.g., capital gains realized vs. unrealized).
- Jurisdictional quirks (e.g., Switzerland’s cantonal variations).
