
6 Things Worth Knowing About How Do I Determine My Household Net Worth
Understanding how to determine your household net worth starts with recognizing that the process is iterative, not static. Assets appreciate or depreciate, debts fluctuate, and market conditions shift. What follows are six foundational principles that separate a rough estimate from a defensible financial audit.1. Net worth isn’t just about big-ticket items
Most people focus on obvious assets—primary residences, investment portfolios, or luxury vehicles—when calculating net worth. But this oversight leads to underreporting. Intangible assets like patents, royalties, or even a thriving side business contribute significantly. For example, a freelancer’s client list or a small business owner’s goodwill may be worth far more than a single property. Similarly, digital assets—cryptocurrency holdings, NFTs, or domain names—often get excluded, yet they can represent substantial value. The error? Assuming only physical or easily liquidated assets matter. A comprehensive audit requires cataloging every form of wealth, even if its value is subjective. Even everyday items can inflate net worth unexpectedly. A vintage wine collection, rare books, or collectible art may hold market value far beyond their original purchase price. Tools like specialized appraisals or auction records can clarify these figures. The lesson: Exhaustive listing—not just high-level estimates—yields a net worth that reflects reality.2. Liabilities aren’t limited to loans and credit cards
Debt is the easiest part of the equation to miscount. Mortgages, auto loans, and credit balances are obvious, but hidden liabilities distort the picture. For instance, unpaid medical bills, outstanding utility debts, or even unreturned library fines can accumulate. Then there are contingent liabilities—legal obligations you might face if, say, you co-signed a loan or are a guarantor for a family member. These don’t appear on credit reports but can drain assets if triggered. The solution? Scour bank statements, tax filings, and personal records for obligations you’ve overlooked. A single missed liability can reduce net worth by tens of thousands, altering financial strategy entirely. Another trap: Opportunity cost as a liability. If you’re renting instead of owning, the difference between your rent and a mortgage payment could be framed as a "lost asset" in some calculations. While this isn’t a traditional liability, it’s a cost of inaction that affects long-term wealth. The takeaway? Debt isn’t just what’s on paper—it’s what you haven’t accounted for.3. Market value ≠ purchase price
The most common mistake in determining household net worth is carrying assets at their original cost. A home bought for $300,000 in 2010 might now be worth $500,000—but if you still list it at the purchase price, your net worth is artificially depressed. The same applies to investments: a stock portfolio’s value today isn’t what you paid in 2008. Appraisal is critical. For real estate, use recent comparable sales (comps) or a professional appraisal. For investments, pull current statements from brokers. Even personal property like jewelry or electronics should be researched via marketplaces or pawn shop valuations. The discipline here? Never assume appreciation or depreciation without evidence. This rule extends to debts, too. A $50,000 student loan taken out at 6% interest may now have a lower balance due to payments, but the current outstanding principal—not the original amount—determines net worth. Ignoring this distinction inflates liabilities and skews results.4. Human capital is the wild card
Human capital—your earning potential—is the most volatile yet valuable asset in net worth calculations. A doctor’s future income stream, a software engineer’s skills in a high-demand field, or even a stay-at-home parent’s ability to generate wealth through caregiving can represent hundreds of thousands in potential value. Yet most net worth statements ignore it entirely. Why? Because quantifying human capital is subjective. Industry estimates suggest it could account for 30–50% of a young professional’s total wealth, but no spreadsheet can capture it precisely. The workaround? Assign a conservative estimate based on career trajectory, salary growth projections, and industry demand. For example, a 30-year-old software engineer with five years of experience might attribute $200,000–$300,000 to their human capital, adjusted annually for promotions or market shifts.
5. Taxes and inflation erode reported net worth
A net worth statement is a snapshot, but taxes and inflation distort the long-term picture. Capital gains taxes, property taxes, or estate taxes can eat into asset values when realized. Similarly, inflation reduces the purchasing power of cash savings over time. The fix? Adjust for time horizons. If you’re calculating net worth to plan for retirement, factor in projected tax liabilities on withdrawals or asset sales. For cash reserves, use real (inflation-adjusted) values rather than nominal figures. The goal isn’t just accuracy today but predictive clarity for tomorrow’s financial landscape.6. Net worth varies by life stage—and that’s intentional
A 25-year-old with student loans and a modest savings account will have a negative or near-zero net worth, while a 55-year-old with a paid-off home and retirement funds may see figures in the millions. This isn’t a failure—it’s a phase. The critical question isn’t whether your net worth is "high enough" but whether it’s trending in the right direction. For example, a young couple might prioritize building human capital (career growth) and liquidity (emergency funds) over asset accumulation. In contrast, a pre-retiree might focus on converting assets into income streams. The takeaway? Benchmark against your own trajectory, not societal averages.
How These Facts Connect
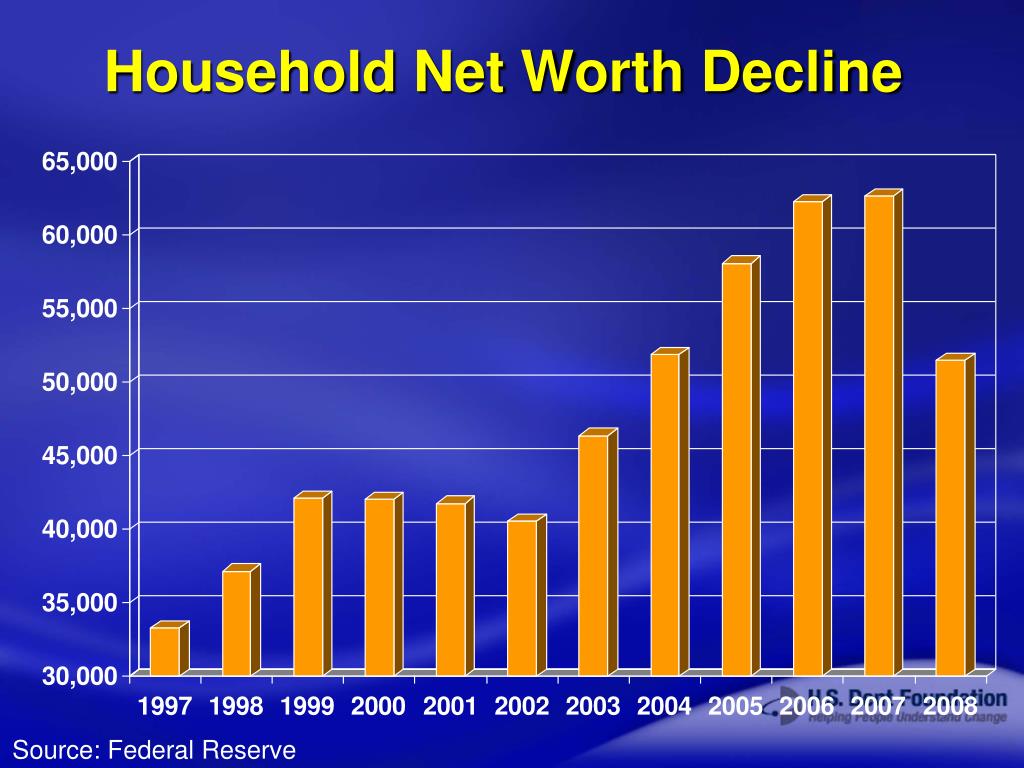
The six principles above reveal that determining household net worth is less about crunching numbers and more about financial storytelling. Every asset and liability tells a part of your economic narrative—whether it’s the side hustle that funded your first home, the student debt that delayed retirement savings, or the inheritance that shifted your trajectory. The most accurate net worth statements don’t just add columns; they explain the "why" behind the "what." For instance, a household with a high net worth but no liquid assets might face solvency risks despite the headline number. Conversely, a lower net worth with diversified, liquid holdings could offer more flexibility. The table below contrasts key considerations when evaluating net worth:| Factor | What It Reveals | Common Mistake | Actionable Fix |
|---|---|---|---|
| Asset Valuation | Current market worth vs. historical cost | Using purchase prices | Appraise annually or use updated statements |
| Liability Scope | Visible debts + hidden obligations | Ignoring contingent liabilities | Audit tax filings and personal records |
| Human Capital | Earning potential’s role in wealth | Excluding entirely | Estimate conservatively based on career data |
| Inflation Adjustment | Real vs. nominal value of cash | Treating dollars as static | Use inflation calculators for long-term planning |
Conclusion
Determining your household net worth isn’t a one-time task but a recurring financial hygiene practice. The process forces you to confront what you control (assets) and what you don’t (liabilities), clarifying where to focus energy. The most precise calculations combine hard data (appraised values, debt statements) with soft insights (career potential, lifestyle trade-offs). The result? A clearer path forward, whether that means accelerating payments, diversifying holdings, or simply gaining peace of mind. The alternative—ignoring the question—leaves you adrift. Without a net worth benchmark, financial decisions become guesswork. But with a disciplined approach, you transform uncertainty into strategy. The first step? Start today. Even an imperfect estimate is better than none.Comprehensive FAQs
Q: Should I include my pension or retirement accounts in net worth?
A: Yes, but with caveats. Defined contribution plans (like 401(k)s or IRAs) should be listed at their current market value, as these funds are accessible (with penalties) if needed. Defined benefit plans (traditional pensions) are trickier—estimate their present value using actuarial tables or employer projections, but note that early withdrawals may incur penalties. The key is consistency: treat retirement assets as liquid if they’re part of your financial safety net.
Q: How often should I recalculate my household net worth?
A: Annually is ideal for most households, aligning with tax season and major life events (marriage, inheritance, job changes). High-net-worth individuals or those with volatile assets (e.g., crypto, startups) may recalculate quarterly. The goal isn’t perfection but trending awareness—spotting shifts in asset values or debt levels early enough to act.
Q: What if my net worth is negative? Is that a problem?
A: Not inherently. A negative net worth is common for young adults, students, or those early in their careers. The concern arises if it’s persistent without progress. For example, a negative net worth at 25 may be expected, but the same at 45 suggests systemic issues (e.g., unchecked debt, stagnant income). The fix? Focus on liquidity and human capital—building skills, increasing income, or reducing high-interest debt to improve the trajectory.
Q: Do I need to hire a professional to determine my net worth?
A: For most households, no—spreadsheets and online tools (like Personal Capital or Mint) suffice if you’re meticulous. However, high-net-worth individuals (assets over $1M+) or those with complex holdings (trusts, international properties) benefit from a financial advisor or CPA. These professionals can navigate tax implications, appraisal nuances, and estate planning considerations that DIY methods miss.
Q: Should I include my car’s value in net worth?
A: Yes, but realistically. Use Kelley Blue Book or Edmunds for current trade-in value, not the original purchase price. Cars depreciate rapidly—including an inflated value skews your net worth. The exception? Classic or collector cars, which may appreciate and should be appraised separately.
Q: How do I handle joint assets with a partner or family?
A: Clarify ownership first. Jointly owned assets (e.g., a shared home) should be divided equally in the net worth calculation unless specified otherwise. Gifts or inheritances may require adjusting for taxes or legal restrictions. For simplicity, many households split joint assets 50/50 unless a prenuptial agreement or trust document dictates otherwise. Transparency here prevents disputes later.
Q: What’s the difference between net worth and net income?
A: Net worth is a stock measure (what you own minus what you owe at a point in time). Net income is a flow measure (take-home pay after taxes and deductions over a period). Confusing the two leads to poor decisions—for example, assuming high net income means high net worth, or vice versa. Net worth reflects wealth accumulation; net income reflects cash flow. Both matter, but they answer different questions.
