
The Short Answers
- A conglomerate like Disney operates across unrelated industries (e.g., film, sports, tech) to spread risk and create synergies—unlike a diversified company that stays within one sector.
- Disney’s vertical integration (owning production, distribution, and exhibition) lets it maximize profits at every stage, from Frozen toys to theme park tickets.
- Conglomerates thrive by cross-promoting assets—e.g., The Mandalorian on Disney+ drives Star Wars merchandise sales, which fund new films.
- Regulatory scrutiny increases as conglomerates grow, but Disney’s nonprofit status for its parks and lobbying efforts help mitigate antitrust risks.
- Modern conglomerates like Disney use data and tech (e.g., AI-driven content recommendations) to dominate, not just traditional media assets.
- The biggest risk? Over-diversification—if one segment (e.g., cable TV) declines, the whole structure must adapt, as Disney is now doing with streaming.
Deep Dive: The Full Picture
Disney’s empire isn’t just a collection of businesses—it’s a closed-loop economy. When a child watches Encanto on Disney+, they’re primed to buy the soundtrack, visit Epcot’s Latin America pavilion, and later attend a live Encanto stage show. Each transaction reinforces the next. This is the essence of a highly optimized example of a conglomerate: every division is designed to feed into another, creating a self-sustaining cycle. Even its failures (like The Rise of Skywalker) become marketing tools, with merchandise and re-releases extending their lifespan. The strategy extends beyond entertainment. Disney’s acquisition of 21st Century Fox in 2019—for a reported $71.3 billion—wasn’t just about films. It secured Fox’s regional sports networks (critical for local TV ad revenue) and its international broadcasting assets, ensuring Disney+ could compete globally. This move turned the streaming service from a side project into a cornerstone of the conglomerate’s future. The lesson? Conglomerates don’t just buy assets; they buy ecosystems.The Context You Need
The modern conglomerate model emerged from the 20th century’s industrial titans—companies like General Electric or ITT that sprawled across unrelated industries to avoid market crashes. But Disney’s approach is different: it’s not just diversified; it’s interdependent. While GE’s conglomerate structure was once criticized as bloated, Disney’s is deliberately lean. It doesn’t hold onto every asset; it prunes aggressively. The sale of ABC’s radio stations in the 2000s, for example, freed up capital for streaming—proving that even conglomerates must evolve or risk obsolescence. The digital age has forced a shift. Traditional conglomerates like ViacomCBS (now Paramount Global) struggled as linear TV declined, but Disney anticipated the change. By 2017, it was already testing direct-to-consumer models with Disney+. When competitors like Warner Bros. followed, Disney had a five-year head start—a classic conglomerate advantage. The takeaway? The most successful examples of conglomerates today aren’t just holding companies; they’re platforms that control the entire value chain.The Mechanics
Disney’s playbook relies on three pillars: ownership, data, and cultural dominance. Ownership ensures it captures profits at every stage—from Avengers movies to Marvel comics to Disney World souvenirs. Data, collected through subscriptions and park visits, lets it predict trends (e.g., why Frozen became a phenomenon). And cultural dominance? That’s the moat. When a franchise like Star Wars becomes a global religion, its merchandise, games, and theme park rides generate billions—all within Disney’s control. The mechanics aren’t just about assets, though. It’s about timing. Disney’s 2020 pivot to "Disney Priority Access" (a $8/month add-on for early streaming access) showed how it could monetize fan obsession. Meanwhile, its direct negotiations with theaters (bypassing traditional distributors) cut costs and boosted profits. This is the hallmark of a modern example of a conglomerate: it doesn’t just compete; it rewrites the rules of competition.Details That Change the Picture
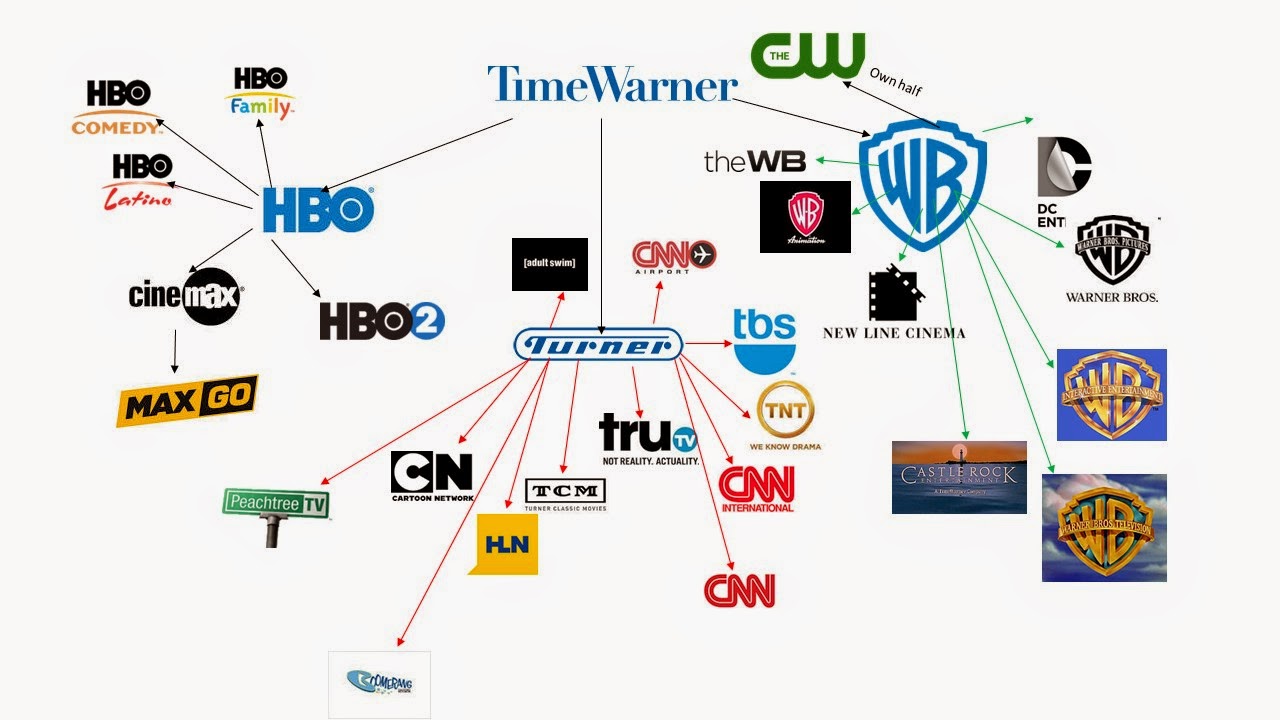
Not all conglomerates succeed. AT&T’s failed attempt to merge with Time Warner in 2018—blocked by regulators—highlighted the risks of overreach. Disney, however, navigates this carefully by acquiring, not just merging. When it bought Lucasfilm in 2012, it didn’t just add Star Wars; it secured a franchise with near-limitless merchandising potential. The result? The Force Awakens grossed $2 billion worldwide—and every dollar went back into Disney’s ecosystem. The real difference lies in synergy execution. While other conglomerates talk about cross-promotion, Disney engineers it. A National Geographic documentary on Disney+ doesn’t just attract subscribers; it drives park attendance for Animal Kingdom. Even its failures (like The Black Hole reboot) get repurposed into educational content for Disney Junior. This isn’t accidental—it’s strategic cannibalization, where every asset is optimized for maximum ROI."Disney doesn’t just own IP; it owns the emotional real estate of generations. That’s why its conglomerate model isn’t just about media—it’s about cultural infrastructure." — Bob Iger, former Disney CEO, in a 2021 interview with The Hollywood Reporter
| Division | Synergy Example |
|---|---|
| Disney+ | Streaming Star Wars content drives merchandise sales, which fund new films. |
| ESPN | NFL broadcasts on ESPN+ boost Disney+ subscriptions via bundled offers. |
| Parks | Epcot’s futuristic exhibits promote Disney’s tech investments (e.g., robotics). |
| ABC News | Political coverage on Hulu (owned by Disney) influences ad revenue for linear TV. |
Conclusion
Disney’s model proves that the most durable examples of conglomerates aren’t those that simply own multiple businesses, but those that design them to interact. The company’s ability to turn a single franchise into a multi-billion-dollar ecosystem—from films to theme parks to fast food—isn’t luck. It’s engineered synergy. As streaming wars intensify and traditional media declines, Disney’s approach offers a masterclass in how to future-proof a business by controlling its own destiny. The warning, however, is clear: conglomerates must adapt or die. Blockbuster’s failure to pivot from rentals to streaming is a cautionary tale. Disney’s success comes from constant reinvention—whether through acquisitions, tech investments, or even rebranding its parks as "destinations" (not just attractions). The lesson for any business studying this example of a conglomerate? Diversification alone isn’t enough. It’s about building a machine where every part moves the whole forward.Comprehensive FAQs
Q: How does Disney’s conglomerate structure differ from, say, Amazon’s?
Amazon operates as a platform-driven conglomerate, using its retail and cloud infrastructure to enter new markets (e.g., streaming via Prime Video). Disney, by contrast, is a content-first conglomerate—its assets (films, parks, sports) are the product, not the platform. Amazon’s strength is logistics; Disney’s is cultural IP.
Q: Are there risks to Disney’s vertical integration?
Yes. Over-reliance on a few franchises (Star Wars, Marvel) creates single points of failure. If a major IP underperforms (e.g., The Black Widow’s box office disappointment), it can ripple across divisions. Additionally, regulatory scrutiny increases as Disney expands—its 2019 Fox deal faced antitrust concerns, and future moves may too.
Q: Can a small company replicate Disney’s conglomerate model?
No—not directly. Disney’s scale (and deep pockets) allows it to acquire, develop, and market at a level most companies can’t. However, smaller businesses can adopt micro-synergies: for example, a local bakery selling pastries in its café while using social media (owned by Meta, another conglomerate) for marketing. The principle is the same: create interconnected revenue streams.
Q: How does Disney’s streaming strategy fit into its conglomerate model?
Disney+ isn’t just a profit center—it’s a loss leader. By subsidizing content with park revenue and merchandise, Disney ensures its streaming service acquires loyal subscribers who then engage with other divisions. The goal isn’t short-term profitability but long-term ecosystem lock-in. This is why Disney can afford to license Star Wars to competitors (e.g., Netflix’s The Mandalorian spin-offs) while still benefiting.
Q: What’s the biggest threat to Disney’s conglomerate dominance?
Fragmentation. As younger audiences shift to TikTok and YouTube, Disney’s reliance on long-form, branded content could weaken. Additionally, rising production costs (e.g., The Mandalorian’s $200M+ budgets) threaten margins. Finally, regulatory pressure on big tech/media mergers could limit Disney’s ability to acquire key assets—like its failed bid for 21st Century Fox’s regional sports networks in 2022.
Q: How does Disney use data in its conglomerate strategy?
Disney’s first-party data (from subscriptions, park visits, and merchandise purchases) lets it personalize offerings. For example, Disney+ recommends content based on viewing history, while parks use mobile apps to upsell experiences (e.g., "Buy a Frozen-themed snack here"). This data also informs content development—like why Encanto’s Latin American focus aligned with rising Hispanic viewership trends.
Q: Could Disney’s model work in industries outside entertainment?
Yes, but with adjustments. A healthcare conglomerate, for example, could integrate hospitals, insurance, and wellness apps—using patient data to cross-promote services (e.g., "Visit our clinic, then get a discount on our fitness program"). The key is owning the customer journey from start to finish, not just selling discrete products. Automotive companies (e.g., Tesla’s vertical integration of batteries, software, and charging networks) already use similar logic.
