
The Short Answers
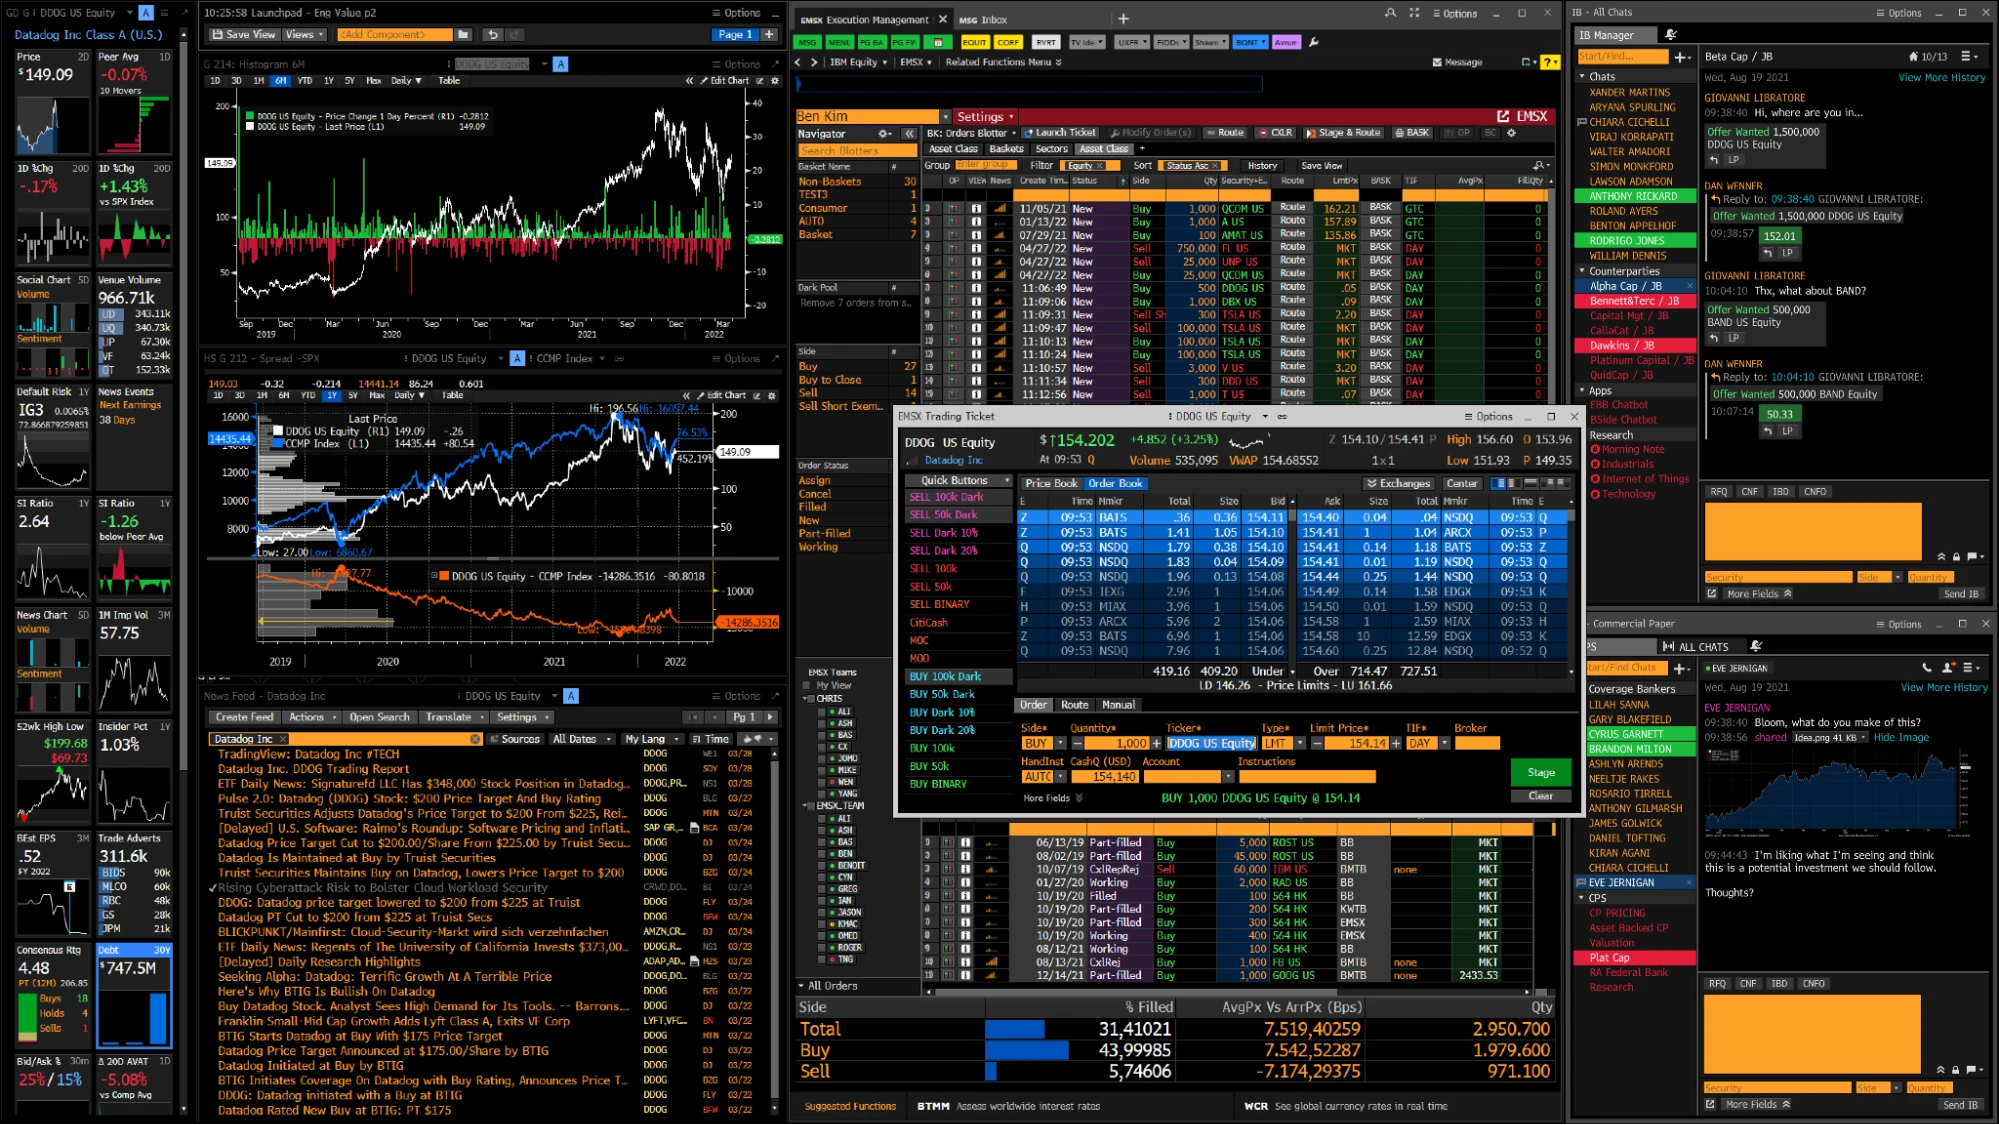
- Bloomberg made his fortune by creating a financial data terminal that became indispensable to Wall Street traders.
- His company, Bloomberg LP, monetized the terminal through hardware sales, data subscriptions, and later media and software services.
- Strategic acquisitions (like Businessweek) and political influence expanded his empire beyond finance into media and policy.
- The core of his wealth remains tied to Bloomberg’s data monopoly, which still generates billions annually.
Deep Dive: The Full Picture
The story of how did Bloomberg make his money starts with a single, brutal observation: Wall Street was inefficient. In 1981, Bloomberg—then a bond trader at Salomon Brothers—noticed that traders spent more time tracking down market data than analyzing it. The solution? A machine that could deliver real-time financial information faster than any human could type it. His first terminal, built with a team of engineers, cost $30,000 to produce. Salomon bought one. Then another. Then Bloomberg quit to sell them himself. The terminals weren’t just tools; they were weapons. Bloomberg structured the hardware so that each new purchase required a subscription to his data feeds. The more traders used the terminals, the more they paid—not just for the machines, but for the exclusive data that made them indispensable. By 1987, Bloomberg LP was profitable. The terminals weren’t just selling; they were creating a lock-in effect. How did Bloomberg make his money? He didn’t just sell a product—he sold a necessity.The Context You Need
The 1980s were a golden age for financial innovation. Computers were getting cheaper, but Wall Street’s infrastructure was still stuck in the 1960s. Bloomberg’s insight was that information wasn’t just data—it was power. His terminals didn’t just display prices; they offered analytics, news, and even messaging systems for traders. The more complex the terminal became, the harder it was for competitors to replicate. Bloomberg’s early advantage wasn’t just technology—it was how did Bloomberg make his money by ensuring that every dollar spent on a terminal also funded his data empire. The risk was enormous. Bloomberg bet his entire career on the idea that traders would pay for convenience. When Salomon Brothers tried to block his terminal sales, Bloomberg sued—and won. The legal battle cemented his independence. By the late 1980s, his company had no debt, no shareholders, and a revenue model that relied entirely on recurring subscriptions. The terminals weren’t just selling; they were building a moat.The Mechanics
The terminals were the Trojan horse. Bloomberg’s real money came from the data. Each subscription included access to his proprietary feeds, which were faster and more comprehensive than anything else on the market. The more traders relied on the terminals, the more they paid—not just for the hardware, but for the data that made the hardware valuable. By the 1990s, Bloomberg LP’s revenue was split between hardware sales (which declined as PCs improved) and data subscriptions (which grew exponentially). The pivot to media came later. In 2009, Bloomberg LP acquired Businessweek for $50 million, a fraction of its peak value. The move wasn’t just about journalism—it was about reinforcing the data monopoly. The magazine’s brand became another channel to distribute Bloomberg’s insights, ensuring that traders and policymakers stayed locked into his ecosystem. How did Bloomberg make his money? By turning data into a subscription service, then expanding into media, software, and even political influence.Details That Change the Picture
The terminals weren’t just a product—they were a network. Bloomberg’s early terminals included a built-in keyboard and screen, but the real value was in the how did Bloomberg make his money by bundling data, news, and analytics into a single, proprietary system. Competitors like Reuters and Dow Jones tried to copy the model, but Bloomberg’s early-mover advantage was insurmountable. By the time the internet made data freely available, Bloomberg had already locked in generations of traders who saw his terminals as essential. The political dimension is often overlooked. Bloomberg’s donations and lobbying efforts—particularly in New York—helped shape regulations that favored his business model. His company’s influence extended beyond finance into city hall, ensuring that policies around data access and financial markets aligned with his interests. How did Bloomberg make his money? Partly by ensuring that the rules of the game worked in his favor."The terminal wasn’t just a tool—it was a way to own the conversation. If you controlled the data, you controlled the market." — Former Bloomberg LP executive (anonymous, 2015)
| Year | Key Financial Milestone |
|---|---|
| 1981 | First Bloomberg terminal sold to Salomon Brothers; company founded. |
| 1987 | Bloomberg LP turns profitable; terminals become standard on trading floors. |
| 2009 | Acquisition of Businessweek; expansion into media begins. |
Conclusion
Michael Bloomberg’s fortune wasn’t built on luck. It was built on how did Bloomberg make his money by identifying a critical bottleneck—Wall Street’s reliance on slow, fragmented data—and turning it into a subscription business. The terminals were the hook, but the real money came from the data, the media, and the political influence that kept the ecosystem intact. His empire didn’t just sell information; it made information indispensable. The lesson in how did Bloomberg make his money isn’t just about technology—it’s about control. Bloomberg didn’t just sell a product; he sold access to a world where his data was the only game in town. That’s why, decades later, his company still dominates financial news and analytics. The terminals may have evolved, but the core principle remains: how did Bloomberg make his money? By ensuring that the people who moved markets paid for the privilege of doing so.Comprehensive FAQs
Q: Was Bloomberg’s first terminal really just a $30,000 machine?
Yes. The original Bloomberg terminal, launched in 1982, cost around $30,000 to produce. Early buyers like Salomon Brothers saw it as a luxury—until they realized how much time it saved. The real value wasn’t in the hardware but in the data subscriptions tied to it.
Q: How much of Bloomberg’s wealth comes from the terminals today?
While exact figures aren’t public, Bloomberg LP’s data and media divisions still generate billions annually. The terminals remain a core revenue driver, though the company has diversified into software, TV (Bloomberg Television), and digital media. The original data monopoly is still the backbone.
Q: Did Bloomberg’s political donations help his business?
Indirectly, yes. Bloomberg’s philanthropy and lobbying—particularly in New York—helped shape policies that benefited his data business. For example, his support for financial regulations often aligned with his company’s interests in maintaining data exclusivity.
Q: Why didn’t competitors like Reuters or Dow Jones kill Bloomberg’s business?
Early competitors failed because Bloomberg moved faster. By the time they caught up, his terminals were already embedded in trading floors worldwide. The network effect—where more users made the system more valuable—created a moat that was nearly impossible to breach.
Q: Is Bloomberg’s media empire (like Businessweek) still profitable?
Yes, but not in the traditional sense. Bloomberg LP’s media assets—including Businessweek, Bloomberg TV, and digital news—are profitable primarily as loss leaders. Their real value is reinforcing the data ecosystem by keeping traders and policymakers engaged with Bloomberg’s brand.
Q: How did Bloomberg’s terminals become so dominant?
Three factors: speed (real-time data), convenience (all-in-one platform), and lock-in (subscriptions tied to hardware). Traders who switched to competitors risked losing efficiency—and business. Bloomberg’s early advantage in bundling data, news, and analytics made it nearly impossible to leave.
Q: What’s the biggest misconception about how Bloomberg made his money?
The biggest myth is that he got rich from hardware sales. In reality, the terminals were just the delivery mechanism. The real wealth came from the how did Bloomberg make his money by selling subscriptions to his data feeds, which became the lifeblood of global finance.
Q: Could someone replicate Bloomberg’s success today?
Unlikely, but not impossible. The key ingredients are: identifying an information bottleneck, building a proprietary system, and ensuring network effects lock in users. Today, the challenge would be competing with open-source data and cloud computing—but the principle remains the same: control the pipeline, and you control the money.
