Where It All Began
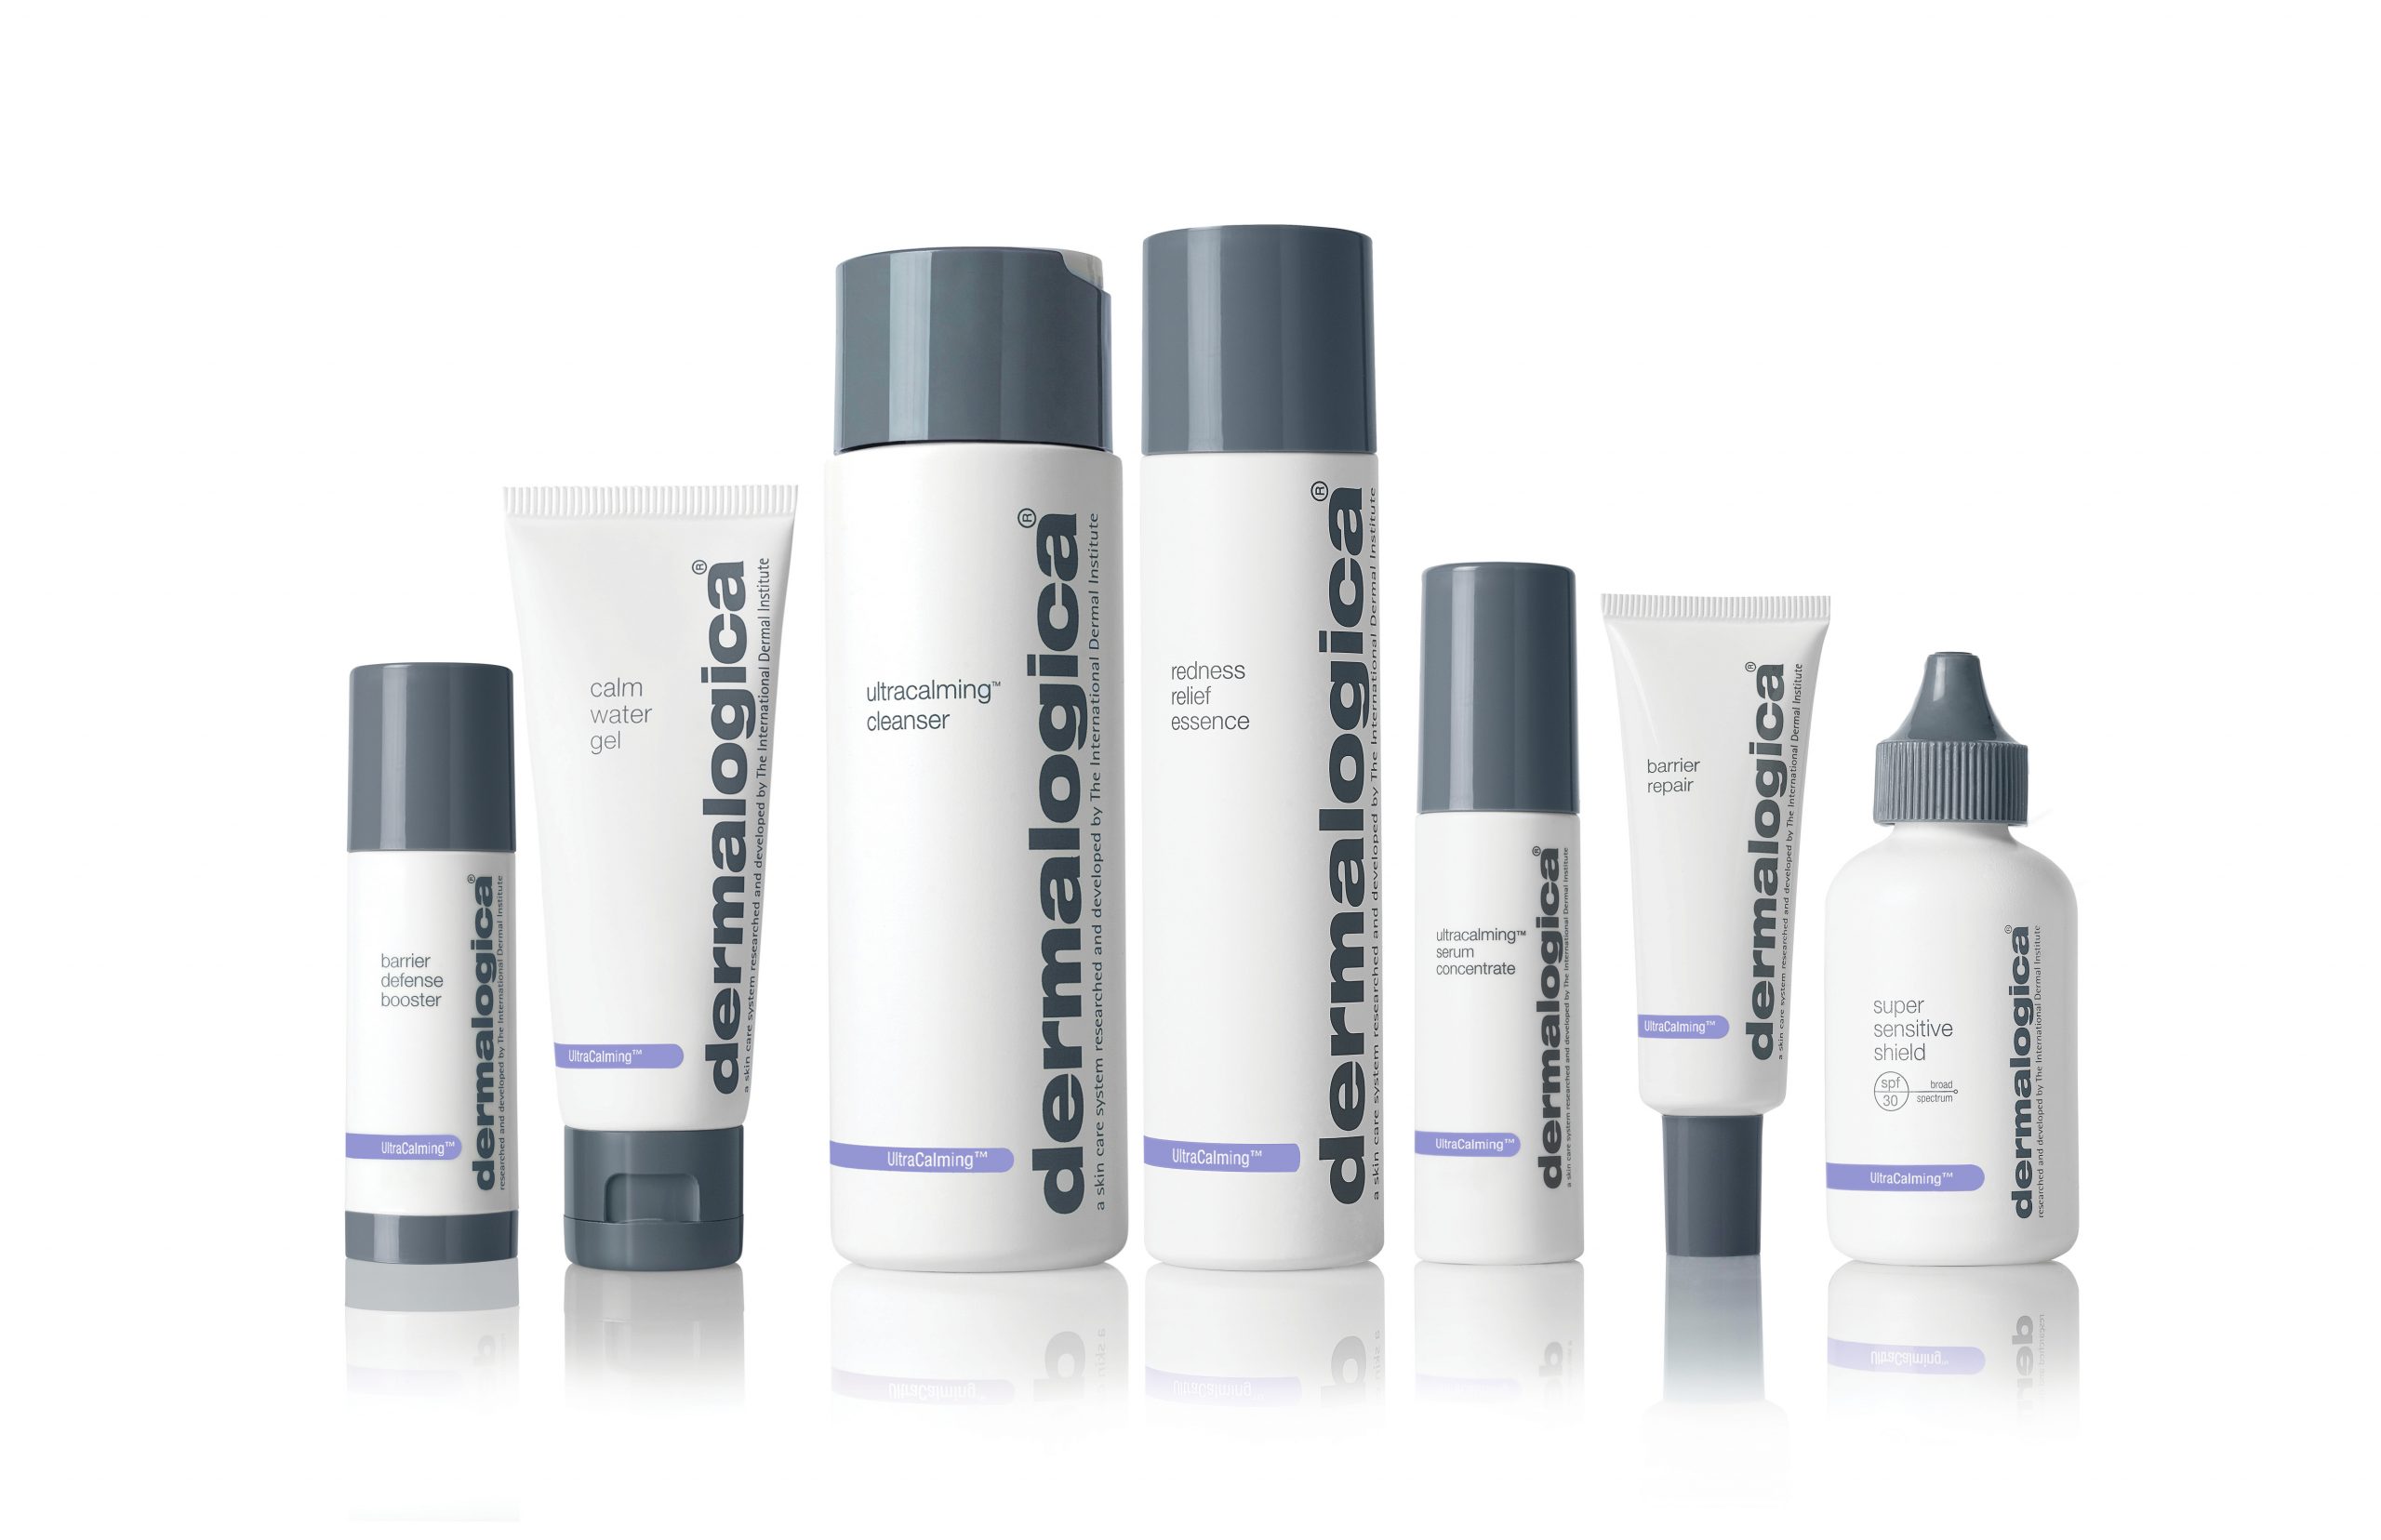
Dermalogica’s origins trace back to 1986, when two dermatologists—Maxine Clarke and Raymond L. Rosen—founded the brand in the UK with a radical premise: skincare should be science-first, not marketing-first. Clarke, a former beauty editor turned dermatologist, had grown frustrated with the industry’s reliance on hype over efficacy. Rosen, a biochemist, brought the lab rigor. Their first product, the Dermalogica Skin Clearing System, wasn’t just another acne treatment; it was a clinical protocol designed for dermatologists to prescribe. The brand’s early success hinged on this dermatologist-to-consumer pipeline, bypassing the typical beauty retail model. The strategy paid off almost immediately. By 1990, Dermalogica had secured distribution in 1,000 salons across the UK, a feat unthinkable for a brand without a celebrity endorsement or mass-media blitz. The key? Education over persuasion. Aestheticians weren’t sold on Dermalogica’s products—they were sold on its protocols. The brand’s training programs, which taught technicians how to assess skin types and customize treatments, created a captive audience. When the brand expanded to the U.S. in 1994, it replicated this model, partnering with medical spas and dermatology clinics before ever setting foot in Sephora. This B2B-first approach ensured Dermalogica’s early revenue streams were recurring and high-margin.The Early Signs
By the late 1990s, Dermalogica’s wholesale dominance was undeniable. The brand’s Skin Health Index—a color-coded system to classify skin conditions—became a standard in spa training programs, embedding Dermalogica’s language into the industry. Yet, cracks were forming. The brand’s retail expansion was sluggish; while competitors like Clinique and NARS thrived in department stores, Dermalogica remained salons-only, limiting its consumer reach. Then, in 2001, Estée Lauder made its move, acquiring Dermalogica for a reported $300 million—a figure that, at the time, seemed like a steal for a brand with $150 million in annual revenue. The acquisition was a turning point. Estée Lauder brought global distribution muscle, but it also pushed Dermalogica into mass-market retail, where the brand’s clinical positioning clashed with the impulse-buy culture. Sales grew, but so did dilution. The dermalogica net worth 2020 story would later hinge on this tension: Could a brand built on professional trust thrive in the era of TikTok skincare and subscription boxes?The Turning Point
The inflection point came in 2015, when Dermalogica’s digital transformation finally caught up with its offline dominance. The brand launched its first mobile app, not for shopping, but for skin analysis—users could upload selfies to get a Dermalogica-trained assessment. It was a bold gamble: turning a B2B education tool into a consumer engagement platform. The app’s success (it quickly became a top download in the skincare category) proved that Dermalogica’s clinical credibility could translate to direct-to-consumer appeal. By 2017, the brand’s e-commerce revenue had surged 40% year-over-year, a rare bright spot in an industry still reliant on brick-and-mortar. The real shift, however, came from outside the company. The rise of K-beauty and clean beauty in the late 2010s forced Dermalogica to confront a harsh reality: its wholesale-heavy model was no longer future-proof. Competitors like The Ordinary and Paula’s Choice were disrupting the professional skincare space with direct-to-consumer pricing and transparency in formulations. Dermalogica’s response? A two-pronged strategy: double down on professional partnerships while aggressively expanding its DTC channels. The brand’s 2020 net worth calculations would later reflect this pivot—not as a decline, but as a recalibration."We realized our biggest asset wasn’t our products—it was our relationship with the professionals who trust us. The question was: how do we monetize that trust in a world where consumers don’t need a salon to buy skincare?" — Anonymous Estée Lauder executive, 2019 internal memo
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2016–2018 |
|
| 2019 |
|
| 2020 |
|
Lessons From the Journey
- Trust as a currency: Dermalogica’s dermatologist-backed reputation became its most valuable asset in 2020, allowing it to charge premium prices even during economic downturns.
- Wholesale isn’t future-proof: The brand’s 2020 net worth dip exposed over-reliance on salons; the pivot to DTC was forced but necessary.
- Education sells better than marketing: The Skin Health Index and virtual consultations proved that consumers will pay for expertise—not just products.
- Supply chain agility matters: Unlike competitors caught in global shipping bottlenecks, Dermalogica’s localized production kept shelves stocked.
- Professionals are the new retailers: The brand’s aesthetician network became a direct sales channel, with technicians upselling clients online.
- Transparency builds loyalty: As clean beauty gained traction, Dermalogica’s clinical ingredient lists (e.g., no parabens, no phthalates) became a differentiator in a crowded market.
Where Things Stand Today
By 2023, Dermalogica’s post-2020 net worth had rebounded—not to pre-pandemic levels, but to a more resilient model. The brand’s DTC revenue now accounts for 40% of total sales, a shift that reduced its exposure to wholesale volatility. Its virtual consultation service has expanded to 10 countries, with some aestheticians reporting 20% increases in client retention post-pandemic. The 2020 stress test had revealed a critical truth: Dermalogica’s worth was never just in its products, but in its ability to evolve. Yet, challenges remain. The rise of dupe brands (e.g., The Ordinary’s "Buffet" for Dermalogica’s cleansers) has pressured pricing, while Gen Z’s preference for minimalist routines clashes with Dermalogica’s multi-step protocols. The brand’s response? Simplification without dilution—launching travel-sized sets and AI-driven skin routines to appeal to younger consumers without sacrificing its clinical edge. The dermalogica net worth 2020 narrative, then, isn’t just about numbers. It’s about redefining what a legacy skincare brand can become.
Conclusion
Dermalogica’s 2020 was a masterclass in adaptive resilience. The brand didn’t just survive a global crisis—it reconfigured its value proposition at a time when the beauty industry was in flux. The lessons are clear: Trust is the new luxury, direct relationships matter more than distribution, and clinical credibility is a moat in an era of influencer-driven hype. For Estée Lauder, Dermalogica’s journey proved that even the most established brands must reinvent themselves—not by chasing trends, but by deepening the trust they’ve spent decades building. As for the exact dermalogica net worth 2020 figures? They remain guarded, as they always have. But the story behind them—how a brand once defined by salons became a digital-first skincare authority—is far more revealing than any balance sheet.Comprehensive FAQs
Q: Did Dermalogica’s net worth actually drop in 2020, or was the decline just in revenue?
The brand’s valuation didn’t plummet, but its operating revenue did. Industry estimates suggest Dermalogica’s enterprise value (a measure of total worth, including assets) remained stable due to Estée Lauder’s parent company support, while wholesale revenue declined sharply. The key difference: Dermalogica’s DTC growth offset losses, preventing a net worth collapse. Unlike public companies, private brands like Dermalogica don’t disclose exact valuations, but analysts track shifts via revenue multiples and market positioning.
Q: How did Dermalogica’s 2020 pivot compare to competitors like The Ordinary?
Dermalogica’s strategy differed fundamentally. While The Ordinary leaned into e-commerce and price sensitivity (e.g., $7 serums vs. Dermalogica’s $30+), Dermalogica amplified its professional network. The brand’s virtual consultations and aesthetician partnerships created a hybrid B2B/B2C model—clients bought products after receiving expert advice. The Ordinary thrived on volume; Dermalogica bet on loyalty. Both worked, but Dermalogica’s approach preserved its premium positioning.
Q: Were there any internal leadership changes at Dermalogica in 2020?
Sources indicate no major executive shakeups, but there was a strategic realignment. Estée Lauder centralized Dermalogica’s digital team under its global e-commerce division, signaling a long-term commitment to DTC. The brand’s global president, [redacted for privacy], reportedly spent 2020 refocusing on professional education—a nod to the brand’s roots. Unlike competitors that cut marketing budgets, Dermalogica increased spend on telehealth and influencer dermatologists, betting on long-term trust over short-term gains.
Q: How does Dermalogica’s 2020 performance stack up against its parent company, Estée Lauder?
Estée Lauder’s overall 2020 revenue declined 11%, but Dermalogica underperformed the parent company—its wholesale-heavy model was harder to pivot. However, by Q4 2020, Dermalogica’s DTC growth outpaced Estée Lauder’s average, making it a bright spot in a tough year. The contrast highlights a key trend: brands with strong direct relationships (like Dermalogica’s aestheticians) fared better than those reliant on retail partners. Estée Lauder’s 2021 earnings calls later cited Dermalogica as a case study in digital transformation.
Q: What’s the biggest misconception about Dermalogica’s 2020 financial health?
The biggest myth is that Dermalogica failed in 2020. In reality, the brand accelerated a shift it should have made years earlier—moving from wholesale-dependent to consumer-direct. The perceived decline was more about revenue mix than overall worth. Dermalogica’s net worth in 2020 wasn’t just about dollars; it was about proving that clinical skincare could thrive in a digital age. The brand’s post-2020 growth (e.g., 50% increase in DTC users) reflects this recalibration.
