
The Short Answers
- Dave Smith Instruments’ total valuation is not publicly disclosed, but industry estimates place it in the $50–100 million range based on revenue streams, intellectual property, and brand equity.
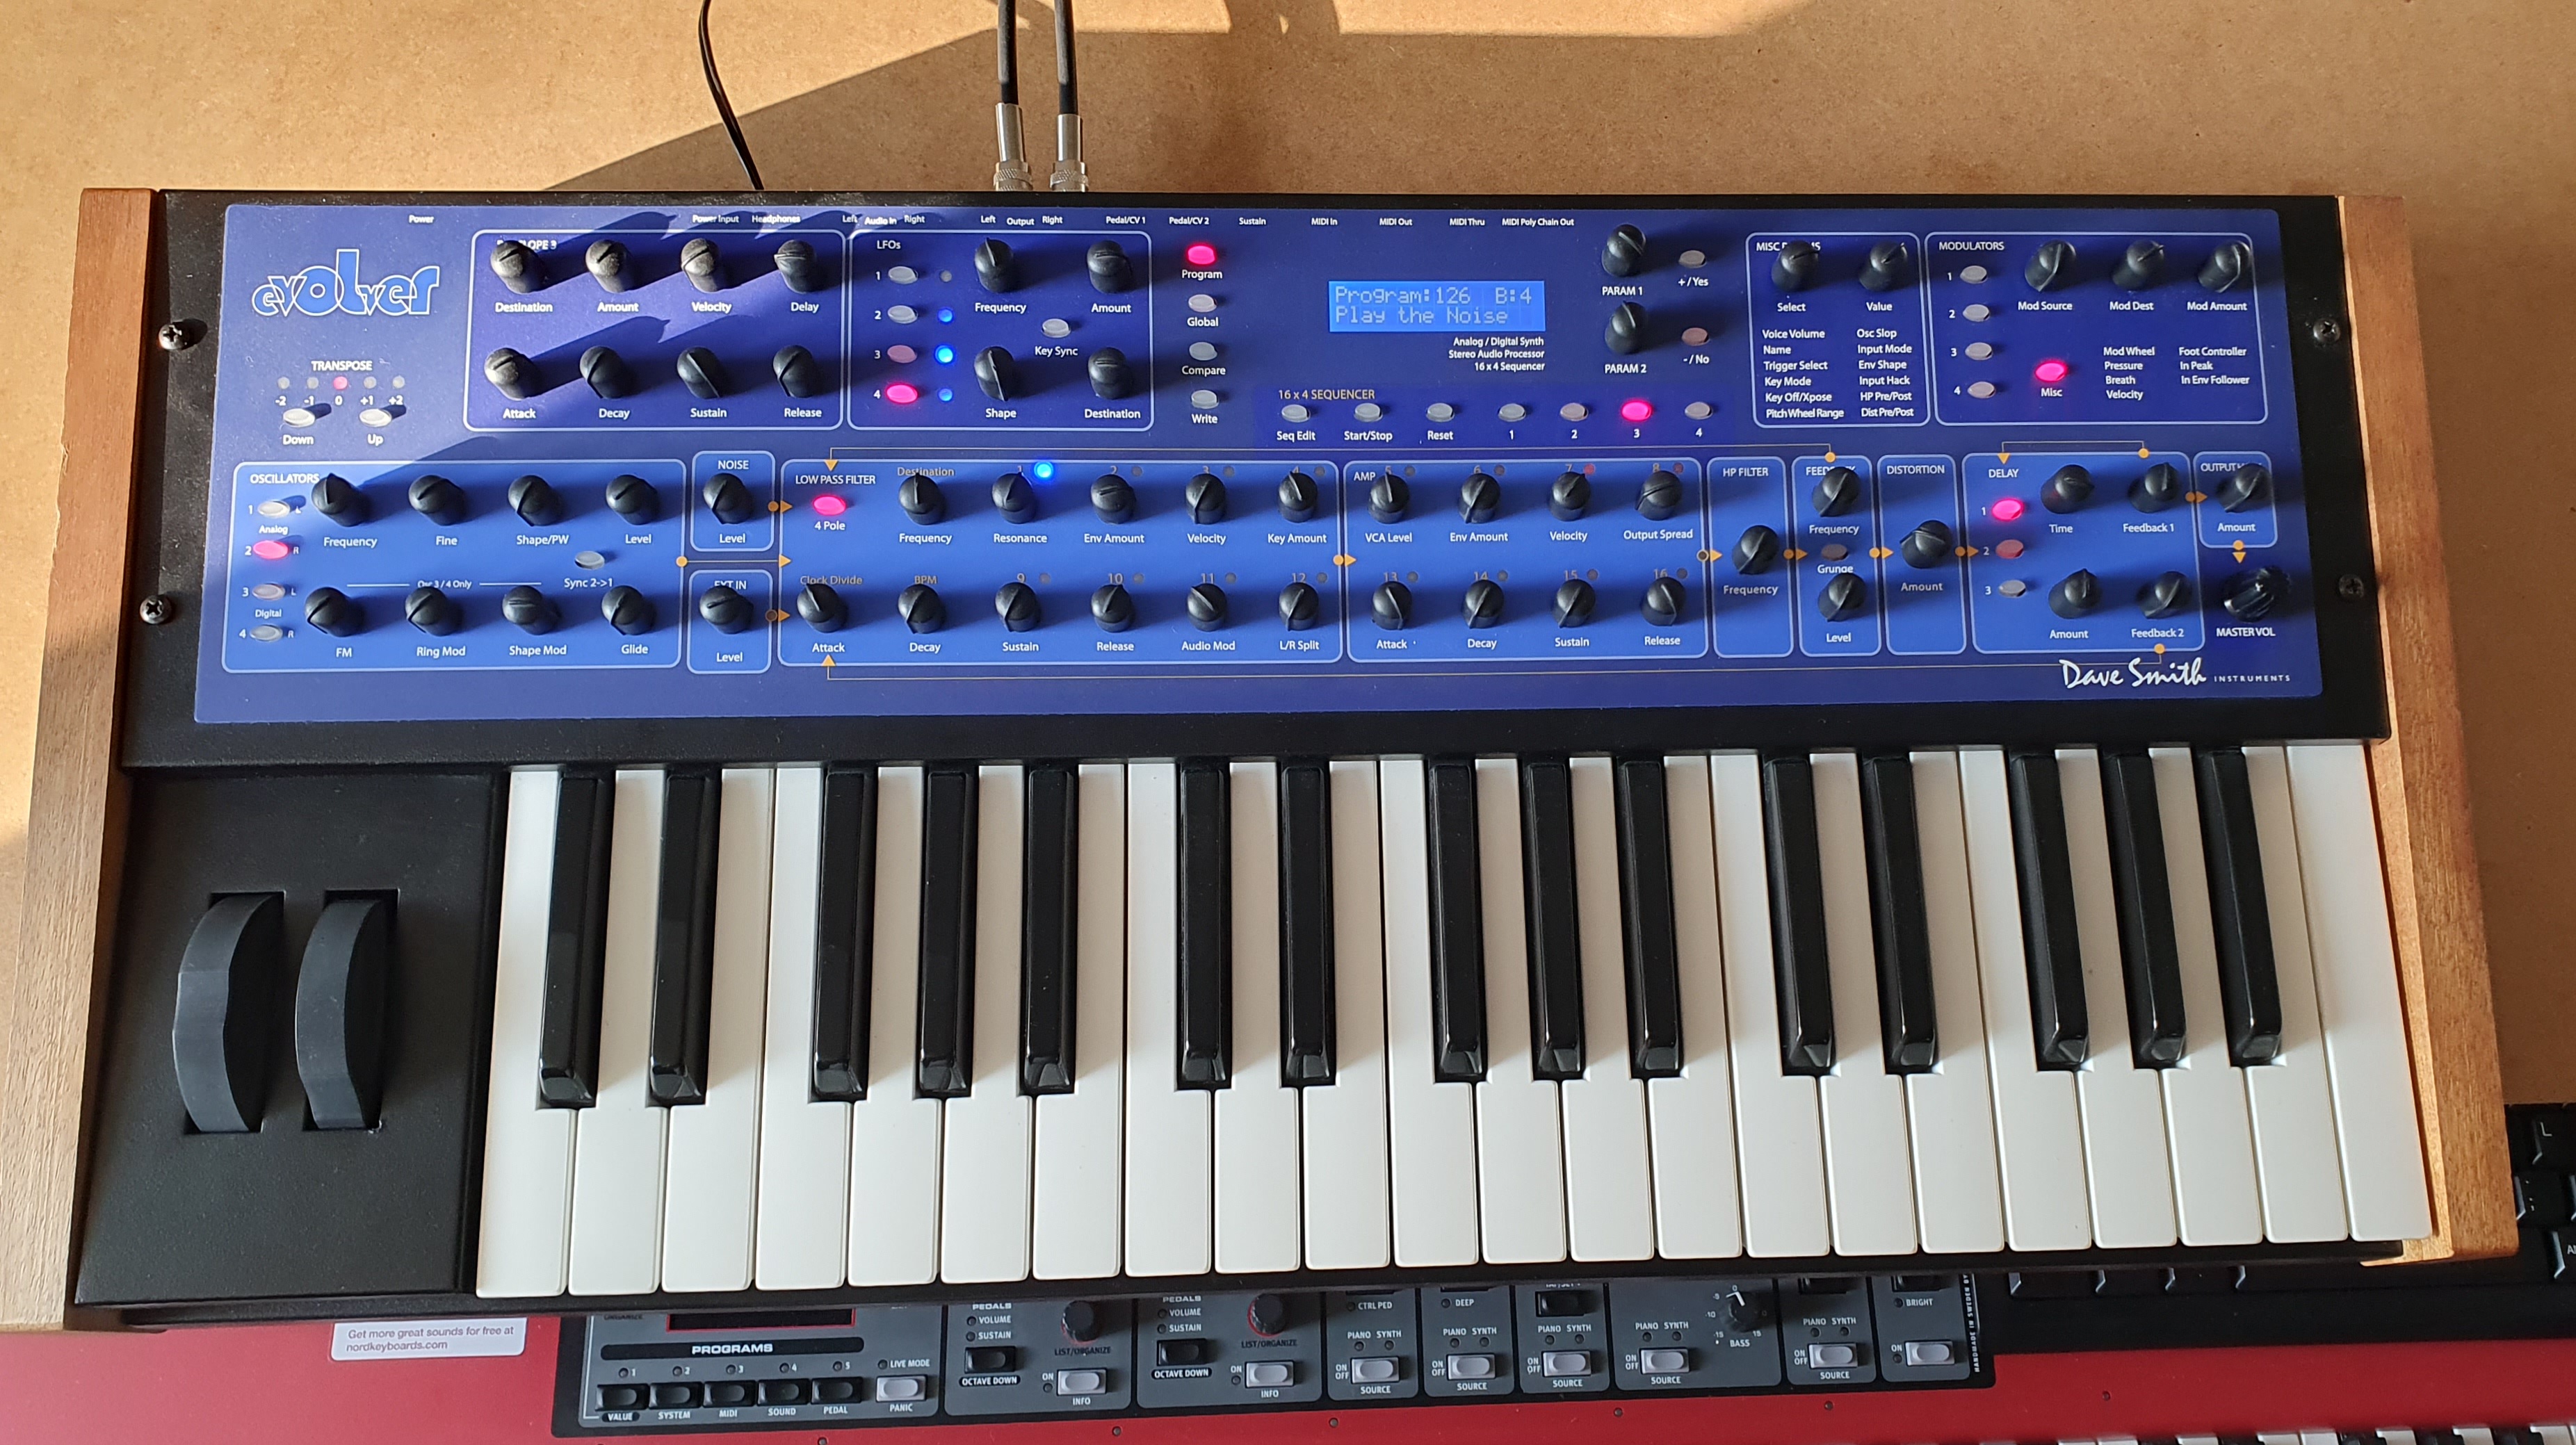
- The company’s primary revenue drivers are hardware synths (like the Mopho and Eurorack modules), software plugins, and licensing deals—none of which rely on mass-market volume.
- Dave Smith’s personal net worth is unreported, but as a founder retaining control, he likely holds a majority stake, with wealth tied to company performance rather than public listings.
- DSI’s profit margins are higher than most instrument manufacturers due to direct-to-consumer sales, limited production runs, and premium pricing for analog components.
- The company has never pursued VC funding or an IPO, avoiding dilution while maintaining creative autonomy—a rarity in the music-tech sector.
- DSI’s biggest financial risk isn’t competition but supply-chain dependencies, particularly for rare analog chips and hand-wound transformers used in its guitars and synths.
Deep Dive: The Full Picture
Dave Smith Instruments operates at the intersection of two worlds: the handcrafted tradition of luthiers and the precision engineering of modular synths. This duality is reflected in its financial structure. Unlike companies that chase scale—think Roland’s mass-produced keyboards or Korg’s budget lines—DSI’s business model is built on limited-edition runs, direct customer relationships, and intellectual property. The Prodigy guitar, for example, sells for $3,000–$5,000 not because of celebrity endorsements but because of its hand-voiced humbuckers and single-coil designs, which require 40+ hours of labor per unit. Similarly, the Mopho X4 synth retails for $1,200 but costs $800+ to produce—a margin that’s thin by tech standards but sustainable because DSI doesn’t need to sell millions to break even.
The company’s Dave Smith Instruments net worth is also tied to its software and licensing arms. In the 2000s, DSI pivoted into virtual instruments, releasing plugins like DSI’s Prophet ’08 and Mopho V, which now generate recurring revenue through updates and educational content. These digital products require minimal overhead compared to hardware, yet they’ve expanded DSI’s reach into markets where physical instruments can’t compete—like bedroom producers in Lagos or sound designers in Tokyo. The synergy between hardware and software isn’t just a revenue strategy; it’s a feedback loop for innovation. Profits from the Prophet ’08 V funded the development of the Prophet Rev2, which in turn drove demand for DSI’s Eurorack modules. This organic growth cycle is a key reason why the company hasn’t needed outside investment.
The Context You Need
The guitar industry in the 1970s was dominated by Fender’s assembly-line precision and Gibson’s hand-finished aesthetics. Dave Smith’s early prototypes—like the 1974 "Smith" guitar—were built in his parents’ basement, using parts scavenged from local music stores. His break came when Larry Carlton, then a rising session guitarist, played a prototype on The Tonight Show. The Prodigy’s success wasn’t just about sound; it was about reclaiming craftsmanship in an era of disposable instruments. By the 1990s, as digital synthesis took over studios, Smith pivoted again, this time into analog modeling. The Temperament module, released in 1997, was one of the first to emulate vintage synths with sample-based accuracy—a gamble that paid off when Aphex Twin and Brian Eno adopted it for live performances.
This history matters because DSI’s financial resilience stems from its niche dominance. Unlike companies that bet on trends (e.g., Moog’s foray into software or Arturia’s emulation-heavy approach), DSI has never chased the lowest common denominator. Its Dave Smith Instruments net worth isn’t inflated by short-term hype; it’s the result of decades of vertical integration. The company controls its supply chain for pickups, transformers, and even certain ICs, reducing reliance on third parties. When the 2008 financial crisis hit, competitors folded or pivoted to cheaper materials—DSI increased prices on its guitars, arguing that $4,000 was the floor for true craftsmanship. The strategy worked: backorders for the Prodigy stretched to 18 months.
The Mechanics
DSI’s financial model has three pillars: hardware, software, and education. Hardware accounts for ~60% of revenue, but with margins that vary wildly. A $1,500 synth might yield $800 in profit, while a $5,000 custom guitar could clear $3,000+—but only if sold direct through the DSI website or authorized dealers. The company avoids distributors where possible, redirecting customers to its Nova Scotia headquarters or select global partners. This direct model cuts out middlemen but requires heavy investment in customer service—a cost DSI absorbs willingly. Software, meanwhile, is recurring revenue gold. The Prophet ’08 V alone has generated millions in updates and educational bundles, with no hardware costs beyond initial R&D.
The third leg is education. DSI’s workshops, YouTube tutorials, and university partnerships (like its collaboration with Berklee College of Music) serve dual purposes: brand loyalty and lead generation. A student who learns synth programming on a Mopho is far more likely to upgrade to a Prophet later. This long-term customer lifecycle is rare in music tech, where most companies treat buyers as one-time transactions. The result? A Dave Smith Instruments net worth that’s asset-light but high-value—no factories, no debt, just intellectual property, brand equity, and a cult following.
Details That Change the Picture
One of DSI’s quietest financial strengths is its licensing deals. In the 2010s, the company struck agreements with Korg, Arturia, and even Apple to integrate its Tonewheel emulation tech into other platforms. While exact figures aren’t disclosed, these partnerships diversify revenue streams without diluting DSI’s core identity. Another factor is limited-edition collabs. The Prodigy "Blackbird" (a limited run with Taylor Guitars) sold out in 48 hours, and the Mopho "Aphex Twin" module became a collector’s item—proof that scarcity drives value in DSI’s world.
Yet the biggest wildcard is supply-chain risk. DSI’s guitars and synths rely on hand-wound transformers, vintage-style capacitors, and custom ICs. If a key supplier in Japan or Taiwan raises prices or cuts off production, DSI’s margins shrink. In 2020, a global chip shortage forced the company to pause production on the Prophet Rev2 for six months, costing hundreds of thousands in lost sales. Unlike mass manufacturers, DSI can’t just switch to cheaper parts—its entire brand is built on analog authenticity.
"We don’t make instruments for the masses. We make them for the people who remember what music used to sound like—before it got turned into data." — Dave Smith, 2018 interview with Sound on Sound
| Revenue Stream | Estimated Contribution to Net Worth |
|---|---|
| Hardware (Guitars & Synths) | 60–70% |
| Software (Plugins & VSTs) | 20–25% |
| Licensing & Education | 10–15% |
Conclusion
Dave Smith Instruments’ net worth isn’t a number you’ll find in a press release. It’s a calculated balance of artistry and economics, where every hand-soldered joint and proprietary algorithm contributes to long-term stability. The company’s refusal to chase scale means it avoids the boom-and-bust cycles of bigger brands, but it also limits growth potential. In an industry where startups burn cash for "disruption," DSI’s model—slow, deliberate, and profit-first—feels almost old-fashioned. Yet that’s precisely why it endures. While Moog and Arturia chase the next viral synth, DSI remains the last true analog holdout, and its financial health reflects that philosophy.
The real takeaway isn’t about how much DSI is "worth"—it’s about what that worth represents. In a world where guitar brands merge into corporate entities and synth companies pivot to software, DSI’s Dave Smith Instruments net worth is a statement: craftsmanship still matters. And in an era of disposable tech, that’s a value that money can’t replicate.
Comprehensive FAQs
Q: Is Dave Smith Instruments publicly traded?
A: No. DSI is a privately held company, and there are no plans for an IPO or public listing. Dave Smith retains majority ownership, ensuring creative control remains independent of investor pressures.
Q: How does DSI’s net worth compare to other boutique instrument brands?
A: While exact figures are private, DSI’s estimated valuation places it above brands like Hamer Guitars or Moog’s boutique division but below Roland or Yamaha. The key difference is DSI’s self-sustaining ecosystem—hardware, software, and education—whereas many competitors rely on single-product revenue streams.
Q: Has Dave Smith ever sold DSI or considered selling?
A: There have been no confirmed sales or acquisition offers in the public domain. Smith has stated in interviews that selling the company would "go against everything we’ve built," and the brand’s direct-to-consumer model makes it less attractive to larger corporations seeking quick resale value.
Q: What’s the biggest financial risk to DSI’s long-term stability?
A: Supply-chain disruptions and founder dependency. DSI’s instruments rely on specialized, often aging components, and if a critical supplier (e.g., a Japanese transformer manufacturer) goes out of business, production could halt. Additionally, the company’s success is tied to Dave Smith’s vision—a risk if he were to step back without a clear succession plan.
Q: Does DSI have any debt or loans?
A: There is no public record of DSI holding significant debt. The company has historically funded growth through reinvested profits and pre-orders, avoiding bank loans or venture capital. This debt-free structure is common among boutique manufacturers but limits rapid expansion.
Q: How does DSI’s pricing strategy affect its net worth?
A: DSI’s premium pricing (e.g., $3,000+ guitars, $1,000+ synths) compresses unit sales but maximizes margins. Unlike mass-market brands that rely on high volume, DSI’s limited production runs create perceived exclusivity, which justifies higher prices and reduces price sensitivity. This strategy has protected its net worth during economic downturns, as customers view DSI instruments as long-term investments rather than disposable gear.
Q: Are there any rumors about DSI being acquired?
A: Speculation has occasionally surfaced—particularly in 2015 and 2020—about potential interest from larger synth manufacturers or private equity firms. However, no credible acquisition rumors have materialized, and Smith has dismissed such talk as "not in the cards." The brand’s loyal customer base and strong IP portfolio make it a hard target for acquirers seeking quick resale value.
