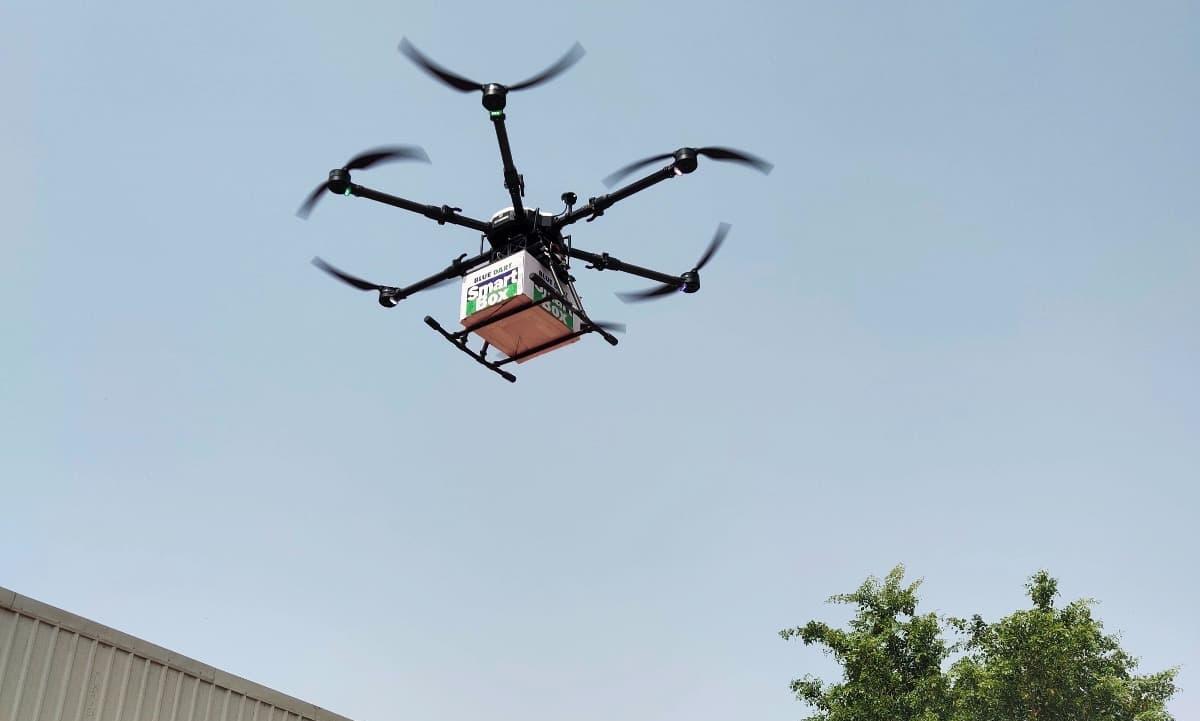
The Short Answers
- Dart Drones’ 2018 net worth was estimated between £50–£100 million, though exact figures were never confirmed.
- The company’s valuation fluctuated due to delays in FAA certification and shifting investor priorities in drone logistics.
- Dart’s tech focused on high-altitude cargo drones, a niche that required massive capital but saw limited early adoption.
- By 2019, the company’s financial trajectory became a cautionary tale for drone startups overpromising before proving viability.
Deep Dive: The Full Picture
Dart Drones emerged in the mid-2010s as one of the most aggressive players in the autonomous drone delivery space. Unlike consumer drone companies, Dart targeted commercial and industrial applications, where the barriers to entry were higher but the potential payoff was transformative. Its drones weren’t toys; they were designed to carry payloads of up to 50 pounds, operate beyond visual line of sight, and navigate complex airspaces—features that required not just engineering prowess but also regulatory approvals that were still years away. The company’s 2018 financial snapshot was a mix of promise and uncertainty. While it had raised capital from venture firms and corporate backers, the lack of a clear path to profitability meant its valuation was more about future potential than current revenue. Industry analysts noted that Dart’s valuation in 2018 was inflated by hype, a common pitfall for drone startups chasing the same vision as Amazon Prime Air or Wing. The difference? Dart’s drones were built for urban logistics, not rural deliveries, a segment with stricter airspace rules and higher operational costs.The Context You Need
By 2018, the drone industry had entered a funding frenzy. Companies were raising millions on the back of lofty claims about revolutionizing delivery, surveillance, and even disaster response. Dart was no exception, but its focus on high-altitude, long-range drones set it apart. The challenge? The Federal Aviation Administration (FAA) had yet to finalize Part 107 regulations for beyond-visual-line-of-sight (BVLOS) operations, leaving Dart in a limbo where its drones couldn’t legally operate at scale. This regulatory lag created a valuation paradox: investors bet on Dart’s future, but the company couldn’t yet demonstrate real-world success. The timing of Dart’s 2018 financial assessments was critical. This was the year when other drone startups—like Flytrex and Workhorse—began facing reality checks after burning through capital without clear revenue streams. Dart’s valuation, therefore, wasn’t just about its own performance but also about the broader industry’s credibility. If Dart could prove its drones were viable, it might justify its funding rounds. If not, it risked becoming another cautionary tale.The Mechanics
Dart’s business model relied on three pillars: hardware innovation, regulatory lobbying, and strategic partnerships. Its drones were engineered for endurance and payload capacity, but the real value proposition was in the software stack that enabled autonomous navigation. This was where the company’s valuation got tricky. Investors weren’t just paying for drones; they were betting on Dart’s ability to navigate airspace restrictions, a gamble that required both technical and political acumen. The mechanics of Dart’s 2018 valuation were opaque by design. Startups in this space often used private funding rounds to inflate valuations without disclosing exact figures. For Dart, this meant its net worth estimates were derived from secondary sources—venture capital filings, executive interviews, and industry leaks. The lack of transparency wasn’t malicious; it was a byproduct of a sector where competitive secrecy was as important as innovation. Yet this opacity made it difficult to separate hype from substance, a problem that would later plague Dart’s fundraising efforts.Details That Change the Picture
One often overlooked factor in Dart’s 2018 financial standing was its burn rate. While the company secured funding, it also spent aggressively on R&D, regulatory compliance, and talent acquisition. This meant that even if its valuation was high on paper, its operational runway was shorter than investors realized. By late 2018, whispers in Silicon Valley suggested Dart was reassessing its growth strategy, a sign that the initial valuation assumptions might have been overly optimistic. Another detail was Dart’s competitive positioning. Unlike Amazon or Alphabet’s drone projects, Dart wasn’t backed by a tech giant. This made its valuation more sensitive to market conditions. When investor interest in drone logistics waned in late 2018—partly due to high-profile failures in the space—Dart’s funding options narrowed. The company’s ability to secure follow-on rounds became a litmus test for its long-term viability."The drone industry in 2018 was a gold rush with no map. Dart had the vision, but the execution lagged behind the hype. Valuations were based on hope, not hard data." — Former venture capitalist tracking drone startups
| Key Metric | 2018 Estimate |
|---|---|
| Reported Valuation Range | £50–£100 million |
| Primary Funding Sources | Venture capital, corporate partnerships |
| Major Challenge | FAA BVLOS certification delays |

Conclusion
Dart Drones’ 2018 valuation was a snapshot of an industry at a crossroads. The company’s financial health wasn’t just about numbers; it was about whether the vision of autonomous drone logistics could survive the transition from lab to marketplace. By the end of the year, it was clear that Dart’s path was far from smooth. Regulatory hurdles, shifting investor priorities, and the sheer complexity of scaling drone operations had tempered early enthusiasm. The legacy of Dart’s 2018 financial chapter lies in what it revealed about the drone sector’s fragility. While some startups collapsed under the weight of unrealistic expectations, others—like Zipline—adapted by focusing on niche, high-impact applications. Dart’s story serves as a reminder that in high-tech industries, valuation and viability are often two different things. For every company that succeeds, there are others that fade into obscurity, their once-lofty net worth figures now footnotes in a larger narrative about patience, regulation, and the cost of innovation.Comprehensive FAQs
Q: Was Dart Drones profitable in 2018?
No. Like most drone startups at the time, Dart operated at a loss, relying on funding rounds to sustain operations. Its 2018 net worth was tied to future potential rather than revenue.
Q: Did Dart Drones go public or get acquired after 2018?
As of 2023, Dart Drones has not gone public or been acquired. The company continues to operate in the drone logistics space, though its financial status remains private.
Q: How did FAA regulations affect Dart’s valuation?
FAA delays in BVLOS certification created uncertainty, making it harder for Dart to demonstrate real-world success. This regulatory risk directly impacted investor confidence and valuation assumptions.
Q: Were there any major investors in Dart Drones in 2018?
Exact investor names were rarely disclosed, but Dart secured funding from venture capital firms and corporate backers interested in autonomous logistics. Some reports linked it to European investors as well.
Q: What happened to Dart Drones after 2018?
Post-2018, Dart shifted focus to partnerships and pilot programs, particularly in urban logistics. However, its growth slowed as the industry consolidated around fewer, more proven players.
