The Complete Overview of How to Calculate Your Net Worth Today—and at Retirement
Net worth calculation is deceptively simple on paper: subtract liabilities from assets. Yet the devil lies in the details—what counts as an asset, how to value illiquid holdings, and whether to include intangibles like education or professional skills. For example, a primary residence might be valued at market price, but if you’re upside-down on a mortgage, its contribution to net worth is negligible. Meanwhile, retirement accounts like 401(k)s or IRAs require careful estimation of future growth, which depends on contribution rates, employer matches, and investment performance. The same principles apply when projecting net worth at retirement, though the variables multiply: expected spending, healthcare inflation, and the timing of Social Security benefits all play pivotal roles. The stakes are higher than ever. A 2022 study by the Employee Benefit Research Institute found that only 21% of workers feel very confident about having enough savings to live comfortably in retirement. This lack of clarity stems from a failure to systematically track net worth over time. Without regular recalibration, even disciplined savers can drift off course—perhaps because they didn’t account for a career shift, rising debt, or unexpected expenses. The solution? A dynamic approach that treats net worth as a living document, not a static snapshot.Historical Background and Evolution
The concept of net worth traces back to medieval accounting practices, where merchants recorded assets and debts to assess solvency. By the 19th century, financial theorists formalized the idea as a measure of economic health, particularly for businesses. Personal net worth calculation gained traction in the 20th century as consumer credit expanded and retirement planning became a priority. The introduction of tax-advantaged accounts like IRAs in the 1970s and 401(k)s in the 1980s further complicated the equation, as these vehicles introduced new variables—contribution limits, vesting schedules, and withdrawal rules—that required sophisticated modeling. Today, digital tools have democratized net worth tracking, but the core methodology remains unchanged. Early adopters of personal finance software in the 1990s treated net worth as a quarterly review, much like a business would audit its balance sheet. Over time, the practice evolved to include real-time adjustments for market volatility, automated tracking of cryptocurrency holdings, and even projections for non-financial assets like a side business or rental property. The shift toward retirement-specific net worth calculations emerged in the 2010s, driven by concerns over longevity risk and the erosion of traditional pension plans.Core Mechanisms: How It Works
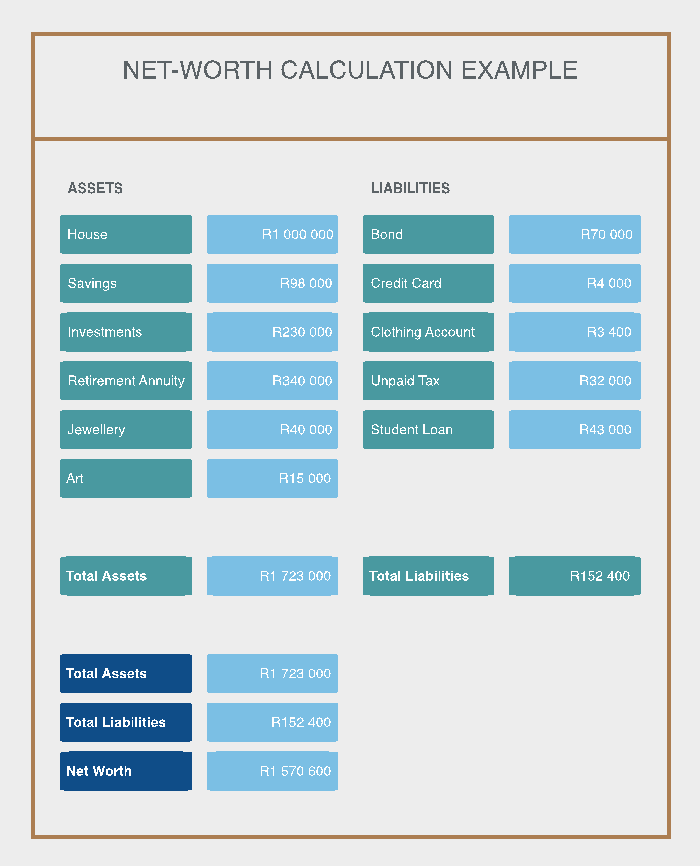
At its core, net worth is the difference between what you own and what you owe. Assets include cash, investments, real estate, and personal property (e.g., vehicles, jewelry), while liabilities encompass mortgages, student loans, credit card debt, and any other obligations. The challenge lies in valuation: a stock portfolio might be worth $500,000 on paper, but if it’s concentrated in a single company, its liquidity risk could reduce its effective contribution to net worth. Similarly, a home’s appraised value may not reflect its saleability in a slow market. When projecting net worth at retirement, the process becomes an exercise in financial forecasting. You’ll need to estimate: - Asset growth: Expected returns on investments, adjusted for inflation. - Debt payoff: Whether mortgages or loans will be cleared by retirement age. - Income streams: Social Security benefits, pensions, and withdrawals from retirement accounts. - Lifestyle costs: Housing, healthcare, and discretionary spending in retirement. The most accurate projections use Monte Carlo simulations, which run thousands of scenarios to account for market fluctuations. Tools like Vanguard’s retirement calculator or Fidelity’s planning tools incorporate these variables, but even they rely on user inputs—meaning your assumptions will dictate the outcome.Key Benefits and Crucial Impact
Understanding how to calculate your net worth today—and at retirement—isn’t just about crunching numbers. It’s about gaining control over your financial narrative. For high earners, it reveals whether aggressive investing or tax optimization is the better path; for middle-class families, it highlights whether student debt is derailing progress. The clarity extends to retirement planning, where knowing your projected net worth allows you to adjust spending, delay retirement, or pursue a passion project without fear of outliving your savings. The psychological impact is equally significant. A 2021 study in the Journal of Financial Therapy found that individuals who regularly tracked their net worth reported lower financial anxiety and higher goal-setting behavior. This isn’t surprising: when you know your numbers, you can make informed trade-offs. Should you take that equity out of your home to send a child to college? Can you afford to switch careers for a lower-paying but more fulfilling role? These decisions become easier when your net worth is a known quantity. > "Net worth is the silent partner in your financial life—it doesn’t speak, but it dictates every major choice you’ll make." > — *Carl Richards, financial planner and author of The Behavior GapMajor Advantages
- Clarity over uncertainty: Eliminates guesswork about your financial standing.
- Identifies leverage opportunities: High net worth may qualify you for better loan terms or investments.
- Retirement readiness check: Reveals whether your savings align with your goals or require adjustments.
- Debt management focus: Pinpoints high-interest liabilities that should be prioritized for payoff.
- Risk assessment: Helps gauge exposure to market downturns or unexpected expenses.

Comparative Analysis
| Current Net Worth Calculation | Retirement Net Worth Projection |
|---|---|
| Static snapshot of assets minus liabilities. | Dynamic model incorporating growth, inflation, and spending. |
| Focuses on liquidity and immediate obligations. | Prioritizes sustainability over time, including healthcare and longevity risks. |
| Tools: Spreadsheets, Mint, Personal Capital. | Tools: Vanguard, Fidelity, or custom Monte Carlo simulations. |
Future Trends and Innovations
The next decade will likely see greater integration of AI-driven net worth tracking, where algorithms adjust for behavioral biases—like emotional spending or procrastination on debt payoff. Platforms may also incorporate real-time updates for cryptocurrency and NFT holdings, which currently lack standardized valuation methods. On the retirement front, dynamic withdrawal strategies that adapt to market conditions (rather than fixed percentages) could become standard, reducing the risk of outliving savings. Another shift will be toward net worth as a lifestyle metric, not just a financial one. Future tools may factor in non-monetary assets—such as time freedom, health, or community ties—to provide a more holistic "wellth" score. This evolution reflects a broader trend: people no longer measure success solely by dollar signs but by the flexibility and security those dollars can provide.
Conclusion
Calculating your net worth today—and projecting it at retirement—is less about memorizing formulas and more about adopting a disciplined mindset. The process forces you to confront hard truths: Are you saving enough? Is your debt manageable? Will your assets stretch far enough? The answers may surprise you, but they’re essential for making informed choices. The alternative—flying blind—leads to regret, whether it’s realizing too late that you should’ve invested more or discovering in retirement that your savings won’t cover your needs. Start with a clear audit of your current assets and liabilities. Then, use historical data and conservative assumptions to model your future net worth. Update the projections annually, adjusting for life changes like marriage, career shifts, or inheritance. The goal isn’t perfection; it’s progress. By treating net worth as an ongoing conversation with your finances, you’ll avoid the pitfalls of static planning—and step into retirement with confidence, not fear.Comprehensive FAQs
Q: Should I include my home’s equity in my net worth calculation?
Yes, but only if you’re prepared to sell it. Home equity is an asset, but it’s illiquid—meaning it doesn’t contribute to your net worth unless you convert it to cash. If you’re upside-down on your mortgage, the equity may be zero or negative. For retirement projections, consider whether you’ll downsize or tap into home equity via a reverse mortgage.
Q: How often should I recalculate my net worth?
At minimum, review your net worth annually. More frequent checks (quarterly or bi-annually) are ideal if your financial situation is volatile—such as during a career transition, after a major purchase, or following a market downturn. Automated tools like Personal Capital or YNAB can simplify this process.
Q: What’s the biggest mistake people make when projecting retirement net worth?
Underestimating healthcare costs and inflation. Many assume Medicare will cover all expenses, but out-of-pocket costs for prescriptions, dental, and long-term care can erode savings quickly. Inflation also distorts spending projections—what costs $50,000 today may require $80,000 in 20 years. Use the 4% rule as a starting point, but adjust for your specific risk tolerance.
Q: Can I calculate net worth without knowing my exact debt balances?
You can estimate, but precision matters. For example, if you’re unsure about a student loan balance, use the highest possible figure to avoid overstating your net worth. Tools like the National Student Loan Data System (NSLDS) or credit reports can help fill gaps. For retirement projections, even rough estimates are better than nothing—but aim to refine them as you near retirement age.
Q: How do I account for assets like a side business or rental property?
Valuing these requires a mix of book value and market potential. For a side business, consider its net profit after expenses and growth trajectory. A rental property’s value depends on its current market rent, vacancy rates, and maintenance costs. Consult a professional appraiser if the asset is significant. In retirement projections, factor in whether you’ll sell the asset or rely on its income.
Q: Does my net worth need to grow every year to be on track for retirement?
Not necessarily. Net worth growth depends on your stage of life. Early in your career, debt (e.g., student loans) may cause your net worth to dip, even if you’re saving aggressively. Later, as you pay down debt and invest, growth should accelerate. The key is consistency—whether your net worth rises by 5% or 15% annually, what matters is that you’re progressing toward your goal.
Q: How do I handle volatile assets like cryptocurrency in my net worth?
Treat them as high-risk, illiquid assets. If you hold crypto, use its cost basis (what you paid) for conservative estimates, or a 30-day average price to smooth volatility. Avoid including unrealized gains until you’ve held the asset for at least a year. For retirement projections, assume a worst-case scenario (e.g., 50% loss) unless you’re confident in long-term holding.
Q: What if my net worth is negative? Is retirement still possible?
Yes, but it requires a strategic reset. Negative net worth often stems from high debt relative to assets. Focus on liquidating low-value assets, increasing income, or negotiating debt settlements. For retirement, prioritize debt-free living—whether through aggressive payoff or refinancing. Some may choose to work longer or adopt a frugal lifestyle to bridge the gap.
