Where It All Began
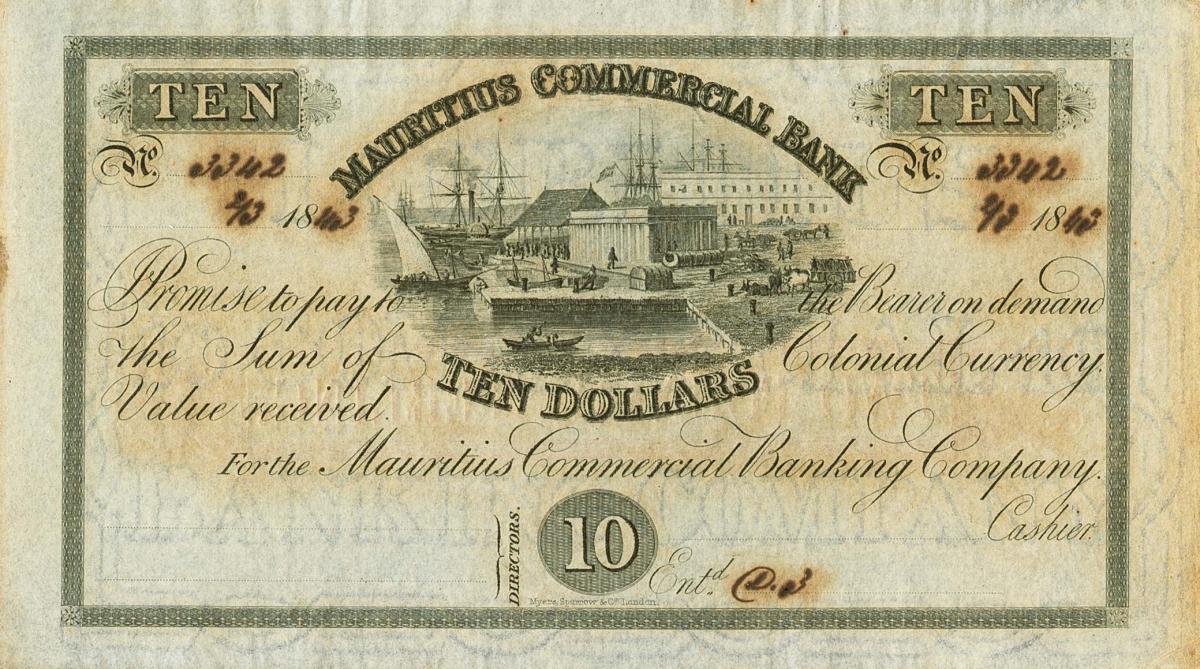
The origins of the MCB banknote story in 2013 trace back to a period of cautious optimism in Mauritius. The island nation, known for its stable democracy and business-friendly policies, had positioned itself as a gateway for African investments. MCB, as the country’s largest bank, was a cornerstone of this strategy, offering denominated currency notes not just for domestic transactions but also as a tool for non-resident investors. For many, purchasing MCB notes was a way to park funds in a currency perceived as resilient, especially against the backdrop of the 2008 financial crisis and the subsequent Eurozone debt struggles. The Mauritian rupee, pegged to a basket of currencies including the US dollar and the euro, provided a degree of stability that other emerging markets lacked. Yet, the appeal of MCB notes extended beyond mere stability. The bank’s notes were often seen as a liquid asset—easier to trade or exchange than physical gold or other commodities. In 2013, the Bank of Mauritius had relaxed some restrictions on foreign exchange transactions, making it simpler for individuals to hold and transfer MCB-denominated funds. This created a secondary market where notes could be bought and sold at prices that sometimes deviated from their face value. For those who acquired them in 2013, the initial assumption was that the notes would retain or even gain value over time, particularly if the Mauritian economy continued its upward trajectory. What they didn’t account for were the geopolitical and monetary shifts that would reshape the landscape by 2019.The Early Signs
The first signs of change emerged in 2014, as global oil prices began their precipitous decline. Mauritius, despite its diversified economy, was still vulnerable to commodity-linked remittances from its diaspora—particularly from the Gulf and Africa. The drop in oil revenues affected the rupee’s stability, and while MCB’s notes remained in circulation, their perceived value started to fluctuate. Investors who had bought MCB notes in 2013 began noticing that the secondary market was no longer as liquid as it had been. Some notes, particularly larger denominations, became harder to exchange at face value, and rumors circulated about the bank tightening its policies on note redemptions. By 2015, the situation had grown more pronounced. The Mauritian government, concerned about capital flight, introduced stricter controls on foreign exchange transactions. While MCB itself was not directly blamed, the broader regulatory environment made it more difficult for note holders to convert their assets into other currencies. This created a two-tier system: those who held notes for domestic use found them still functional, while those who had speculated on their exchange value faced uncertainty. The bank’s response was measured—it maintained that all notes remained valid, but the lack of transparency around redemption terms left many wondering whether their 2013 purchases would hold their worth by 2019.The Turning Point
The defining moment came in 2016, when the Bank of Mauritius announced a review of its foreign exchange policies. The move was framed as an effort to combat money laundering and illegal capital outflows, but the practical effect was a chilling one for MCB note holders. The bank began requiring more stringent documentation for large transactions, and in some cases, it imposed limits on how quickly notes could be exchanged. This was not a ban, but it was a signal: the era of treating MCB notes as freely tradable assets was over. For those who had bought them in 2013 with the expectation of easy liquidity, the shift was jarring. The turning point wasn’t just about policy, though. It was also about perception. As the Mauritian economy faced headwinds—slowing tourism growth, a drop in foreign direct investment, and rising public debt—the confidence in MCB’s notes as a "safe" asset began to erode. The bank’s stock price dipped, and while this didn’t directly affect the notes in circulation, it sent a message to investors. By 2017, the secondary market for MCB notes had all but dried up. Those who still held them were left with a question: would they be worth more in 2019, or had the regulatory and economic shifts rendered them a liability?"In 2013, we bought MCB notes thinking they’d be a steady store of value. By 2016, we realized the rules of the game had changed. The bank wasn’t the problem—it was the system around it." — An anonymous investor who held MCB notes from 2013
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2013 | MCB notes purchased as a hedge against rupee volatility. Secondary market active; notes traded at or near face value. Bank of Mauritius eases FX controls. |
| 2014–2015 | Oil price crash impacts remittances. MCB notes become harder to exchange at full value. Rumors of bank tightening policies emerge. |
| 2016 | Bank of Mauritius announces FX review. MCB requires documentation for large transactions. Secondary market collapses. |
| 2017–2019 | Notes remain valid but illiquid. Some holders convert to rupees; others hold as "dead money." MCB’s reputation recovers slightly, but trust in notes is damaged. |
Lessons From the Journey
- Regulatory shifts matter more than bank stability. Even a well-capitalized bank like MCB can’t insulate assets from government policy changes.
- Liquidity is not guaranteed in emerging markets. What seems tradable today may not be tomorrow.
- Currency notes are not just paper—they’re tied to the trust of the issuing institution and the broader economy.
- Diversification beyond banknotes was critical. Those who held only MCB notes faced higher risk than those with mixed portfolios.
- The secondary market is a double-edged sword. While it offers flexibility, its collapse can leave investors stranded.
- Timing is everything. Buying in 2013 was a gamble on stability; by 2019, the rules had changed.
Where Things Stand Today
As of 2019, the fate of MCB notes purchased in 2013 varied widely depending on how they were held. For those who had kept them as a long-term store of value and converted them back to rupees or foreign currency when possible, the outcome was mixed. The Mauritian rupee had depreciated against the US dollar by roughly 10% over the period, but inflation and economic growth had eroded some of that loss. Those who had speculated on the notes’ exchange value, however, found themselves in a tougher spot. The lack of a functional secondary market meant that selling notes at a premium was no longer an option, and the bank’s policies made large-scale conversions cumbersome. MCB itself had weathered the storm relatively well. The bank’s profitability remained strong, and its notes were still legally tender. However, the episode had left a lasting impression on investors. The days of treating MCB notes as a liquid, high-trust asset were over. By 2019, the bank had shifted its focus toward digital banking and foreign exchange services, signaling a move away from the physical note market. For those who had bought them in 2013, the lesson was clear: in an era of tightening capital controls and shifting economic priorities, even the most stable-seeming assets could become entangled in unforeseen risks.Conclusion
The story of those who acquired MCB banknotes in 2013 is a microcosm of the broader challenges faced by investors in emerging markets. It’s a tale of misplaced confidence, regulatory wake-up calls, and the harsh reality that financial instruments—no matter how reputable—are only as good as the environment they operate in. For some, the notes turned out to be a decent hedge; for others, they became a lesson in the fragility of assumed liquidity. What’s certain is that the experience reshaped how many investors viewed currency notes, not just in Mauritius but across the region. Today, MCB remains a key player in the Mauritian financial system, but the episode of 2013–2019 serves as a cautionary tale. The bank’s notes are still in circulation, but their role has evolved. The real takeaway isn’t just about the numbers—it’s about understanding that in finance, as in life, the only constant is change.Comprehensive FAQs
Q: Can I still exchange MCB notes purchased in 2013 for their full value in 2024?
As of 2019, MCB maintained that all notes remained valid, but the process for large exchanges became more stringent. By 2024, you would need to contact MCB directly to confirm current policies, as regulatory environments can shift further. Smaller denominations are typically easier to exchange, but expect documentation requirements.
Q: Did the value of MCB notes appreciate or depreciate between 2013 and 2019?
This depended on how the notes were held. For those who converted them to other currencies or rupees during the period, the effective value was influenced by exchange rate movements and inflation. Notes held as "dead money" (not exchanged) may have lost purchasing power due to inflation, though their face value remained intact. There is no public data on aggregate appreciation/depreciation.
Q: Were there legal risks associated with holding MCB notes during this period?
No direct legal risks emerged for holding the notes themselves, but the 2016 FX policy changes introduced indirect risks. Unauthorized trading or attempting to bypass redemption limits could have triggered regulatory scrutiny. Always consult a financial advisor familiar with Mauritian laws before making decisions.
Q: How did MCB’s stock performance compare to the fate of its banknotes?
MCB’s stock price experienced volatility during this period, particularly around 2016–2017, but it recovered by 2019. Unlike the notes, which were affected by liquidity and regulatory shifts, the stock reflected broader market sentiment. The two assets moved in parallel but were not directly linked—stocks are tradable securities, while notes are legal tender subject to central bank policies.
Q: Are there alternatives to holding physical MCB notes today?
Yes. MCB now offers digital banking solutions, foreign exchange services, and other financial products that may provide similar exposure without the liquidity risks of physical notes. Many investors now prefer these options due to the uncertainties surrounding note redemptions.
Q: What should someone consider before buying MCB notes today?
If you’re considering purchasing MCB notes now, assess the current regulatory environment, the bank’s liquidity policies, and your own need for flexibility. Physical notes may no longer offer the same advantages they did in 2013. Consult a financial expert familiar with Mauritian offshore banking to weigh the risks and benefits.
