The Short Answers
- Bill Demas’ net worth is estimated in the hundreds of millions, with Shopkick contributing a significant portion—though exact figures remain private.
- Shopkick was acquired in 2018 for reportedly around $200–300 million, but Demas’ stake’s value depends on equity terms and post-exit agreements.
- Demas’ wealth extends beyond Shopkick; he’s invested in other retail tech and venture funds, diversifying his financial exposure.
- The "bill demas shopkick net worth" debate hinges on whether the acquisition price reflected long-term growth potential or a fire-sale discount.
Deep Dive: The Full Picture
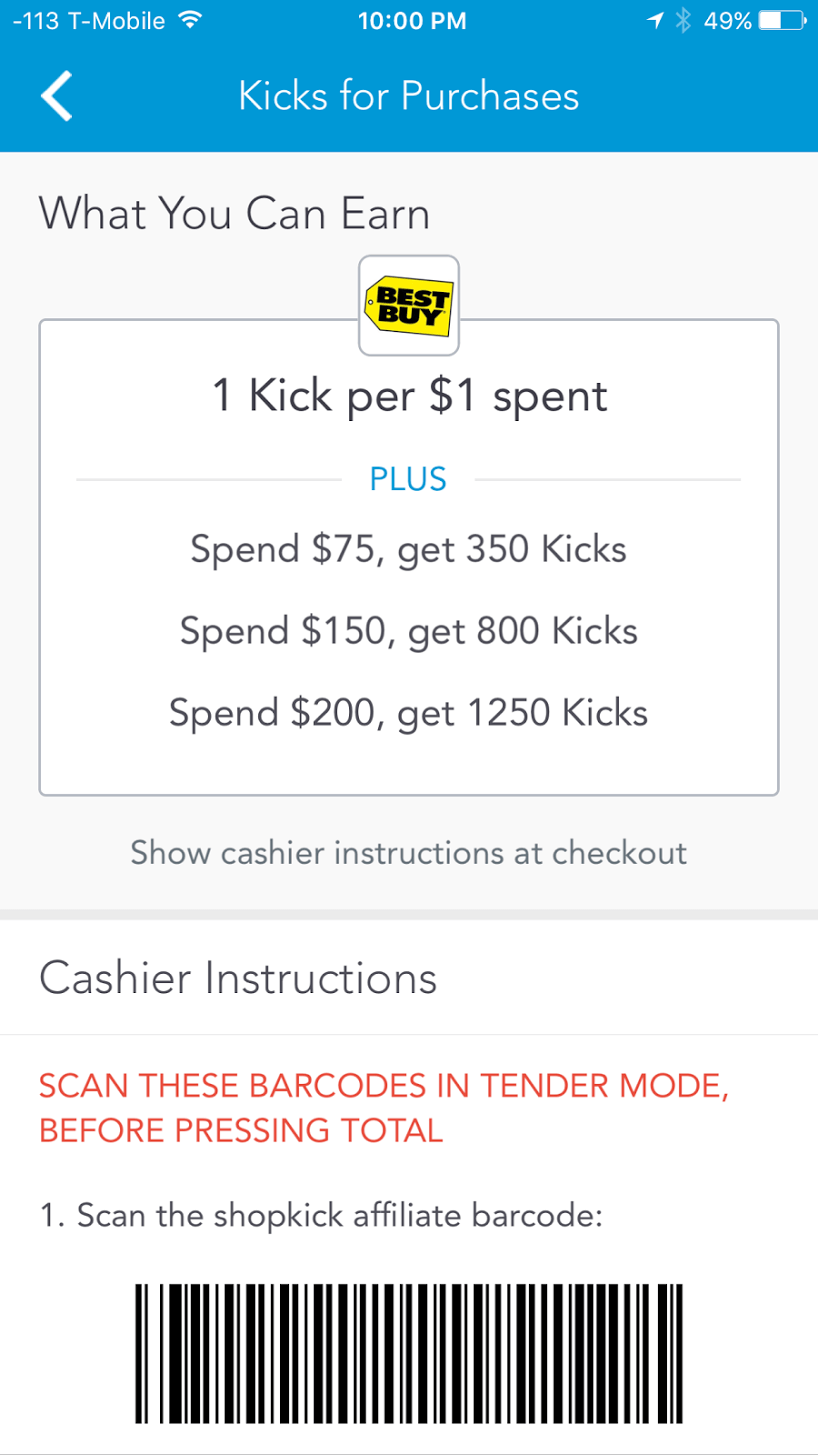
Shopkick’s story is a study in pivoting before failure. The company’s first iteration—where users earned "kicks" for visiting stores—was ahead of its time, but retailers were slow to adopt it as a primary marketing tool. By the mid-2010s, the mobile loyalty space had become crowded, with competitors like Foursquare (which rebranded as Swarm) and IBM’s Watson Analytics encroaching on its turf. Demas and his co-founder, Cyriac Roeding, recognized that the real opportunity wasn’t in consumer-facing apps but in the behavioral data Shopkick collected. That shift allowed them to reposition the company as a B2B engagement platform, selling tools to retailers to track foot traffic and personalize promotions.
The 2018 acquisition—often cited as the turning point for "bill demas shopkick net worth" discussions—wasn’t just about revenue. It was about proving that Shopkick’s data infrastructure had tangible value. The buyer, a private equity-backed retail media firm, saw potential in Shopkick’s ability to cross-reference offline store visits with online shopping behavior, a capability that became increasingly valuable as retailers raced to close the "last-mile attribution" gap. For Demas, this meant his equity was no longer tied to a struggling consumer app but to a niche asset with enterprise appeal. Whether that translated into a windfall depended on the terms of the deal, which—like most acquisition agreements—were structured to protect the buyer’s interests first.
#### The Context You Need
The retail tech boom of the 2010s was fueled by two forces: the decline of traditional loyalty programs and the rise of programmatic advertising for physical stores. Shopkick was one of the first companies to bridge that gap, offering retailers a way to measure in-store engagement in real time. But by 2017, the market had shifted. Investors were prioritizing AI-driven personalization and unified commerce—areas where Shopkick’s original tech was less competitive. The company’s decision to focus on B2B was a pragmatic move, but it also narrowed its addressable market. When the acquisition happened, it wasn’t because Shopkick was a cash cow; it was because the buyer saw synergies with its own data platforms. Demas’ role in this narrative is crucial. As a former retail executive (he’d worked at companies like The Gap and American Apparel), he brought institutional knowledge about what retailers actually needed—not just what consumers would use. That dual perspective helped Shopkick avoid the fate of many mobile startups: building a cool app no one paid for. Instead, it became a quietly profitable B2B tool, the kind of asset that appeals to private equity firms looking for recurring revenue streams. For Demas, the acquisition wasn’t just an exit; it was validation that his approach to retail tech had merit. ####The Mechanics
Here’s how "bill demas shopkick net worth" gets calculated—or at least, how it’s estimated: 1. Equity Ownership: Demas reportedly held a minority stake (likely in the 10–20% range) in Shopkick at the time of the acquisition. Exact percentages are unconfirmed, but venture-backed startups typically distribute equity to founders, employees, and investors in a way that rewards early risk-takers. 2. Acquisition Terms: The $200–300 million figure often cited for the 2018 deal is an all-cash or mixed-cash-equity valuation. If Demas’ stake was, say, 15%, his immediate payout would have been in the $30–45 million range. However, post-acquisition, his net worth would also include any earned-out payments (if the buyer had performance-based clauses) or royalties (if Shopkick’s tech remained under his influence). 3. Diversification: Demas hasn’t stayed idle. Post-Shopkick, he’s been involved in later-stage retail tech investments and advisory roles, which could have compounded his wealth through follow-on deals or board seats. His net worth isn’t just tied to one exit. 4. Opportunity Cost: The real question isn’t just what Shopkick was worth at acquisition, but what it could have been worth if the company had gone public or pursued a different growth path. Had Shopkick IPO’d in 2015–2016, Demas might have seen a multi-bagger return—but the retail tech IPO window was narrow, and Shopkick’s consumer model wasn’t yet proven at scale.Details That Change the Picture
The acquisition wasn’t just about money; it was about control. Shopkick’s buyer was a player in the retail media ecosystem, meaning Demas’ stake’s long-term value depended on how aggressively the new owners monetized the data. If Shopkick’s tech became a core part of the buyer’s platform, Demas might have retained influence—or at least, a seat at the table for future decisions. Conversely, if the acquisition was a fire sale (as some industry observers suggested), his stake could have been undervalued, leaving him with a lump sum but no ongoing equity upside.
What’s less discussed is the cultural shift at Shopkick. Demas and Roeding had built a company where employee equity was meaningful. If Shopkick’s acquisition included accelerated vesting for founders or rollover equity in the new entity, Demas might have secured additional upside. Without public disclosures, these details remain speculative—but they’re critical to understanding why "bill demas shopkick net worth" estimates vary so widely.
"The retail tech space in the 2010s was a gold rush with a map that kept changing. Shopkick’s real value wasn’t in the app—it was in the data. Demas understood that before most people did." — Former Shopkick investor (anonymous, 2023)
| Factor | Impact on "bill demas shopkick net worth" |
|---|---|
| Shopkick’s 2018 acquisition valuation | Base figure for stake value; likely $200–300M total. |
| Demas’ reported equity percentage | Estimated 10–20%; exact terms private. |
| Post-acquisition performance of Shopkick’s tech | If integrated well, could add earned-out payments or royalties. |
| Demas’ other ventures post-Shopkick | Diversified wealth; not solely dependent on one exit. |
| Market timing of the acquisition | Retail tech valuations peaked in 2015–2016; 2018 was a cooler market. |
Conclusion
Bill Demas’ story isn’t just about "bill demas shopkick net worth"—it’s about the hidden economics of retail tech. Shopkick’s acquisition proved that even "failed" consumer apps could have enterprise value if reframed as B2B tools. For Demas, the lesson was clear: the real money in retail tech isn’t in the app, but in the data and infrastructure behind it. Whether his Shopkick stake was a home run or a solid single depends on how you measure success. If the goal was liquidity, he likely walked away with a high seven-figure sum. If the goal was long-term wealth building, his post-Shopkick investments suggest he’s playing the game differently now.
The broader takeaway? In the world of private tech exits, net worth isn’t just about the headline number. It’s about leverage—how much of your stake you can turn into cash, how much you can reinvest, and how much you can control. Demas’ ability to pivot Shopkick from a consumer play to a B2B asset shows he understood that lesson early. For anyone tracking "bill demas shopkick net worth", the number is less important than the strategy that got him there—and the moves he’s making now.
Comprehensive FAQs
#### Q: How much did Bill Demas reportedly make from Shopkick’s acquisition?
A: Estimates suggest Demas’ stake in Shopkick’s 2018 acquisition could have been worth between $30–45 million, assuming he held around 15% equity and the deal closed in the $200–300 million range. However, exact figures are private, and his total net worth includes other investments.
####Q: Is Shopkick still operating under its original name?
A: No. Shopkick was acquired and rebranded as part of a larger retail media network. The original consumer app was either shut down or absorbed into the buyer’s platform, focusing on B2B tools for retailers.
####Q: Did Bill Demas retain any ownership after the acquisition?
A: There’s no public record of Demas holding ongoing equity in the post-acquisition entity. Most founder exits in private deals involve cash payouts and vesting acceleration, with limited rollover stakes unless negotiated separately.
####Q: How does Demas’ Shopkick net worth compare to other retail tech founders?
A: Compared to founders who took companies public (e.g., Rick Levin of Reebok or Ron Johnson of JC Penney), Demas’ wealth is more aligned with private exit founders like those behind Crate & Barrel’s e-commerce pivot or Urban Outfitters’ early investors. His net worth is substantial but not in the $1B+ range seen with IPO-backed founders.
####Q: What’s the biggest misconception about "bill demas shopkick net worth"?
A: The biggest mistake is assuming his wealth is solely tied to Shopkick. Demas has since invested in other retail tech ventures and advisory roles, diversifying his financial exposure. The "Shopkick windfall" is just one piece of a broader portfolio.
####Q: Could Shopkick’s tech be worth more today if it hadn’t been acquired?
A: Possibly—but retail tech valuations are cyclical. If Shopkick had gone public in 2015–2016 (when retail media stocks like Demandware were trading at high multiples), it might have fetched a higher valuation. However, the company’s niche B2B focus post-2016 made it a less attractive IPO candidate, and private acquirers often pay 20–30% less than public markets.
####Q: Are there any legal disputes or unresolved claims tied to Shopkick’s acquisition?
A: No major public disputes have been reported. Acquisitions of this nature typically include non-compete clauses and confidentiality agreements, which have kept any internal negotiations private.
