Breaking Down the Numbers
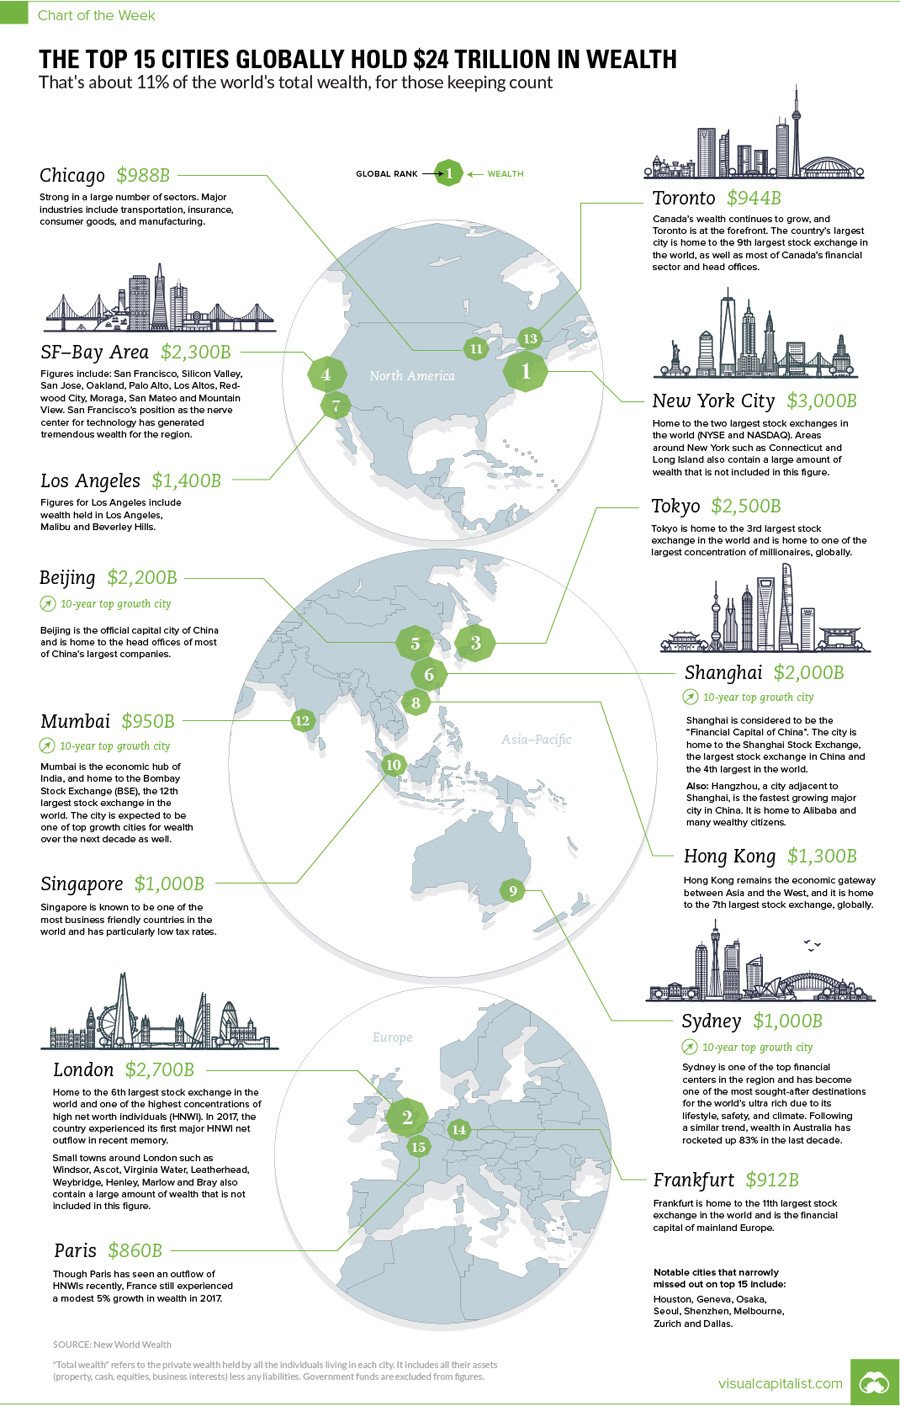 Australia’s wealth metrics are often discussed in tiers, not just binary labels. The net worth considered wealthy in Australia varies by source, but three broad brackets emerge from public data: the comfortable, the affluent, and the elite. The first group—those with net worth figures around AUD $1 million to $3 million—might own a home outright, have modest investments, and feel financially secure but not untouchable. They’re the backbone of Australia’s aspirational middle class, the ones who can afford a European holiday every few years but still check their superannuation balances with nervousness. The affluent, typically with net worth between $3 million and $10 million, operate in a different league. They’re the ones who can buy property in multiple states, fund private education without blinking, and access exclusive healthcare. Their wealth is liquid enough to weather market dips but tied up enough in assets to feel permanent.
The elite—those with net worth exceeding $10 million—move in a world where wealth is a tool, not a goal. Their concerns shift from tax minimisation to dynastic planning, from philanthropy to global mobility. For them, what constitutes wealthy net worth in Australia is less about the number itself and more about the options it unlocks: a second passport, a vineyard in Margaret River, or the ability to walk away from a boardroom without financial consequence. The Australian Securities and Investments Commission (ASIC) has observed that the ultra-wealthy in Australia are increasingly diversifying into private equity, timber assets, and even cryptocurrency—sectors where traditional wealth benchmarks don’t apply. Meanwhile, the Grattan Institute warns that the concentration of wealth in property and superannuation means most Australians are one bad investment away from feeling poor, regardless of their headline net worth.
The Verified Baseline
Publicly available data offers concrete starting points. The Australian Bureau of Statistics (ABS) defines the median household net worth in Australia as approximately AUD $1.1 million (as of 2022-23), though this masks vast regional disparities. In Melbourne and Sydney, where housing costs dominate, the median jumps to $1.8 million and $2.5 million, respectively. These figures are averages, not benchmarks—but they reveal why homeownership is Australia’s primary wealth-building tool. The Reserve Bank’s Household Expenditure Survey shows that households in the top 10% of wealth (net worth above $3.5 million) spend 40% more on education, healthcare, and financial services than the national average. This isn’t just about luxury; it’s about risk management. A family with net worth considered wealthy in Australia at this level can afford to self-insure against medical emergencies or send a child to an elite university without taking on debt. Tax filings provide another lens. The Australian Taxation Office (ATO) publishes anonymised data on the wealthiest 0.1% of taxpayers, those with net worth exceeding $25 million. These individuals account for just 0.001% of the population but hold 1.5% of total national wealth. Their portfolios often include directorships in ASX-listed companies, agricultural land, and international investments—assets that don’t appear in standard wealth surveys. The ATO’s data also highlights a generational divide: 58% of the ultra-wealthy are over 60, suggesting that wealth accumulation in Australia is still a slow, asset-driven process. For younger Australians, the path to what’s considered wealthy net worth in Australia now requires either high-income careers, entrepreneurial exits, or inheriting property portfolios—a trio of options that excludes most.What the Estimates Suggest
Private wealth managers and financial planners offer softer benchmarks, often tied to lifestyle outcomes rather than absolute numbers. Colonial First State’s Wealth Pulse Report suggests that net worth figures around $2 million to $5 million in capital cities allow for "financial independence"—defined as the ability to cover living expenses without depleting capital. This aligns with the "4% rule" (a global standard where withdrawals don’t exceed 4% of assets annually), but Australia’s higher cost of living adjusts the math. In regional areas, $1 million might suffice for a comfortable retirement, while in Sydney or Perth, $3 million is the new baseline. The catch? These estimates assume debt-free status—a rarity in Australia, where mortgage debt per capita is the highest in the world. The Australian Securities Exchange (ASX) notes that 30% of households with net worth above $1 million still carry mortgages, often on investment properties. Industry estimates also factor in liquidity. A $10 million net worth in Australia might sound elite, but if $8 million is tied up in illiquid assets (e.g., commercial real estate, art, or unlisted shares), the family’s actual spending power is closer to $2 million. Wealth managers like Per Capita and Equity Trustees warn that the true measure of wealth in Australia is "spendable net worth"—not just the balance sheet total. This explains why some Australians with high net worth on paper still stress over cash flow. The Australian Financial Review’s Rich List (published annually) reinforces this: the top 200 wealthiest Australians collectively hold $150 billion, but their spending habits vary wildly. A mining magnate with $3 billion might live frugally in a suburban home, while a media heir with $500 million splashes on multiple residences. The lesson? What net worth is considered wealthy in Australia depends less on the number and more on how it’s structured.Case Study: A Closer Look
Consider the case of Dr. Emily Chen, a 48-year-old cardiologist in Sydney’s North Shore. Her net worth is estimated at $4.2 million, but her financial reality is far from carefree. $2.5 million is tied up in her family home (valued at $3.8 million, with a $1.3 million mortgage), while $1 million sits in ASX-listed healthcare stocks and $700,000 in superannuation. Her liquid assets—cash, term deposits, and a small family trust—total $350,000. On paper, she’s affluent, but her monthly expenses (private school fees for two kids, a nanny, and healthcare premiums) eat into her liquidity. Chen’s story illustrates why net worth benchmarks in Australia are misleading without context. She can’t afford to retire early, despite her age, because her home equity is her largest asset—and illiquid. Chen’s situation mirrors broader trends. A 2023 report by Macquarie Group found that 60% of Australians with net worth between $2 million and $10 million face liquidity constraints, unable to access their wealth without selling assets. For Chen, the path to true wealth would require downsizing her home (a politically and emotionally charged move in Sydney) or diversifying into more liquid investments—neither of which aligns with her risk profile. Her case also highlights the generational wealth gap: Chen inherited her parents’ home (bought in 1995 for $280,000), which she leveraged to build her portfolio. For younger Australians without inherited property, reaching the same net worth requires higher income, entrepreneurship, or both."Wealth in Australia isn’t about the number—it’s about the options you can’t buy. If you’re still thinking about whether to sell the house to fund your child’s education, you’re not wealthy. You’re just rich on paper." — Simon Johnson, Head of Private Wealth at Per Capita| Factor | Estimated Impact on Net Worth | |--------------------------|------------------------------------------------------------------------------------------------| | Property Location | Sydney homeowner: +$1.5M–$2M vs. regional: +$500K–$1M (same asset class). | | Debt Leverage | Investment property loans: –$300K–$1M in liquidity, even if net worth rises. | | Superannuation Rules | Early access penalties: –$50K–$200K in forced withdrawals for medical/financial crises. |
What This Means Going Forward
 Australia’s wealth dynamics are being reshaped by three forces: demographics, technology, and policy. The aging population means more wealth is concentrated in older hands, while younger Australians face stagnant wages and record housing costs. The Australian Institute of Health and Welfare projects that by 2030, 25% of Australians will be over 65, increasing pressure on aged-care funding and inheritance patterns. Meanwhile, fintech and digital assets are creating new wealth tiers. The Digital Finance Analytics report estimates that Australians with crypto holdings (even small ones) have higher net worth volatility—their portfolios can swing ±30% annually, blurring the lines between wealth and risk. For traditional wealth managers, this is a challenge: how do you define "wealthy" when half of it is in volatile assets?
Policy will play a decisive role. The 2024 Federal Budget introduced stricter capital gains tax rules for property investors, while negative gearing reforms (proposed but not yet passed) could redefine how wealth accumulates. The Grattan Institute warns that without intervention, Australia’s wealth inequality will widen, with the top 1% capturing 40% of all new wealth created. For individuals, this means strategic planning is no longer optional. Those aiming for net worth considered wealthy in Australia must now consider:
- Diversification beyond property (private equity, global markets, or even timber or renewable energy assets).
- Tax-efficient structures (family trusts, self-managed super funds).
- Liquidity buffers—because even $5 million isn’t enough if it’s all tied up in one asset.
The message is clear: wealth in Australia is no longer static. What was wealthy net worth in 2010 ($2 million in Sydney) is now middle-class comfort. The bar is rising, and the tools to clear it are changing.
Conclusion
Australia’s wealth landscape is a paradox. On one hand, the country’s strong property market and superannuation system have created more millionaires than ever. On the other, rising costs and stagnant wages mean that what net worth is considered wealthy in Australia is becoming a moving target. The data shows that $1 million buys different outcomes in Brisbane than in Bondi Junction, and that $10 million doesn’t guarantee financial freedom if it’s locked in illiquid assets. For policymakers, this raises hard questions: Should wealth benchmarks be regionalised? Should the tax system reward liquidity over asset hoarding? For individuals, the takeaway is simpler: wealth in Australia is no longer about accumulation—it’s about adaptability. The future belongs to those who understand the difference between net worth and spendable wealth, who plan for volatility, and who accept that the old rules no longer apply. Whether you’re a first-home buyer, a property investor, or a high-net-worth professional, the question isn’t just how much you have—it’s how much you can use, when you need it most.Comprehensive FAQs
Q: Is $1 million enough to retire comfortably in Australia?
A: It depends on where you live. In regional areas or smaller cities, $1 million could fund a modest retirement (withdrawing $40K–$50K annually), but in Sydney or Melbourne, it would require downsizing or supplementary income. The 4% rule suggests $1 million generates $40K/year, but Australia’s higher cost of living means many retirees need $60K–$80K annually just to cover basics. Superannuation rules (like the $230K annual pension limit) also limit how much you can withdraw without tax penalties.
Q: How does property ownership affect what’s considered wealthy net worth in Australia?
A: Property is Australia’s primary wealth-building tool, but it distorts net worth metrics. A homeowner with $1.5 million in property might have only $200K in liquid assets, while a rentvestor with the same net worth could have $1 million in cash and investments. Negative gearing (where investment properties lose money but reduce taxable income) means some Australians appear wealthier on paper than they are in reality. The ABS notes that 65% of household wealth is tied to housing, making property the biggest single factor in whether someone is considered wealthy.
Q: Can you be wealthy in Australia without owning property?
A: Yes, but it’s far harder. High-income earners (doctors, lawyers, tech executives), entrepreneurs, and those with diversified portfolios (stocks, private equity, intellectual property) can achieve net worth considered wealthy in Australia without property. However, property provides leverage—most Australians use mortgages to amplify wealth, which isn’t possible with cash-only investments. The ASX’s *Wealth Report found that only 12% of Australians with net worth above $5 million don’t own property, compared to 40% in the $1M–$3M bracket.
Q: How does age affect wealth benchmarks in Australia?
A: Younger Australians (under 40) need higher net worth to feel secure because they have longer life expectancies, higher education costs, and less time to recover from market downturns. The ASIC’s MoneySmart data shows that Gen X (40–55) considers $2.5M wealthy, while Millennials (25–40) aim for $5M+ to account for future risks. Meanwhile, Baby Boomers (60+) often underestimate their wealth because they don’t account for home equity—a common mistake that leads to unnecessary downsizing in retirement.
Q: Does having a high net worth in Australia guarantee financial security?
A: No. Illiquid assets, high debt, and unexpected costs can derail even $10 million net worth. The Macquarie Wealth Report found that 30% of Australians with $5M+ face liquidity crises when large expenses arise (e.g., healthcare, school fees). Case in point: A Sydney-based family with $8M in property might struggle to pay for a child’s gap-year trip if they lack cash reserves. True financial security in Australia requires diversification, tax planning, and a liquidity buffer—not just a high balance sheet.
Q: How do wealth benchmarks differ between capital cities and regional areas?
A: Sydney and Melbourne require 2–3x the net worth of regional areas for the same lifestyle. For example: - Sydney: $3M+ for "wealthy" (due to $2M+ home values and higher living costs). - Brisbane/Adelaide: $1.5M–$2M suffices for comfort. - Regional (e.g., Hobart, Darwin): $800K–$1.2M can feel affluent. The ABS’s Regional Australia report shows that wealth inequality is 20% higher in cities than in rural areas, partly because property prices are the primary wealth driver. In regional areas, farming assets, small businesses, and superannuation play bigger roles.
Q: What’s the fastest way to reach "wealthy" net worth in Australia?
A: There’s no single path, but combining high income, property leverage, and entrepreneurship accelerates wealth growth. Common strategies include: 1. Career acceleration (medicine, law, tech, or finance—top earners hit $500K+ annually). 2. Property stacking (buying multiple investment properties with 100% financing). 3. Business ownership (exiting a startup for $5M+, or scaling a family business). 4. Superannuation boosting (salary sacrificing $50K/year to hit $1M+ faster). The Australian Tax Office notes that self-employed professionals and entrepreneurs reach $2M net worth 5–10 years faster than salaried workers, thanks to tax deductions and asset control. However, high risk comes with high reward—40% of wealthy Australians have experienced major financial setbacks (e.g., business failures, market crashes).
Q: How does wealth compare between Australia and other developed nations?
A: Australia’s wealth benchmarks are higher than the U.S. or UK but lower than Switzerland or Singapore when adjusted for cost of living. For example: - Australia: $2M–$3M = "affluent" in cities. - U.S.: $1M–$1.5M = "wealthy" (due to lower housing costs in many states). - UK: £1M–£1.5M (~$2M AUD) = "comfortable" (but London pushes this to £3M+). - Singapore/Hong Kong: $5M+ is entry-level elite (due to ultra-high living costs). The OECD’s *Wealth Distribution Report ranks Australia above the U.S. but below Nordic countries in wealth equality, meaning more Australians are middle-class, but fewer are ultra-wealthy. The key difference? Australia’s wealth is more tied to property, while U.S. wealth is more diversified (stocks, businesses, private equity).

