
The Short Answers
- The top 20% of Australians control 65% of net wealth, while the bottom 40% hold just 3%.
- Housing policies—like negative gearing and capital gains discounts—fuel wealth inequality by favoring investors.
- Wage growth has lagged behind productivity for decades, worsening the divide between executives and workers.
- Superannuation wealth is concentrated among high earners, with the top 10% holding ~40% of total funds.
- Regional disparities mean cities like Sydney and Melbourne see extreme wealth concentration, while rural areas face decline.
Deep Dive: The Full Picture
Australia’s wealth inequality is a product of deliberate policy choices. The tax system, for instance, treats capital gains and dividends more favorably than labor income. Negative gearing—allowing investors to deduct losses from rental properties—has inflated housing prices while offering little benefit to first-home buyers. These measures, justified as pro-growth, have instead reinforced asset concentration. The result? A society where wealth begets more wealth, while those without assets struggle to break even. The mining boom of the 2000s exacerbated the trend. While resource profits flowed to a small elite, wages for most Australians failed to rise proportionally. The boom also led to a construction bubble, with property prices soaring in cities like Sydney and Melbourne. Today, homeownership is out of reach for many under-40s, pushing them into long-term renting—a status that, in Australia, often means financial instability.The Context You Need
Australia’s wealth inequality isn’t a new phenomenon, but its scale is alarming. Historical data shows that by the 1980s, wealth distribution had already begun to skew toward the top. The 1990s saw further divergence as globalization and technological change favored skilled labor over unskilled workers. Yet the real inflection point came in the 2000s, when housing became the primary vehicle for wealth accumulation. The problem is compounded by Australia’s aging population. Older Australians—who control the majority of wealth—are living longer, meaning wealth remains concentrated in fewer hands. Younger generations, meanwhile, face stagnant wages and unaffordable housing, creating a generational divide. This isn’t just an economic issue; it’s a social one, with implications for everything from political stability to public health.The Mechanics
At its core, wealth inequality in Australia is driven by three key mechanisms: tax policy, asset ownership, and wage stagnation. The tax system is heavily skewed toward capital, with low rates on dividends and capital gains. This encourages investment in assets like property and shares, which appreciate over time, while wages—taxed at higher rates—fail to keep up. Housing is the most visible symptom. The top 10% of households own nearly half of all residential property, while the bottom 40% own just 3%. This isn’t just about prices; it’s about access. Policies like negative gearing and the capital gains tax discount (which applies to investments held over a year) make property a far more attractive investment than, say, a business or a career. The result? A self-reinforcing cycle where wealth begets more wealth, while those without assets struggle to accumulate any.Details That Change the Picture
The wealth inequality gap isn’t uniform across Australia. Cities like Sydney and Melbourne see extreme concentration, with the top 1% holding ~20% of total wealth. In contrast, regional areas often have more balanced distributions—but also face higher unemployment and lower wages. This geographic divide means that while the wealthy in capital cities benefit from asset appreciation, many Australians in rural and remote areas see little economic growth. Superannuation—Australia’s retirement savings system—further widens the gap. The top 20% of earners hold nearly 60% of all super funds, while the bottom 20% have barely any. This isn’t just about savings habits; it’s about starting salaries. Those who enter the workforce with higher incomes accumulate wealth faster, creating a permanent divide. The system, while well-intentioned, has become another tool for wealth concentration."The real tragedy is that Australia’s wealth inequality isn’t a result of bad luck—it’s the product of policies that deliberately favor the few over the many." — Dr. Richard Denniss, Economic Policy Director, Australia Institute
| Metric | Top 10% | Bottom 40% |
|---|---|---|
| Share of total wealth | ~50% | ~3% |
| Homeownership rate | ~90% | ~30% |
| Superannuation holdings | ~40% | ~1% |
| Average net worth (est.) | $3.5M+ | $50K-$100K |
Conclusion
Australia’s wealth inequality is not an accident—it’s the result of decades of policy choices that prioritize asset accumulation over wage growth. The consequences are clear: a shrinking middle class, generational inequality, and a society where opportunity is increasingly tied to wealth rather than effort. The question now is whether reform is possible. Taxing wealth more fairly, reforming negative gearing, and ensuring wages keep pace with productivity could all help—but political will remains the biggest obstacle. The alternative is a future where the divide deepens, where younger generations feel disenfranchised, and where the promise of a fair-go society rings hollow. Australia has the resources to address this crisis. What it lacks is the political courage to act.Comprehensive FAQs
Q: How does Australia’s wealth inequality compare to other developed nations?
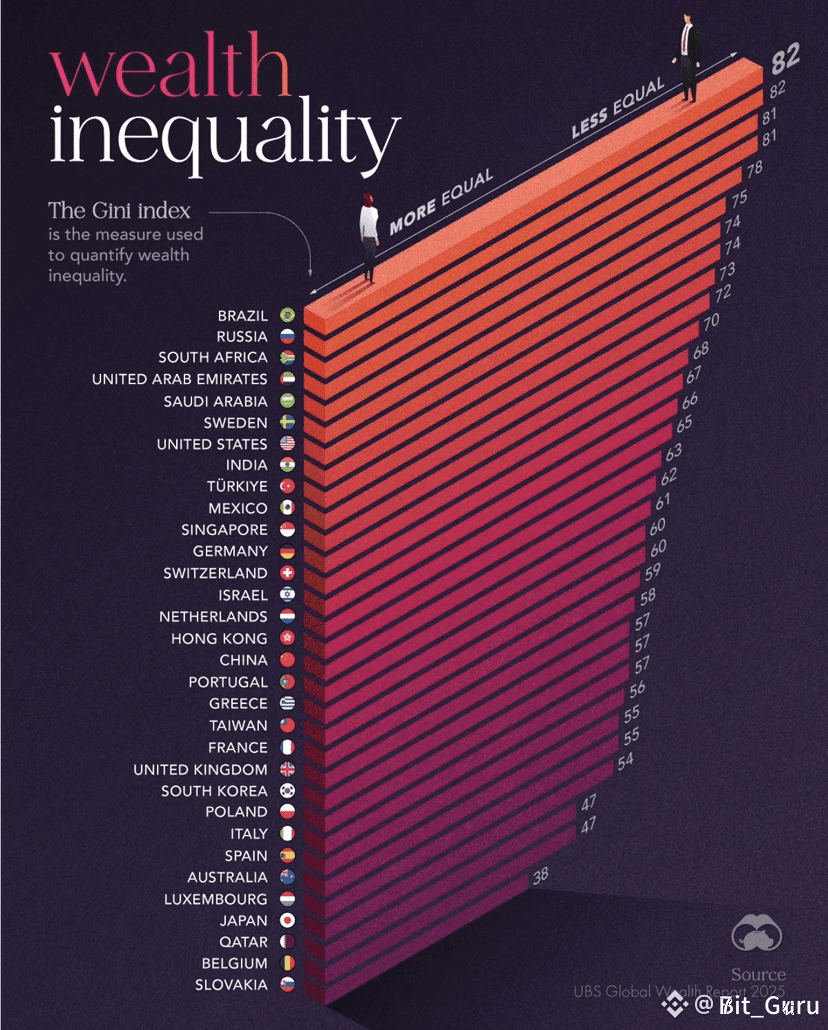
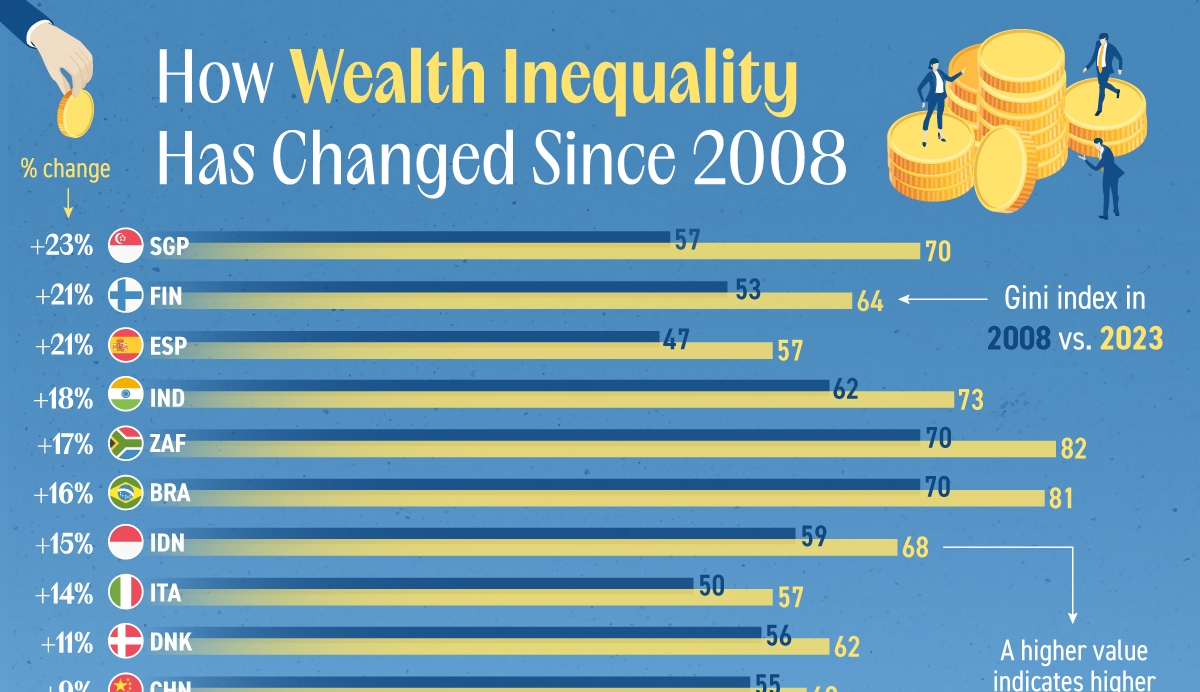
Australia’s wealth inequality is higher than in many European countries but lower than in the U.S. The Gini coefficient—a measure of income inequality—places Australia around 0.35, similar to Canada and the UK, but higher than Nordic nations. However, wealth inequality (not just income) is more extreme, with Australia’s top 1% holding a larger share of total assets than in most of Europe.
Q: Why does housing play such a big role in wealth inequality?
Housing is Australia’s largest asset class, and policies like negative gearing and capital gains discounts make property investment far more attractive than other forms of wealth accumulation. The result? A system where the wealthy get richer through asset appreciation, while renters and first-home buyers struggle to enter the market. This isn’t just about prices—it’s about policy design.
Q: Could wage growth reduce wealth inequality?
Yes, but Australia’s wage growth has lagged behind productivity for decades. Stronger unions, minimum wage increases, and policies that link wages to inflation could help—but without broader tax and housing reforms, the impact would be limited. The real solution requires addressing both income and asset distribution.
Q: Are there any policies that could help close the gap?
Several reforms could make a difference: tightening negative gearing rules, taxing wealth more progressively, expanding public housing, and ensuring superannuation benefits are more evenly distributed. However, political resistance—particularly from property owners and high-income earners—has stymied meaningful change.
Q: How does regional inequality factor into Australia’s wealth divide?
Regional disparities are significant. Cities like Sydney and Melbourne see extreme wealth concentration, while rural and remote areas face higher unemployment and lower wages. This geographic divide means that while the wealthy in capital cities benefit from asset growth, many Australians in regional areas see little economic participation. Closing this gap would require targeted investment in infrastructure and local economies.
Q: What are the long-term consequences of unchecked wealth inequality?
The risks include social unrest, political polarization, and economic stagnation. Historically, societies with extreme wealth gaps face lower social mobility, higher crime rates, and weaker public services. Australia’s current trajectory suggests these risks are growing—unless meaningful reforms are implemented.
