
The Short Answers
- Apple’s net worth after their first year as a public company (1980–1981) was estimated at $1.2 billion, though exact figures vary due to market volatility.
- The valuation was driven by speculative trading and the hype around the Apple II, not actual earnings—profits were minimal in those early years.
- Apple’s IPO structure (a direct public offering) was unusual at the time, allowing founders to retain more control but also exposing the company to market swings.
- The first-year valuation set a precedent for tech IPOs, proving that hardware innovation could command premium valuations.
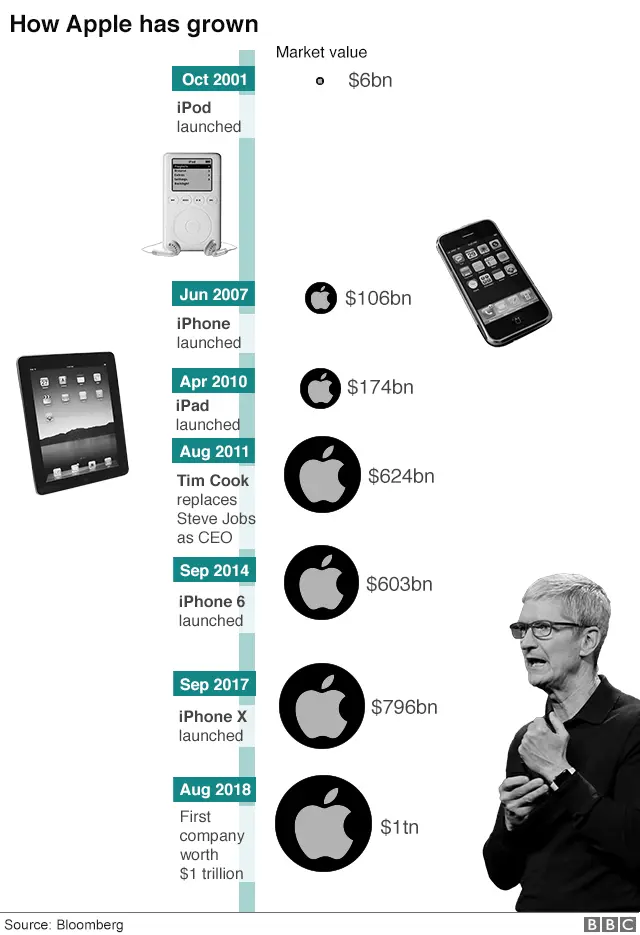
- Today, Apple’s net worth after their first year would be dwarfed by its current market cap—but the 1980 IPO was a turning point for Silicon Valley.
Deep Dive: The Full Picture
Apple’s debut on the NASDAQ in December 1980 wasn’t just an IPO—it was a cultural moment. The company had been privately held for five years, operating out of a garage-turned-factory in Cupertino. When it went public, the offering price was set at $22 per share, but demand was so fierce that the stock opened at $29—an instant 32% jump. By the end of the first trading day, Apple’s net worth after their first year had ballooned to an estimated $1.2 billion, making it one of the most successful tech IPOs in history. Yet the real story wasn’t the money. It was the signal: a tech company could be as valuable as a blue-chip corporation. The market’s reaction wasn’t just about Apple’s balance sheet. It was about the Apple II, a computer that had sold over 100,000 units by 1980 and was now positioned as the future of personal computing. Analysts at the time compared it to the IBM PC, but Apple’s advantage was its user-friendly design and vibrant third-party ecosystem. The company’s first-year net worth reflected not just its current sales but the belief that it could dominate the emerging home-computer market. That belief was so strong that some investors treated Apple stock like a speculative asset, buying shares not for dividends but for the potential of future growth.The Context You Need
To understand why Apple’s net worth after their first year mattered so much, you have to look at the tech landscape of the late 1970s. Personal computers were still a novelty, and most investors saw them as a hobbyist’s tool rather than a mainstream product. Companies like Atari and Commodore were profitable, but they weren’t valued like traditional industries. Apple changed that. Its IPO came at a time when Silicon Valley was transitioning from a collection of garage startups to a serious economic force. The net worth after their first year wasn’t just a financial metric—it was proof that tech could be both a business and a cultural phenomenon. The timing was also critical. The U.S. economy was recovering from the 1970s oil crisis, and consumer electronics were becoming more accessible. Apple’s marketing—with its iconic "1984" ad just a few years later—reinforced the idea that its products weren’t just tools but status symbols. The company’s first-year valuation was a reflection of that cultural shift: investors weren’t just betting on a company; they were betting on the future of computing itself.The Mechanics
Apple’s IPO wasn’t a traditional underwritten offering. Instead, it used a direct public offering (DPO) model, where the company sold shares directly to investors without an underwriting bank. This was risky—there was no guarantee of a smooth debut—but it allowed Apple to retain more control and avoid the fees that underwriters typically charge. The strategy paid off in the short term, with the stock surging on day one. However, the lack of underwriting also meant that Apple had to manage its own investor relations, which proved challenging as the stock became volatile. The net worth after their first year was further inflated by speculative trading. Many early investors treated Apple stock like a lottery ticket, buying shares in the hopes of flipping them for a quick profit. This created artificial demand, pushing the valuation higher than fundamentals alone would justify. By the end of 1981, the stock had settled into the mid-$20s range, but the damage was done: Apple had proven that tech stocks could be both high-risk and high-reward. The lesson for future startups was clear—if you could create enough hype, the market would reward you with a premium valuation, even if profits were still years away.Details That Change the Picture
Apple’s first-year net worth wasn’t just about the stock price. It was also about the company’s operational realities. Despite the market’s enthusiasm, Apple was still a young company with thin margins. The Apple II was profitable, but the company was burning cash on R&D, marketing, and expansion. Steve Jobs, then in exile from the company, later criticized the board for overvaluing the company based on hype rather than substance. The net worth after their first year was, in many ways, a house of cards—built on speculation, not fundamentals. Yet that speculation had real-world consequences. The influx of capital allowed Apple to accelerate its growth, hiring more engineers and expanding its product line. It also attracted attention from competitors, who saw the Apple II’s success as a threat. Within a few years, IBM would enter the personal computer market with its own machine, forcing Apple to adapt. The first-year valuation wasn’t just a financial milestone; it was the beginning of a tech arms race that would define the 1980s."The Apple IPO wasn’t just about money. It was about proving that technology could be cool—and that cool could be worth billions." — Mike Markkula, Apple’s early investor and board member
| Metric | 1980–1981 Figures |
|---|---|
| IPO Offering Price | $22 per share (opened at $29) |
| Estimated Market Cap After First Year | $1.2 billion (adjusted for inflation: ~$4.5 billion today) |
| Apple II Units Sold (1980) | Over 100,000 (driving early revenue) |
| Net Income (1980) | $47 million (on $117 million revenue) |
| Founders’ Stake Post-IPO | Steve Jobs retained ~7 million shares (~10% ownership) |
Conclusion
Apple’s net worth after their first year was more than a financial stat—it was a cultural reset for the tech industry. The IPO didn’t just raise money; it redefined what a tech company could be. Before 1980, software and hardware were seen as niche markets. Afterward, they became the foundation of a new economy. The first-year valuation wasn’t sustainable by traditional metrics, but it didn’t matter. The market had spoken: innovation could be worth more than profits. Today, Apple’s market cap is measured in trillions, but the lessons from 1980 remain. The company’s early success wasn’t just about the Apple II—it was about the power of perception. Investors didn’t just buy stock; they bought into a vision. That same dynamic plays out today with AI startups, electric vehicle makers, and other high-growth sectors. Apple’s net worth after their first year wasn’t an anomaly—it was the first act in a story that would change the world.Comprehensive FAQs
Q: How did Apple’s IPO structure differ from today’s tech IPOs?
A: Apple’s 1980 IPO used a direct public offering (DPO), selling shares directly to investors without underwriting banks. Today’s tech IPOs typically involve underwritten offerings, where investment banks guarantee a minimum price and take a cut of the proceeds. Apple’s model was riskier but allowed founders to retain more control—though it also meant the company had to manage its own investor relations.
Q: Was Apple actually profitable in its first year as a public company?
A: Yes, but just barely. Apple reported $47 million in net income in 1980 on $117 million in revenue. However, the company was still burning cash on expansion, and its market valuation was driven more by speculation than earnings. The net worth after their first year was inflated by investor enthusiasm for the Apple II and the broader tech boom of the early 1980s.
Q: Did Steve Jobs benefit financially from the IPO?
A: Jobs retained about 10% ownership post-IPO, holding roughly 7 million shares. While he wasn’t a billionaire yet, the IPO gave him liquidity and leverage—though his later ouster from Apple in 1985 meant he missed out on the company’s long-term growth. His stake would have been worth billions today if he’d held onto it.
Q: How did Apple’s first-year valuation compare to other tech companies at the time?
A: Apple’s net worth after their first year was far higher than most tech firms of the era. For context, Microsoft (which went public in 1986) had a more measured debut, while companies like Atari and Commodore were valued based on immediate profitability, not growth potential. Apple’s IPO proved that tech could command premium valuations based on vision alone—a model later adopted by Google, Amazon, and others.
Q: What was the biggest risk to Apple’s early valuation?
A: The biggest risk was market volatility. Since Apple’s IPO wasn’t underwritten, the stock was exposed to speculative trading, which could have crashed the valuation if investor sentiment shifted. Additionally, the company’s reliance on a single product (the Apple II) meant that any supply chain or design flaw could have derailed growth. The net worth after their first year was fragile—built on hype, not a diversified business model.
Q: How did Apple’s IPO affect Silicon Valley’s funding landscape?
A: Apple’s success legitimized tech as an investable asset, leading to a surge in venture capital funding for hardware and software startups. Before 1980, most VC money went to industrial or biotech firms. Afterward, tech IPOs became a path to wealth, attracting more entrepreneurs and investors to Silicon Valley. The first-year valuation set a precedent that innovation could outvalue traditional metrics—a philosophy that still drives today’s unicorn economy.
