
The Short Answers
- Apple has held the title of the largest company net worth in the world for most of the past decade, with a market cap often exceeding $2.5 trillion.
- Its dominance stems from iPhone profitability, services revenue (Apple Music, iCloud, Apple Pay), and a brand premium that commands higher margins than competitors.
- Apple’s cash reserves—reportedly around $190 billion—make it one of the most liquid corporations on Earth, able to weather downturns or make bold acquisitions.
- Regulatory risks (e.g., antitrust cases) and supply chain vulnerabilities (e.g., China dependence) are the biggest threats to its largest company net worth status.
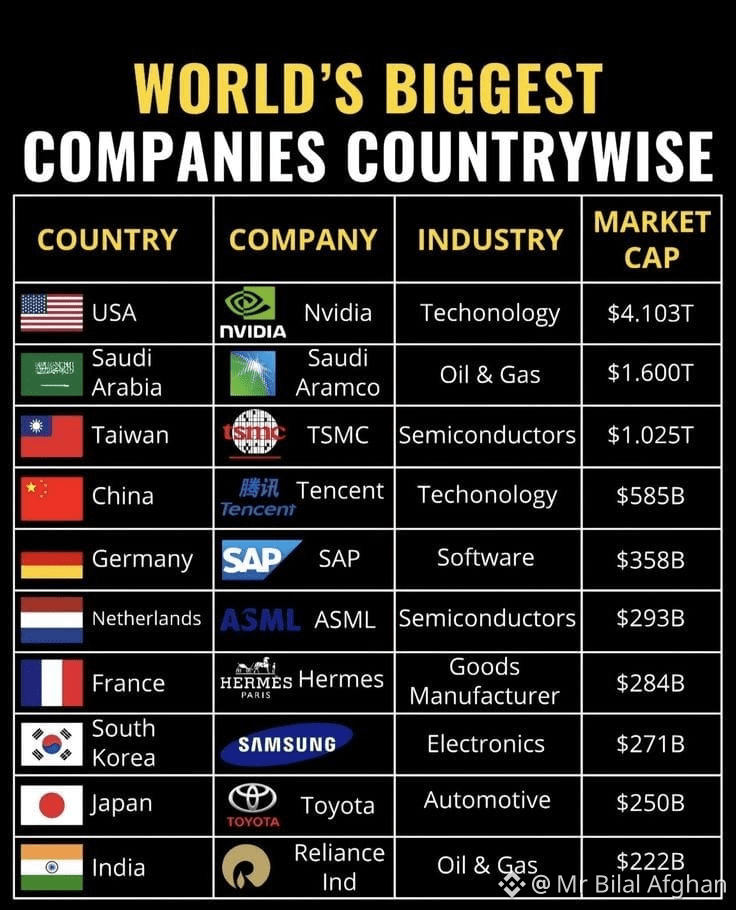
- Microsoft and Saudi Aramco have briefly challenged Apple’s lead, but none have matched its ecosystem lock-in or long-term growth trajectory.
Deep Dive: The Full Picture
Apple’s ascent to the largest company net worth in the world wasn’t a sprint—it was a marathon of incremental mastery. While rivals chased quarterly earnings, Apple focused on owning the entire user journey: from the moment a customer wakes up to their iPhone alarm to the way their Apple Watch syncs with their Mac at night. This vertical integration isn’t just a business strategy; it’s a defense mechanism. When Android manufacturers or Windows PCs improve, Apple’s users don’t just buy a product—they buy into a closed-loop experience. The result? Sticky revenue that compounds over decades. What separates Apple from other global net worth titans like Saudi Aramco or Microsoft is its dual engine: hardware and services. The iPhone alone generates operating margins north of 40%, a figure unmatched in consumer tech. But the real alchemy happens when you layer in services—Apple Music’s subscriber growth, Apple Pay’s transaction volume, and iCloud’s data dependency. These aren’t afterthoughts; they’re the foundation of Apple’s valuation. When you own the device, the OS, the app store, and the cloud, you don’t just sell products—you own the customer’s digital life.The Context You Need
Understanding Apple’s largest company net worth requires stripping away the hype around its products and examining the structural advantages that make it untouchable. For starters, Apple’s supply chain isn’t just efficient—it’s strategic. The company holds billions in cash with suppliers, effectively acting as a bank for its own ecosystem. This financial leverage lets Apple negotiate terms that no competitor can match, from Foxconn’s labor costs to Taiwan Semiconductor’s chip allocations. When others scramble for components, Apple owns the queue. Then there’s the brand halo effect. Apple doesn’t just sell phones; it sells status. The premium pricing isn’t a mistake—it’s a deliberate signal that reinforces exclusivity. Studies show Apple users pay 20-30% more for accessories and peripherals than Android users, not because of specs, but because of perceived value. This isn’t just about margins; it’s about cultural capital. When Apple launches a new product, it doesn’t just move inventory—it reshapes consumer behavior.The Mechanics
The largest company net worth in the world isn’t built on debt—it’s built on cash flow. Apple’s free cash flow has consistently exceeded $50 billion annually, even during downturns. This isn’t just profit; it’s dry powder that lets the company buy back shares (boosting its stock price), pay dividends (attracting income investors), or make acquisitions (like Beats or Dark Sky) that expand its moat. The company’s shareholder returns—$400 billion+ in buybacks and dividends since 2012—have turned Apple into a machine for wealth creation, not just a tech company. But the real secret sauce is R&D efficiency. Apple spends less than 3% of revenue on R&D compared to peers like Samsung (15%) or Qualcomm (20%). How? By outsourcing innovation—partnering with universities, acquiring startups, and leveraging its design prowess to reimagine existing tech. The iPhone’s camera, for example, wasn’t built by Apple engineers alone; it was a collaboration with lens manufacturers, sensor firms, and software teams that Apple orchestrrated. This networked innovation lets Apple punch above its weight in valuation.Details That Change the Picture
Apple’s largest company net worth isn’t just about today’s profits—it’s about tomorrow’s bets. Consider its $1 trillion+ in off-balance-sheet assets, including real estate, intellectual property, and untapped services potential. Apple TV+, Apple Arcade, and Apple Fitness+ may seem niche, but they’re training wheels for a future where subscriptions dominate. The company’s services revenue has grown 20% annually for over a decade—a clip that dwarfs its hardware growth. If Apple can monetize its user data (without regulatory backlash) or crack AI integration (like Siri 2.0), its valuation could spiral upward. Yet for every strength, there’s a pressure point. Apple’s China dependence—over 90% of its iPhone production happens there—is a geopolitical risk. Tariffs, labor strikes, or a US-China decoupling could disrupt supply chains overnight. Then there’s antitrust scrutiny: the EU’s Digital Markets Act and US lawsuits over App Store fees could force Apple to loosen its grip, eroding the very moat that protects its largest company net worth. And let’s not ignore talent retention. Apple’s $100 billion+ R&D budget is only as good as the engineers it can keep. Poaching by Google, Microsoft, or even startups could hollow out its innovation pipeline."Apple’s valuation isn’t about the products it sells—it’s about the trust it’s built over 20 years. When users feel their data is safe, their devices won’t become obsolete, and their ecosystem is seamless, they don’t just buy a phone. They invest in Apple’s future." — Tim Cook, Apple CEO (internal memo, 2021)
| Metric | Apple’s Position (2024) |
|---|---|
| Market Cap (Peak) | ~$2.9 trillion (briefly surpassed in 2021) |
| Cash Reserves | ~$190 billion (highest among Fortune 500) |
| Services Revenue Growth (YoY) | ~20% (vs. ~5% for hardware) |
| R&D Spend as % of Revenue | ~2.8% (vs. ~15% for Samsung) |

Conclusion
Apple’s largest company net worth in the world isn’t an accident—it’s the result of decades of disciplined execution. While competitors chase trends, Apple sets them. Its ability to reinvent itself—from a Mac-focused company to a services powerhouse—is what keeps it ahead. But the real test isn’t maintaining the title; it’s defending the ecosystem that underpins it. Regulatory battles, supply chain shocks, and the rise of AI could all threaten its dominance. The question isn’t whether Apple will stay on top—it’s how long it can stay untouchable. One thing is certain: no other company combines Apple’s financial firepower, brand loyalty, and innovation moat in the same way. For now, the largest company net worth in the world remains Apple’s to lose—if it chooses to.Comprehensive FAQs
Q: How does Apple’s net worth compare to other global giants like Saudi Aramco or Microsoft?
Apple’s market cap has historically outpaced both. While Aramco’s valuation is tied to oil price volatility, and Microsoft’s growth is cloud-dependent, Apple’s diversified revenue streams (hardware + services) make it more resilient. Microsoft briefly surpassed Apple in 2021 due to its cloud surge, but Apple’s ecosystem stickiness ensures it rebounds quickly.
Q: Can Apple’s net worth be threatened by a recession?
Apple has weathered recessions better than most due to its high-margin products and services growth. In 2008-09, it cut costs but maintained profitability; in 2020, it pivoted to services as iPhone sales slowed. Its $190 billion cash hoard acts as a shock absorber, letting it buy back shares or invest in R&D even during downturns.
Q: Why does Apple’s stock price fluctuate so much if it’s the largest company?
Apple’s stock is highly sensitive to three factors: iPhone sales cycles (quarterly earnings), Macro trends (interest rates, USD strength), and innovation bets (e.g., AI, wearables). Unlike stable dividend stocks, Apple’s valuation is growth-driven, so even minor misses in guidance can trigger sharp sell-offs. Its services revenue (less volatile) is now a counterbalance.
Q: How does Apple’s cash reserve compare to governments?
Apple’s $190 billion+ in cash is larger than the annual budget of many countries (e.g., Iceland’s GDP). It’s also more liquid than sovereign wealth funds, as Apple can deploy it instantly for buybacks, acquisitions, or tax payments. This financial flexibility is why investors treat Apple like a hybrid corporation-state.
Q: What’s the biggest risk to Apple’s net worth—regulators or competitors?
Regulators pose the immediate threat—antitrust cases could force Apple to open its App Store, reducing its 30% cut on transactions. Competitors like Samsung or Google can’t replicate Apple’s ecosystem, but Microsoft’s AI push or China’s homegrown tech giants (Huawei, Xiaomi) could erode its premium. The bigger risk? Apple resting on its laurels—innovation stagnation would unravel its moat faster than any lawsuit.
Q: How does Apple’s valuation hold up against private companies like SpaceX or ByteDance?
Private valuations are speculative, but Apple’s $2.5T+ market cap dwarfs even the most aggressive estimates for SpaceX (~$180B) or ByteDance (~$300B). The key difference? Apple’s cash-flow-positive business model vs. burn-rate-heavy startups. SpaceX and ByteDance rely on funding rounds; Apple funds itself. That’s why investors trust Apple’s numbers more than private valuations.
Q: Could Apple’s net worth grow even larger if it enters new industries?
Apple’s entry into healthcare (Apple Watch), autonomous vehicles (Project Titan), or AI could expand its TAM (total addressable market), but the risks are high. Regulatory hurdles (e.g., medical devices) or cannibalizing existing revenue (e.g., Apple TV vs. iPhone) could dilute its focus. The safest bet? Deepening services (e.g., Apple Pay in more countries) or AI integration—areas where it can leverage its user base without overreach.
Q: Is Apple’s net worth sustainable long-term, or is it a bubble?
Apple’s valuation is not a bubble—it’s backed by real assets: IP, cash, and recurring revenue. The "bubble" argument ignores that 90% of Apple’s market cap comes from future earnings, not today’s profits. If services grow at 20% annually and Apple cracks AI, its valuation could double. The real risk? Overestimating its ability to innovate—if growth slows, the premium multiple (30x+ P/E) could shrink.
