
The Short Answers
- The median American net worth is around $138,000, but the average (skewed by the ultra-wealthy) is closer to $1.1 million.
- The top 1% owns 35% of all wealth, while the bottom 50% owns just 2.6%.
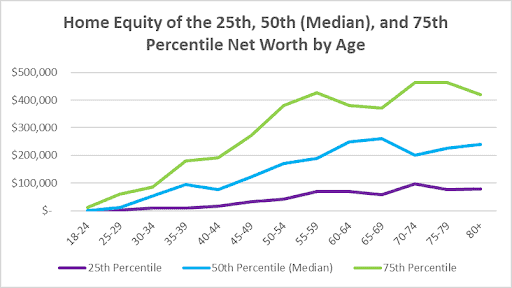
- Homeownership is the single biggest driver of net worth—67% of the top 10% own their homes outright, vs. 3% of the bottom 20%.
- Regional disparities are stark: the median net worth in Maryland is $150,000+, while in West Virginia, it’s under $60,000.
- Age is destiny—65+ Americans hold 57% of all net worth, despite making up just 16% of the population.
Deep Dive: The Full Picture
The Americans percentile by net worth landscape is defined by two forces: inheritance and asset accumulation. The top 10% didn’t just earn their way to the top—they inherited it. A 2022 study by the Urban Institute found that 60% of wealth transfers (via gifts or estates) go to the richest 20%. Meanwhile, the bottom 40% receive almost nothing. This isn’t just about wills and trusts; it’s about social capital. Families that own homes, stocks, or businesses pass down generational wealth, while renters and wage earners start from zero. The Federal Reserve’s data shows that liquid assets—cash, stocks, bonds—are concentrated in the top percentiles. The median net worth for the 90th percentile is $1.3 million, but 90% of that wealth is tied up in home equity or retirement accounts. For the bottom 20%, liquidity is a luxury. Their net worth is often negative, thanks to student loans or medical debt. This isn’t a failure of personal finance—it’s a failure of systemic access. The wealth percentiles of Americans aren’t just numbers; they’re a ledger of who gets to play by the rules.The Context You Need
The percentile breakdown of American net worth has barely budged in decades. Since 1989, the top 1%’s share of wealth has grown from 33% to 35%, while the bottom 90%’s share has shrunk. The Great Recession of 2008 wiped out $16 trillion in household wealth, but the recovery wasn’t uniform. The top 5% saw their net worth rebound by 2012; the bottom 20% never did. This isn’t a temporary blip—it’s the new normal. The distribution of Americans by net worth percentile has become more extreme with each economic cycle. Policy plays a role, but so does culture. Americans are taught to believe in meritocracy, yet the data shows that wealth begets wealth. A child born into the top 20% has a 70% chance of staying there; one born into the bottom 20% has just a 5% chance of escaping. The net worth percentiles of Americans aren’t just about money—they’re about who gets to write the rules of the game. And those rules favor the already wealthy.The Mechanics
The mechanics of Americans’ net worth percentiles hinge on three pillars: homeownership, retirement savings, and inheritance. Homeownership is the great equalizer—or not. The median homeowner’s net worth is $280,000, while the median renter’s is $8,000. Retirement accounts (401(k)s, IRAs) follow a similar pattern: the top 10% have $250,000+ saved, while the bottom 20% have nothing. Inheritance is the wild card. The wealthiest 1% receive 37% of all bequests, while the bottom 40% get less than 1%. The percentile rankings of Americans by net worth also reflect education. A college degree boosts lifetime earnings by $1 million, but the effect is nonlinear. A degree from an elite university can add another $2 million to net worth over a lifetime. Meanwhile, the bottom 20% of Americans by net worth are more likely to have no degree at all. This isn’t just about smarter choices—it’s about access to opportunities that most never see.Details That Change the Picture
Race and gender distort the Americans percentile by net worth data in ways that go unnoticed. The median white household sits in the 60th percentile, while the median Black household is in the 25th. The gap isn’t just income—it’s wealth accumulation over generations. For women, the story is different but equally stark. At retirement, women’s net worth is 30% lower than men’s, even after adjusting for income. The wealth distribution among Americans by percentile isn’t neutral; it’s shaped by historical exclusion, pay gaps, and caregiving burdens that fall disproportionately on women. Geography amplifies these divides. In Massachusetts, the median net worth is $150,000+; in Mississippi, it’s under $60,000. The percentile breakdown of American net worth varies by state because tax policies, housing markets, and job opportunities differ wildly. A teacher in New York City may be in the 80th percentile, while one in Detroit could be in the 30th. The wealth percentiles of Americans aren’t static—they’re a moving target shaped by where you live."Wealth isn’t just about how much you earn—it’s about who you know, where you live, and what your parents left you. The percentile rankings of Americans by net worth prove that the game is rigged before you even start." — Edward N. Wolff, Professor of Economics at NYU
| Percentile | Median Net Worth |
|---|---|
| Top 1% | $10.3 million+ |
| 90th–99th | $1.3 million–$10.3 million |
| 50th (Median) | $138,000 |
| Bottom 20% | $8,000 (often negative due to debt) |

Conclusion
The Americans percentile by net worth isn’t just a snapshot—it’s a warning. The data shows that wealth isn’t earned in a vacuum; it’s inherited, accumulated through homeownership, and protected by policy. The distribution of Americans by net worth percentile has become more extreme over time, not less. This isn’t an accident—it’s the result of deliberate choices in taxation, education, and housing policy. The question isn’t whether the system is fair—it’s whether it’s sustainable. If the wealth percentiles of Americans continue to diverge, the middle class will shrink further, and social mobility will become a myth. The data is clear: wealth begets wealth, and without intervention, the net worth percentiles of Americans will keep widening. The only question left is whether society will act before it’s too late.Comprehensive FAQs
Q: How does homeownership affect my net worth percentile?
The median homeowner’s net worth is $280,000, while renters sit at $8,000. If you own your home outright, you’re likely in the top 30% of Americans by net worth. Renting keeps you in the bottom 40%, even if you earn a middle-class income.
Q: Can I move up percentiles by saving aggressively?
Yes, but the odds are stacked against you. The bottom 20% of Americans by net worth have no liquid assets—even if you save $500/month, it’ll take decades to climb into the 50th percentile. Inheritance, stock market gains, and home appreciation are far more powerful than budgeting alone.
Q: Why do Black and Hispanic households rank lower in net worth percentiles?
Historical redlining, wage gaps, and lower homeownership rates explain the gap. The median white household is in the 60th percentile; the median Black household is in the 25th. Policy changes—like student debt relief or down payment assistance—could shift these numbers, but systemic barriers remain.
Q: Does age matter more than income for net worth percentiles?
Absolutely. A 30-year-old in the 75th percentile may have $250,000, but a 65-year-old in the same bracket could have $1.2 million thanks to compounding. The wealthiest 10% are overwhelmingly 55+, while the bottom 20% are under 35. Time is the ultimate wealth multiplier.
Q: How do I check my own net worth percentile?
Use the Federal Reserve’s SCF data or tools like Spectrem Group’s wealth reports. Plug in your assets (home, investments, retirement) minus debts (mortgage, loans). If you’re under $138,000, you’re below median. If you’re over $1.3 million, you’re in the top 10%.
