
Where It All Began
The origins of united states net worth by age tracking can be traced back to the 1960s, when economists first began dissecting household balance sheets. Before then, discussions about wealth focused on income—what people earned in a year. But net worth, the difference between assets and liabilities, told a different story. It revealed that wealth wasn’t just about paychecks; it was about time, leverage, and luck. The first major study, conducted by the Federal Reserve in 1962, showed that Americans over 55 held 80% of all liquid assets, while those under 35 had barely any. The implication was clear: wealth was concentrated in the hands of those who had spent decades building it. The real inflection point came in 1983, when the Fed’s Survey of Consumer Finances introduced age-based breakdowns. For the first time, the public could see how wealth accumulated—or failed to—in predictable patterns. A 30-year-old with a mortgage and car payments had little to show for their labor, while a 60-year-old with a paid-off home and retirement savings had a net worth that dwarfed theirs. The data suggested that wealth wasn’t just a product of effort, but of structural timing. Those who entered the workforce during economic expansions, bought homes when prices were low, and benefited from employer pensions had an unfair advantage. The system wasn’t rigged—it was just stacked.The Early Signs
By the late 1980s, the cracks began to show. The Savings and Loan crisis of the early 1990s wiped out wealth for thousands of middle-class families, but the damage was uneven. Older homeowners with fixed-rate mortgages weathered the storm, while younger buyers with adjustable rates saw their equity vanish. The message was simple: united states net worth by age wasn’t just about demographics—it was about risk tolerance and access to capital. Meanwhile, the rise of 401(k)s over pensions shifted the burden of retirement savings onto individuals, widening the gap between those who could save consistently and those who couldn’t. The 1990s tech boom further exaggerated the divide. A 25-year-old software engineer in Silicon Valley could build wealth overnight, while a 45-year-old factory worker in Rust Belt saw their savings erode. The dot-com crash of 2000 didn’t reset the clock—it accelerated the trend. Those who had entered the market early rode the wave; those who entered late were left behind. The lesson was clear: united states net worth by age was no longer just about time—it was about timing.The Turning Point
The Great Recession of 2008 was the moment united states net worth by age became a political issue. The collapse of housing prices didn’t just hurt homeowners—it rewrote the rules of wealth accumulation. Older Americans, who had benefited from decades of home equity growth, saw their net worth drop by 20% on average. But younger Americans, who had entered the market later, were hit harder. Those under 35 lost 30% of their wealth, and many never recovered. The Fed’s response—quantitative easing and near-zero interest rates—kept the economy afloat, but it also inflated asset prices, making it harder for younger buyers to enter the market. The aftermath revealed a brutal truth: wealth begets wealth. Those who had assets before the crash saw their portfolios rebound quickly. Those who didn’t were left playing catch-up in an economy where housing, stocks, and even wages were increasingly out of reach. By 2015, the median net worth of Americans over 65 had fully recovered, while those under 35 were still 15% below their pre-crisis levels. The recession didn’t just expose inequality—it deepened it."Wealth isn’t just money. It’s opportunity. And opportunity isn’t equally distributed." — Edward N. Wolff, Professor of Economics at NYU

The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1980s–1990s | Shift from pensions to 401(k)s; homeownership rates peak; wealth gap by age begins to widen visibly. |
| 2000s | Dot-com crash and housing bubble; older generations benefit from rising home values, younger workers enter a stagnant job market. |
| 2010s–Present | Student debt crisis; gig economy growth; older Americans hold 70% of all investable assets, while younger generations struggle with debt and housing costs. |
Lessons From the Journey
- Wealth accumulation is exponentially harder for younger generations due to student debt, housing costs, and stagnant wages.
- Policy responses—like low interest rates—benefit asset holders (older Americans) more than wage earners (younger Americans).
- The homeownership advantage is the single biggest driver of wealth inequality by age.
- Retirement savings systems (401(k)s) shift risk to individuals, widening gaps between disciplined savers and those who can’t save.
- Inheritance and gifting play a larger role in wealth transfer than most assume—70% of intergenerational wealth transfer goes to those already in the top 20%.
- The racial wealth gap is three times wider than the age-based gap, but the two are deeply interconnected.
Where Things Stand Today
As of 2024, the data on united states net worth by age paints a stark picture. The median net worth of Americans aged 65–74 is $280,000, while those under 35 sit at $12,000. The gap isn’t just about money—it’s about options. Older Americans can retire, travel, or weather financial shocks. Younger Americans face student debt, unaffordable housing, and stagnant wages. The pandemic briefly compressed the gap as stock markets surged, but the underlying trends remain unchanged: wealth still flows upward. The most alarming trend? Younger generations are saving less. A 2023 Federal Reserve report found that Americans under 40 are saving only 3% of their income, compared to 8% for those over 60. The reasons are clear: rising costs, stagnant wages, and a lack of financial safety nets. Without intervention, the united states net worth by age gap will only widen, creating a permanent underclass of asset-poor young adults.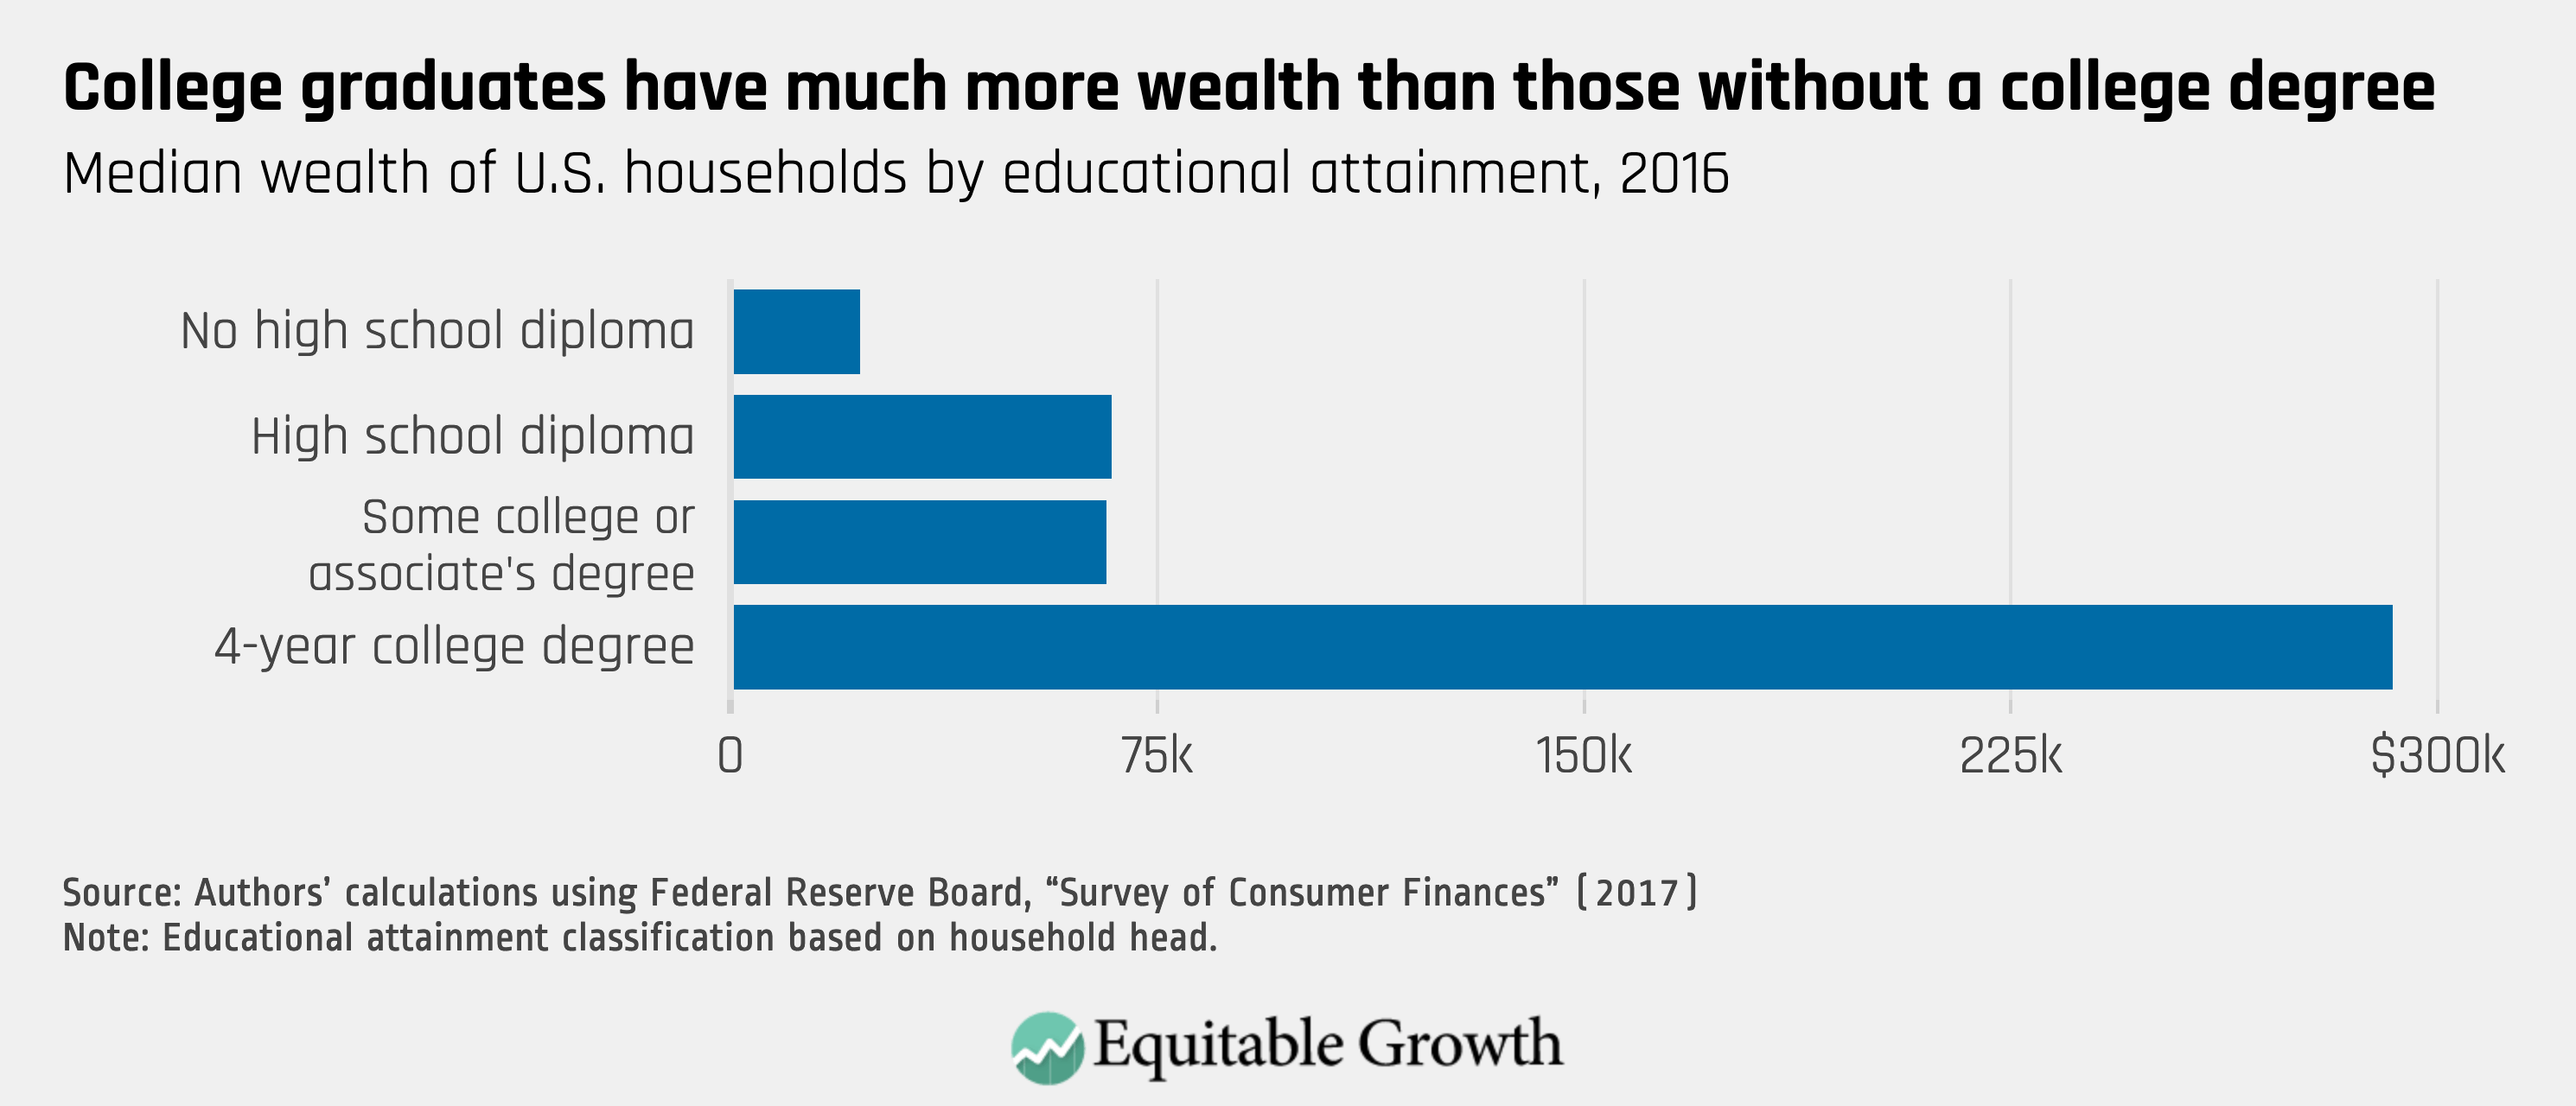
Conclusion
The story of united states net worth by age isn’t just about numbers—it’s about power. Those who control wealth control opportunity. And in America, that opportunity has been systematically deferred to future generations. The question now isn’t just how to close the gap, but whether younger Americans will ever have the same chance to build wealth that their parents and grandparents did. The data suggests the answer is no, unless structural changes—like student debt relief, housing reform, and stronger social safety nets—are made. The alternative is a future where wealth inequality isn’t just a statistic—it’s a permanent divide. And that future is already here.Comprehensive FAQs
Q: Why is the wealth gap by age so much wider now than in the 1980s?
The gap has widened due to three major factors: the shift from pensions to 401(k)s (which penalizes those who can’t save consistently), the housing crisis of 2008 (which wiped out younger workers’ equity), and stagnant wages paired with rising costs (especially education and healthcare). Older generations benefited from low interest rates, home equity growth, and employer-sponsored retirement plans—none of which exist for younger workers today.
Q: Can younger Americans ever catch up in net worth?
It’s possible, but unlikely without systemic changes. Current trends suggest that homeownership, stock market participation, and inheritance are the only reliable paths to wealth—but all three are increasingly out of reach for younger generations. Policies like student debt forgiveness, expanded Social Security, and rent control could help, but none are currently on the horizon.
Q: How does race factor into the age-based wealth gap?
The racial wealth gap dwarfs the age-based gap. A Black 65-year-old has, on average, one-tenth the net worth of a white 65-year-old. This is due to historical discrimination (redlining, wage gaps), inherited wealth disparities, and systemic barriers to homeownership and education. The age-based gap is worse for Black and Latino Americans because they start from a lower baseline.
Q: Is there any age group that’s doing better than expected in terms of net worth?
Yes—immigrants and high-earning professionals under 40 are outperforming their peers. Immigrants, particularly from Asia, have higher household incomes and stronger savings rates. Meanwhile, tech workers, doctors, and lawyers in their 30s are building wealth faster than the average due to high salaries and early stock market investments. However, these groups are small minorities—most young Americans still struggle.
Q: What’s the biggest myth about wealth by age?
The biggest myth is that hard work alone is enough. While effort matters, timing, inheritance, and systemic advantages play a far larger role. A 25-year-old working two jobs may save aggressively, but if they can’t afford a home or student debt is crushing them, they’ll never catch up to someone who bought a house in the 1990s. Wealth is not just about effort—it’s about opportunity.
Q: How does the U.S. compare to other developed nations in age-based wealth inequality?
The U.S. has one of the widest age-based wealth gaps in the developed world. Countries with stronger social safety nets (like Sweden or Germany) see less extreme disparities because universal healthcare, paid leave, and housing subsidies reduce financial risk for younger workers. In the U.S., lack of universal childcare, high college costs, and weak unemployment benefits make wealth accumulation far more volatile by age.
