Common Myths About American Wealth Distribution Over Time
The conventional wisdom about wealth inequality in America often oversimplifies history. One persistent myth is that the modern concentration of wealth is a recent phenomenon, a product of the last few decades. In reality, the patterns stretch back over a century, with the late 19th century seeing wealth shares among the top 1% rivaling today’s levels. Another misconception is that wealth inequality is purely a function of individual effort—if you work hard enough, you’ll join the ranks of the rich. Yet the data shows that inheritance and asset ownership (like real estate or stocks) play a far larger role than sheer labor in building generational wealth. A third myth frames the 1950s and 1960s as a golden era of broad-based prosperity, where the middle class thrived and inequality shrank. While it’s true that the post-WWII period saw a more equal distribution of income, wealth inequality remained stubbornly high—especially when accounting for assets like homes and stocks. The real "golden age" for the middle class was shorter and more fragile than often remembered, dependent on specific policies (like progressive taxation and strong labor unions) that were later dismantled.Myth 1: The 1% Always Held the Most Wealth
The idea that the top 1% have always dominated American wealth distribution ignores critical historical turns. In the early 20th century, the share of wealth held by the top 1% fluctuated significantly—peaking at around 35% in the 1920s, then plummeting to roughly 15% by the late 1970s. This shift was driven by policies like the New Deal, which redistributed wealth through taxation and asset reforms, and World War II, which temporarily equalized incomes as military service and wartime production created jobs across skill levels. The post-war boom also saw a rise in unionization and stronger labor protections, which compressed wage gaps. By the 1980s, however, deregulation, tax cuts, and financial innovation began reversing these trends, restoring the top 1%’s share to pre-Depression levels. What’s often overlooked is that the long-term trajectory of wealth distribution isn’t a straight line upward for the rich. The 1930s and 1940s were periods of forced redistribution—through confiscatory tax rates (up to 94% on top incomes) and asset seizures. Even the 1950s, when the middle class expanded, saw the top 1% holding about 20% of wealth, not the near-monopoly some assume. The real outlier isn’t today’s inequality; it’s how quickly it rebounded after the mid-century compression.Myth 2: The Middle Class Has Always Been the Majority
The notion that the American middle class has consistently made up a majority of households obscures how definitions of "middle class" have shifted—and how wealth, not just income, matters. In the 1950s, about 60% of households owned their homes, and stock ownership was still rare outside elite circles. By the 1980s, homeownership rates climbed to 65%, but wealth inequality widened as asset values concentrated in the hands of fewer people. Today, the "middle class" is often defined by income brackets (e.g., $50,000–$150,000 annually), but this ignores that wealth distribution over time tells a different story: the median household’s net worth has stagnated since the 1990s, while the top 10% hold nearly 70% of all wealth. The confusion arises because income and wealth are not the same. A family earning $80,000 might feel middle-class, but if they have no savings, no home equity, and no investments, their financial security is far more precarious than in past eras. The evolution of wealth ownership shows that the middle class’s share of total wealth has declined since the 1980s, even as their share of income remained relatively stable. This disconnect explains why so many Americans feel economically stagnant despite nominal growth in GDP.Myth 3: Wealth Inequality Is Just About Money—Not Power
Focusing solely on dollar figures misses how wealth concentration over time translates into political and social leverage. The top 1% don’t just control capital; they shape the rules of the game. In the Gilded Age, railroad tycoons like Vanderbilt and Carnegie not only amassed fortunes but also lobbied to weaken antitrust laws and suppress labor movements. Today, the ultra-wealthy influence policy through lobbying, campaign donations, and think tanks that frame economic debates. The historical arcs of wealth distribution reveal that when the rich hold disproportionate sway, policies tend to favor asset appreciation (like tax cuts for capital gains) over wage growth or public investment. This dynamic isn’t static. During the New Deal, wealth redistribution was paired with labor rights and social programs, temporarily reducing inequality. When wealth concentration rose again in the 1980s, policies shifted toward deregulation and financialization—benefiting those who already owned assets. The lesson is clear: wealth distribution over time isn’t just an economic metric; it’s a battleground for who controls the future.
What Holds Up to Scrutiny
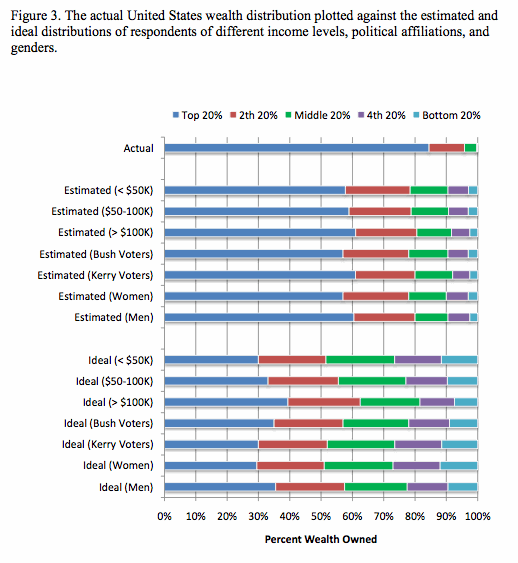
The most reliable data on American wealth distribution over the past century comes from two sources: the Federal Reserve’s Survey of Consumer Finances (SCF) and historical estimates by economists like Edward N. Wolff and Thomas Piketty. These sources confirm that wealth inequality in the U.S. has followed three broad phases: 1. Concentration (1890s–1930s): The top 1% held 30–40% of wealth, with fortunes built on railroads, oil, and manufacturing. 2. Compression (1930s–1980s): Progressive taxation, labor laws, and wartime disruption reduced the top 1%’s share to 15–20%. 3. Reconcentration (1980s–present): Tax cuts, financial deregulation, and globalization restored the top 1%’s share to near-historic highs. What’s less debated is that wealth inequality is far more extreme than income inequality. While the top 20% earn about half of all income, they hold roughly 90% of all wealth. The bottom 50% of Americans collectively own less than 1% of the nation’s wealth—a figure that hasn’t changed meaningfully since the 1980s."Wealth inequality is not just about money. It’s about who gets to pass on generational advantage—and who doesn’t." —Edward N. Wolff, How the Other Half Lives
| Common Belief | What the Evidence Says |
|---|---|
| The 1950s were a golden age for the middle class. | While incomes rose, wealth inequality remained high (top 1% held ~20%), and asset ownership (like stocks) was concentrated among the wealthy. |
| Taxes are the main driver of inequality. | Tax rates on top incomes fell sharply after 1980, but wealth concentration also surged due to financial deregulation and globalization. |
| The Great Recession reduced wealth inequality. | It temporarily narrowed gaps, but by 2021, the top 1%’s share of wealth exceeded pre-2008 levels. |
| Homeownership has always been the great equalizer. | While homeownership rates rose post-WWII, mortgage lending practices (like redlining) excluded minorities, perpetuating racial wealth gaps. |
| Wealth inequality is a recent problem. | The top 1%’s share of wealth was similarly high in the 1920s and has only recently surpassed those levels. |
Why the Confusion Persists
Two factors obscure the clarity of wealth distribution trends over time. First, data limitations: The Federal Reserve’s SCF only began tracking wealth in 1989, leaving gaps for earlier eras. Economists rely on patchwork sources—tax records, probate data, and estate filings—to reconstruct the past, which introduces uncertainty. Second, political framing: Conservatives often emphasize income mobility and entrepreneurship, while progressives highlight structural barriers like inheritance and asset ownership. Both narratives contain truth, but neither fully captures how wealth accumulation over generations reinforces inequality. The result is a public discourse that treats inequality as either a moral failing or an inevitable market outcome—rather than a policy choice. The data shows that periods of reduced inequality (like the 1950s) coincided with active government intervention, while eras of rising inequality followed deregulation and tax cuts. The confusion isn’t just about numbers; it’s about who benefits from the system as it exists today.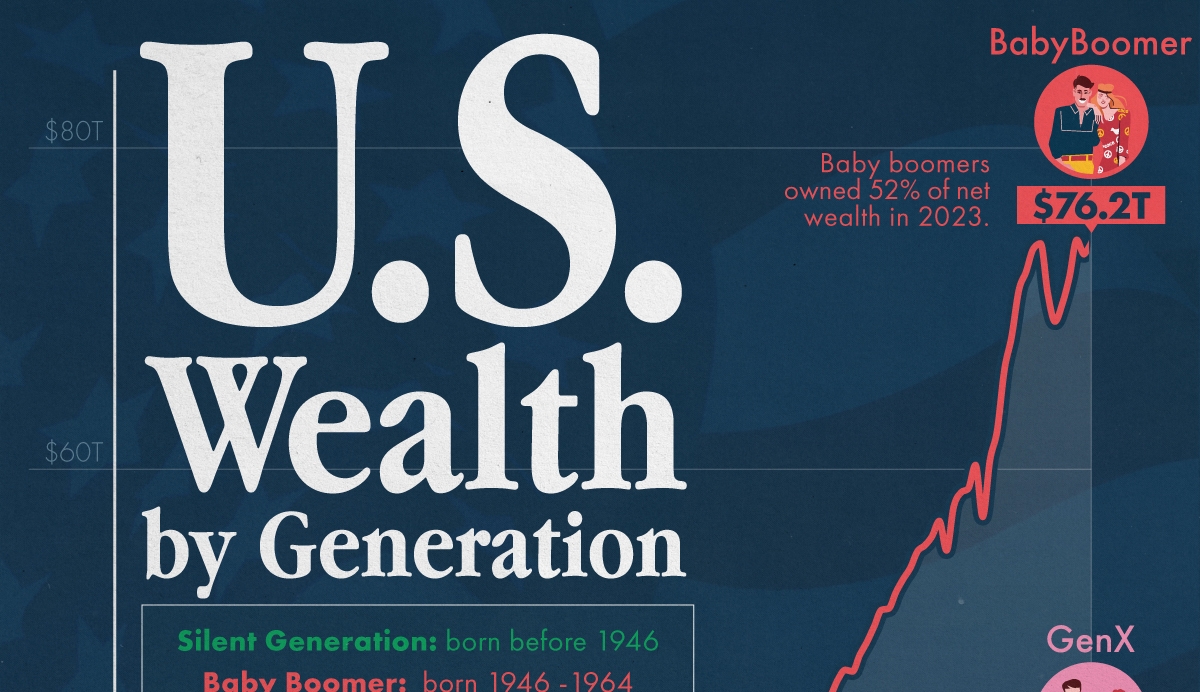
Conclusion
The history of American wealth distribution is not a tale of inevitable decline or progress, but of cycles where power and policy interact. The 19th-century robber barons, the mid-century New Dealers, and today’s tech billionaires all reflect eras where the rules of wealth accumulation were rewritten—sometimes to concentrate power, sometimes to disperse it. What’s clear is that wealth inequality is not a natural state but a product of deliberate choices: which taxes to cut, which industries to regulate, and which families to include in the system’s rewards. The challenge ahead isn’t just measuring inequality but deciding whether to repeat the past’s mistakes or learn from its lessons. The data shows that wealth concentration can be reversed—but only when there’s political will to challenge the status quo. The question is whether that will emerges before the next cycle of inequality takes hold.Comprehensive FAQs
Q: How does inheritance factor into wealth inequality?
Inheritance accounts for about 20% of wealth transfers annually, but its impact is uneven. The top 10% of estates (worth over $12 million) receive 80% of all inherited wealth, reinforcing concentration. Unlike income, which can be earned anew, inherited wealth compounds over generations, creating a self-perpetuating advantage for the already wealthy.
Q: Did the New Deal actually reduce wealth inequality?
Yes, but not as dramatically as often claimed. Progressive taxation (top rates up to 94%) and asset reforms (like breaking up monopolies) reduced the top 1%’s share from ~35% in the 1920s to ~15% by the 1970s. However, wealth inequality remained high by modern standards, and the middle class’s share of total wealth grew only modestly. The real shift was in income equality, not wealth.
Q: Why do the ultra-rich hold so much wealth today?
Three factors dominate: tax policy (lower capital gains rates since 1980), financialization (assets like stocks and private equity outperform wages), and globalization (which benefits capital over labor). The top 1%’s share of wealth surged after 1980 because policies favored asset owners—while wages stagnated and public investment declined.
Q: Can wealth inequality be fixed without radical policy changes?
Unlikely. Historical examples show that meaningful reductions in wealth inequality require structural changes: progressive taxation (like the 1930s–1970s), strong labor unions, and policies that expand asset ownership (e.g., Social Security, homeownership programs). Incremental reforms (like closing tax loopholes) can help, but they’ve proven insufficient to reverse long-term trends.
Q: How does racial wealth inequality fit into this story?
Racial wealth gaps are a critical subplot. The median white household holds $188,200 in wealth, while the median Black household holds $24,100—a ratio that persists despite decades of civil rights progress. Policies like redlining, predatory lending, and mass incarceration systematically stripped wealth from Black and Latino families, while white families benefited from homeownership subsidies, inheritance, and intergenerational wealth transfers.
Q: What’s the biggest misconception about wealth inequality?
The idea that it’s primarily about laziness or lack of effort. While individual choices matter, wealth is far more about inheritance, asset ownership, and access to opportunity than personal merit. The top 1%’s share of wealth has fluctuated wildly over time—proving that inequality is shaped by policy, not just human nature.
