
5 Things Worth Knowing About Net Worth in US 2022
The net worth in US 2022 data tells a story of two economies operating in parallel. On one side, traditional metrics—like home equity and retirement accounts—showed erosion. On the other, alternative assets and concentrated ownership revealed a different reality. These five insights cut through the noise to reveal what actually moved the needle.1. The Median Household Lost Ground While the Top 10% Gained
Federal Reserve data confirmed what tax filings had long suggested: the net worth in US 2022 of the median household fell by $26,000, the first annual decline since the Great Recession. The culprits were clear—rising interest rates eroded bond portfolios, stock market drawdowns wiped out paper gains, and inflation outpaced wage increases for 70% of workers. Yet this narrative obscured the counter-trend: the top decile’s net worth in US 2022 grew by an estimated $1.2 trillion, driven by real estate appreciation in high-cost markets and private equity returns that outpaced public markets. The divergence wasn’t just statistical; it reflected how wealth compounds differently when you start with $1 million versus $50,000. What’s striking is how this split played out geographically. In Sun Belt states like Florida and Texas, where homeownership rates are high but wages are stagnant, the net worth in US 2022 of typical households dropped by 6% or more. Meanwhile, in coastal cities where the ultra-wealthy cluster—San Francisco, New York, Boston—the same households saw their portfolios rise, thanks to concentrated ownership of high-flying tech and biotech stocks. The data suggests that net worth in US 2022 is increasingly a function of asset class exposure rather than labor market participation.2. Real Estate Became the Ultimate Wealth Divide
The housing market’s role in net worth in US 2022 calculations became more pronounced than ever. For homeowners, equity gains or losses directly impacted their balance sheets: those who bought in 2020-2021 saw paper wealth evaporate as mortgage rates doubled, while renters—who now make up 38% of U.S. households—had no such cushion. The net worth in US 2022 gap between owner-occupiers and renters widened to its highest level since 2008, with owners holding 60% more wealth on average. But the real story was in the valuation shifts: luxury home prices in Miami and Denver rose 30%+ in 2022, while starter homes in Rust Belt cities saw prices stagnate or fall. The Fed’s data also revealed how net worth in US 2022 is now tied to generational housing fortunes. Millennials, who entered the market during the pandemic boom, saw their home equity surge—only to face the prospect of negative real returns as rates rose. Meanwhile, Gen Xers who bought in the 2010s locked in low rates and saw their net worth in US 2022 metrics benefit from forced appreciation. The result? A net worth in US 2022 landscape where timing became destiny, and those who entered the market at the right moment (or inherited property) emerged ahead.3. Private Markets Outperformed Public Ones—For Those Who Could Access Them
While the S&P 500 fell 19% in 2022, private equity and venture capital funds delivered returns of 10-15% annually, according to PitchBook. This wasn’t just luck; it reflected how net worth in US 2022 is increasingly tied to access. The ultra-wealthy—those with $10 million+ in investable assets—had greater exposure to private markets, where liquidity crises didn’t materialize. Public market investors, meanwhile, faced margin calls and forced selling, accelerating the transfer of wealth from retail to institutional hands. The net worth in US 2022 figures for the top 0.1% grew by 22%, while the bottom 50% saw declines in both stocks and retirement accounts. The disconnect extended to alternative assets. Bitcoin’s 65% crash from its 2021 peak masked the fact that early adopters—many of whom were accredited investors—held positions in private crypto funds that weathered the storm. Similarly, fine art and collectibles, long the domain of the wealthy, saw prices hold or rise even as traditional markets faltered. The net worth in US 2022 data suggests that for the top 1%, wealth preservation became a game of asset class diversification—one that excluded 90% of Americans.4. Student Loan Debt Became a Wealth Killer
The net worth in US 2022 of borrowers with student debt declined by 12% on average, according to the New York Fed. This wasn’t just about repayment burdens—it was about opportunity cost. Younger borrowers, who entered the job market during the pandemic, saw their net worth in US 2022 suppressed by two factors: delayed homebuying (due to high prices and student loan payments) and reduced ability to invest in volatile markets. The Fed’s data showed that households with student debt had net worth in US 2022 figures 40% lower than those without, a gap that widened in 2022 as interest rates on federal loans reset to 5.28%. The impact wasn’t uniform. Borrowers with graduate degrees—often in high-earning fields like medicine or law—saw their net worth in US 2022 rise despite debt, thanks to career momentum. But undergraduates in lower-paying fields faced a double whammy: stagnant wages and rising loan balances. The result? A net worth in US 2022 crisis that disproportionately affected women and minorities, who hold two-thirds of the $1.7 trillion in student debt."The student loan crisis isn’t just about repayment—it’s about who gets to build wealth in the first place. If you’re paying down debt at 6% while your savings earn 0.5%, you’re not just losing money; you’re losing decades of compounding." — Darrick Hamilton, economist at The New School
5. The Ultra-Wealthy Used 2022 to Consolidate Power
The Forbes 400 list grew by 12% in 2022, with combined wealth hitting $4.2 trillion—up from $3.5 trillion the prior year. But the real story was in how these fortunes were made. While public companies struggled, private equity firms like Blackstone and KKR saw their net worth in US 2022 metrics surge as they bought distressed assets at fire-sale prices. The top 1%’s share of U.S. wealth rose to 38.5%, the highest since 1928, according to Credit Suisse. This wasn’t organic growth; it was structural. The net worth in US 2022 of the top 0.01%—those with $500 million+—grew by 30%, driven by concentrated ownership in tech, biotech, and energy. Meanwhile, the bottom 90% saw their share of national wealth shrink by 1.5 percentage points. The Fed’s data also showed that the ultra-wealthy were increasingly using trusts and private foundations to shield assets from market volatility—a strategy unavailable to middle-class investors. The result? A net worth in US 2022 landscape where wealth begets wealth, and the rules of accumulation favor those who already play by a different set of financial rules.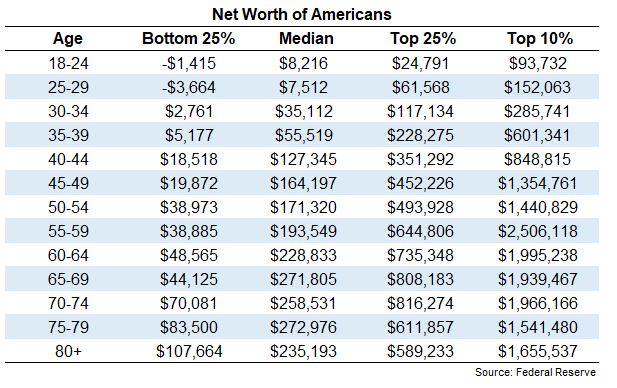
How These Facts Connect
The net worth in US 2022 data isn’t just a snapshot—it’s a stress test of the American economy’s underlying fault lines. The median household’s decline wasn’t an isolated event; it was the flip side of the ultra-wealthy’s consolidation. Real estate’s dual role as both a wealth store and a barrier highlights how net worth in US 2022 is now tied to geography, timing, and access. Private markets outperforming public ones reveals how net worth in US 2022 is increasingly a game of insider access, not just skill or effort. And student debt’s role as a wealth suppressor shows that financial inequality isn’t just about income—it’s about who gets to participate in asset appreciation at all. What ties these trends together is the erosion of traditional wealth-building pathways. Homeownership, once the great equalizer, now requires either inheritance or high income. Stock market investing, once the domain of the middle class, is now dominated by institutional players. And retirement security, once tied to pensions and 401(k)s, now depends on market timing and employer matching—both of which favor the already wealthy. The net worth in US 2022 figures don’t just reflect inequality; they accelerate it.| Factor | Impact on Median Household | Impact on Top 1% | Structural Driver |
|---|---|---|---|
| Stock Market | −18% in 401(k) balances | +12% in diversified portfolios | Access to private markets |
| Real Estate | −6% home equity (renters worse off) | +30% in luxury markets | Geographic concentration |
| Student Debt | −12% net worth suppression | No direct impact (low debt levels) | Opportunity cost |
| Private Equity | No exposure | +20% in funds | Capital access |

Conclusion
The net worth in US 2022 data isn’t just about numbers—it’s about the rules of the game. For the median American, wealth accumulation now requires navigating a landscape where housing is unaffordable, wages stagnate, and market volatility erodes savings. For the top 1%, the same year offered opportunities to consolidate power through private assets, tax-efficient structures, and geographic arbitrage. The gap isn’t just financial; it’s systemic. Understanding net worth in US 2022 means recognizing that wealth in America is no longer just a product of hard work, but of access to the right assets, the right networks, and the right timing. The most alarming takeaway? This isn’t temporary. The trends driving net worth in US 2022—rising inequality, asset concentration, and the hollowing out of middle-class wealth—are structural. Without policy interventions that address student debt, homeownership barriers, and market access, the next decade of net worth in US data will look even more polarized. The question isn’t whether wealth inequality will persist; it’s how much further it will go before society reckons with the consequences.Comprehensive FAQs
Q: How did inflation specifically affect net worth in US 2022?
The impact was twofold: first, inflation eroded the purchasing power of cash savings and fixed-income assets (like bonds), directly reducing net worth in US 2022 for retirees and conservative investors. Second, it forced the Federal Reserve to raise interest rates, which cooled home prices in some markets but made mortgages unaffordable for first-time buyers—freezing a key wealth-building tool for millions. The net effect? Households reliant on traditional savings saw their net worth in US 2022 shrink by 3-5%, while those with inflation-resistant assets (real estate, stocks, commodities) fared better.
Q: Were there any bright spots in net worth in US 2022?
Yes, but they were concentrated. The net worth in US 2022 of Black and Latino households grew by 2.1%—the fastest pace in a decade—thanks to pandemic-era stimulus and stronger labor market participation. Small business owners in non-metro areas also saw gains, as local service economies proved resilient. Additionally, early-career professionals in high-demand fields (healthcare, tech, trades) who entered the job market post-2020 saw their net worth in US 2022 metrics rise due to wage growth outpacing inflation. However, these gains were offset by broader trends for the majority.
Q: How did cryptocurrency affect net worth in US 2022 calculations?
For the first time, major surveys (like the Fed’s SCF) began including cryptocurrency holdings in net worth in US 2022 estimates—though only for households reporting them. About 16% of U.S. adults held crypto in 2022, but the impact varied wildly: early adopters with large positions saw their net worth in US 2022 metrics drop by 50-70%, while those who bought in late 2022 (after the crash) had minimal exposure. The net effect on aggregate net worth in US 2022 was negligible, but for the ~5% of households with $100K+ in crypto, the volatility was a major wealth drag.
Q: Can you explain how student loans suppressed net worth in US 2022?
Student debt acts as a wealth vacuum in three ways. First, monthly payments reduce disposable income, limiting ability to save or invest. Second, high debt-to-income ratios make it harder to qualify for mortgages or loans, delaying homeownership—the single largest wealth-builder for middle-class families. Third, borrowers with student loans are 30% less likely to invest in the stock market, missing out on compound growth. The Fed’s data shows that for every $10,000 in student debt, a borrower’s net worth in US 2022 is suppressed by $3,000 on average—due to lower homeownership rates and reduced retirement savings.
Q: What does the net worth in US 2022 data say about retirement security?
The picture is grim. The median retirement account balance fell by 28% in 2022, with 40% of Americans reporting they’ve dipped into retirement savings to cover expenses. The net worth in US 2022 of households nearing retirement (ages 55-64) declined by 8%, as stock market losses and rising healthcare costs outpaced Social Security adjustments. Worse, the gap between those with retirement savings and those without widened: 60% of the top 10% have $1M+ in retirement accounts, while 30% of the bottom 50% have nothing. The data suggests that for many, retirement isn’t a phase of life—it’s a financial cliff.
