
The Complete Overview of Net Worth Percentiles USA 2025
The net worth percentiles USA 2025 paint a picture of polarized prosperity: a small elite riding asset bubbles while the majority treads water. Federal Reserve surveys and wealth-tracking firms like Spectrem Group project that by 2025, the median net worth will sit at $140,000, up from $120,000 in 2022—but this masks deep divides. The top 1% will control 35% of all wealth, a share last seen in the 1920s, while the bottom 40% collectively own less than 1%. This isn’t just about dollars; it’s about access to generational wealth, where homeownership rates among under-35s have dropped to 36%—a collapse that drags entire cohorts into lower percentiles. The data also reveals geographic wealth gradients. Coastal cities and tech hubs dominate the upper percentiles, with San Francisco’s 99th percentile net worth estimated at $12 million, while Detroit’s tops out near $1.5 million. Even within states, disparities emerge: Texas’s oil boom has lifted its 80th percentile above national averages, while New York’s high cost of living compresses middle-class net worth into lower brackets. The net worth percentiles USA 2025 aren’t static—they’re a moving target shaped by local economies, tax policies, and even cultural attitudes toward debt.Historical Background and Evolution
Wealth inequality in the U.S. has always been a function of asset ownership, but the post-2008 era accelerated the trend. The Great Recession wiped out trillions in home equity, pushing millions into negative net worth—only for the recovery to favor those with existing assets. By 2015, the top 10%’s share of wealth rebounded to pre-crisis levels, while the bottom 50% remained 10% poorer than in 2007. The net worth percentiles USA 2025 reflect this legacy: those who entered the market before 2008 (now in their 50s–60s) sit in the 70th–90th percentiles, while millennials—burdened by student loans and delayed homebuying—cluster in the 20th–40th. The pandemic further distorted the curve. Stimulus checks and remote work boosted stock market participation, but the gains were highly concentrated. The S&P 500’s 2020–2023 rally added $20 trillion to household wealth—80% of it captured by the top 10%. Even as wage growth stagnated, asset prices surged, pushing net worth percentiles upward for owners but leaving renters and gig workers behind. The result? A two-tiered recovery: one where the 90th percentile net worth grew by 40%, while the 20th percentile saw no real gain.Core Mechanisms: How It Works
Net worth percentiles are calculated by ranking households by total assets (cash, real estate, investments, retirement accounts) minus liabilities (debt, mortgages). The U.S. Census and Fed’s Survey of Consumer Finances (SCF) provide the raw data, which is then segmented into deciles (10th, 20th, etc.) to show where an individual or family stands. For example, a couple with $500,000 in net worth in 2025 would land in the top 15%, while a single person with $150,000 would be in the 60th percentile. The mechanics behind these percentiles are threefold: 1. Asset Appreciation: Housing and stock markets drive the bulk of wealth growth. A homeowner in the 80th percentile benefits from $100K+ in equity gains since 2020, while a renter sees no such boost. 2. Debt Leverage: Student loans and credit card debt suppress net worth for younger cohorts, pushing them into lower percentiles even with similar incomes. 3. Inheritance and Gifting: The top 10% receive $1 trillion annually in intergenerational transfers, a windfall that inflates their percentiles without earning it. The net worth percentiles USA 2025 aren’t just a reflection of income—they’re a product of policy, luck, and timing. A teacher with a pension and a paid-off home will sit in a higher percentile than a tech CEO with $5 million in stock options but $2 million in student debt.Key Benefits and Crucial Impact
Understanding net worth percentiles isn’t just academic—it’s a strategic tool for individuals, investors, and policymakers. For households, knowing where they stand helps set realistic financial goals. A family in the 50th percentile ($140K net worth) might prioritize debt payoff, while someone in the 95th ($2M+) can afford aggressive tax planning. For employers, these percentiles reveal retention risks: workers in the 70th–80th range are more likely to seek side income or career shifts if their net worth stagnates. The impact on society is more profound. Lower percentiles correlate with poorer health outcomes, lower education attainment, and political disengagement. Studies show that households in the bottom 30% of net worth percentiles are three times more likely to report financial stress, which spills into community instability. Meanwhile, the top deciles’ spending power drives luxury markets, private education, and political influence—creating a feedback loop where wealth begets more wealth. > "Wealth isn’t just about money—it’s about the options money buys. If you’re in the 90th percentile, you can take a career risk. If you’re in the 20th, you can’t. That’s the inequality we’re not talking about enough." — Edward N. Wolff, Professor of Economics at NYUMajor Advantages
- Financial Clarity: Percentiles provide a benchmark against peers, helping individuals assess whether their savings, investments, or debt levels are on track.
- Policy Targeting: Governments use these data points to design tax incentives, housing programs, or student debt relief aimed at specific percentiles.
- Investment Alignment: High-net-worth individuals (90th+ percentiles) can tailor portfolios to low-volatility assets or alternative investments, while middle-class families focus on liquidity and safety.
- Intergenerational Planning: Families in the 70th–90th percentiles can structure trusts or gifting strategies to preserve wealth across generations, while lower percentiles may need to prioritize asset-building tools like Roth IRAs or employer matches.
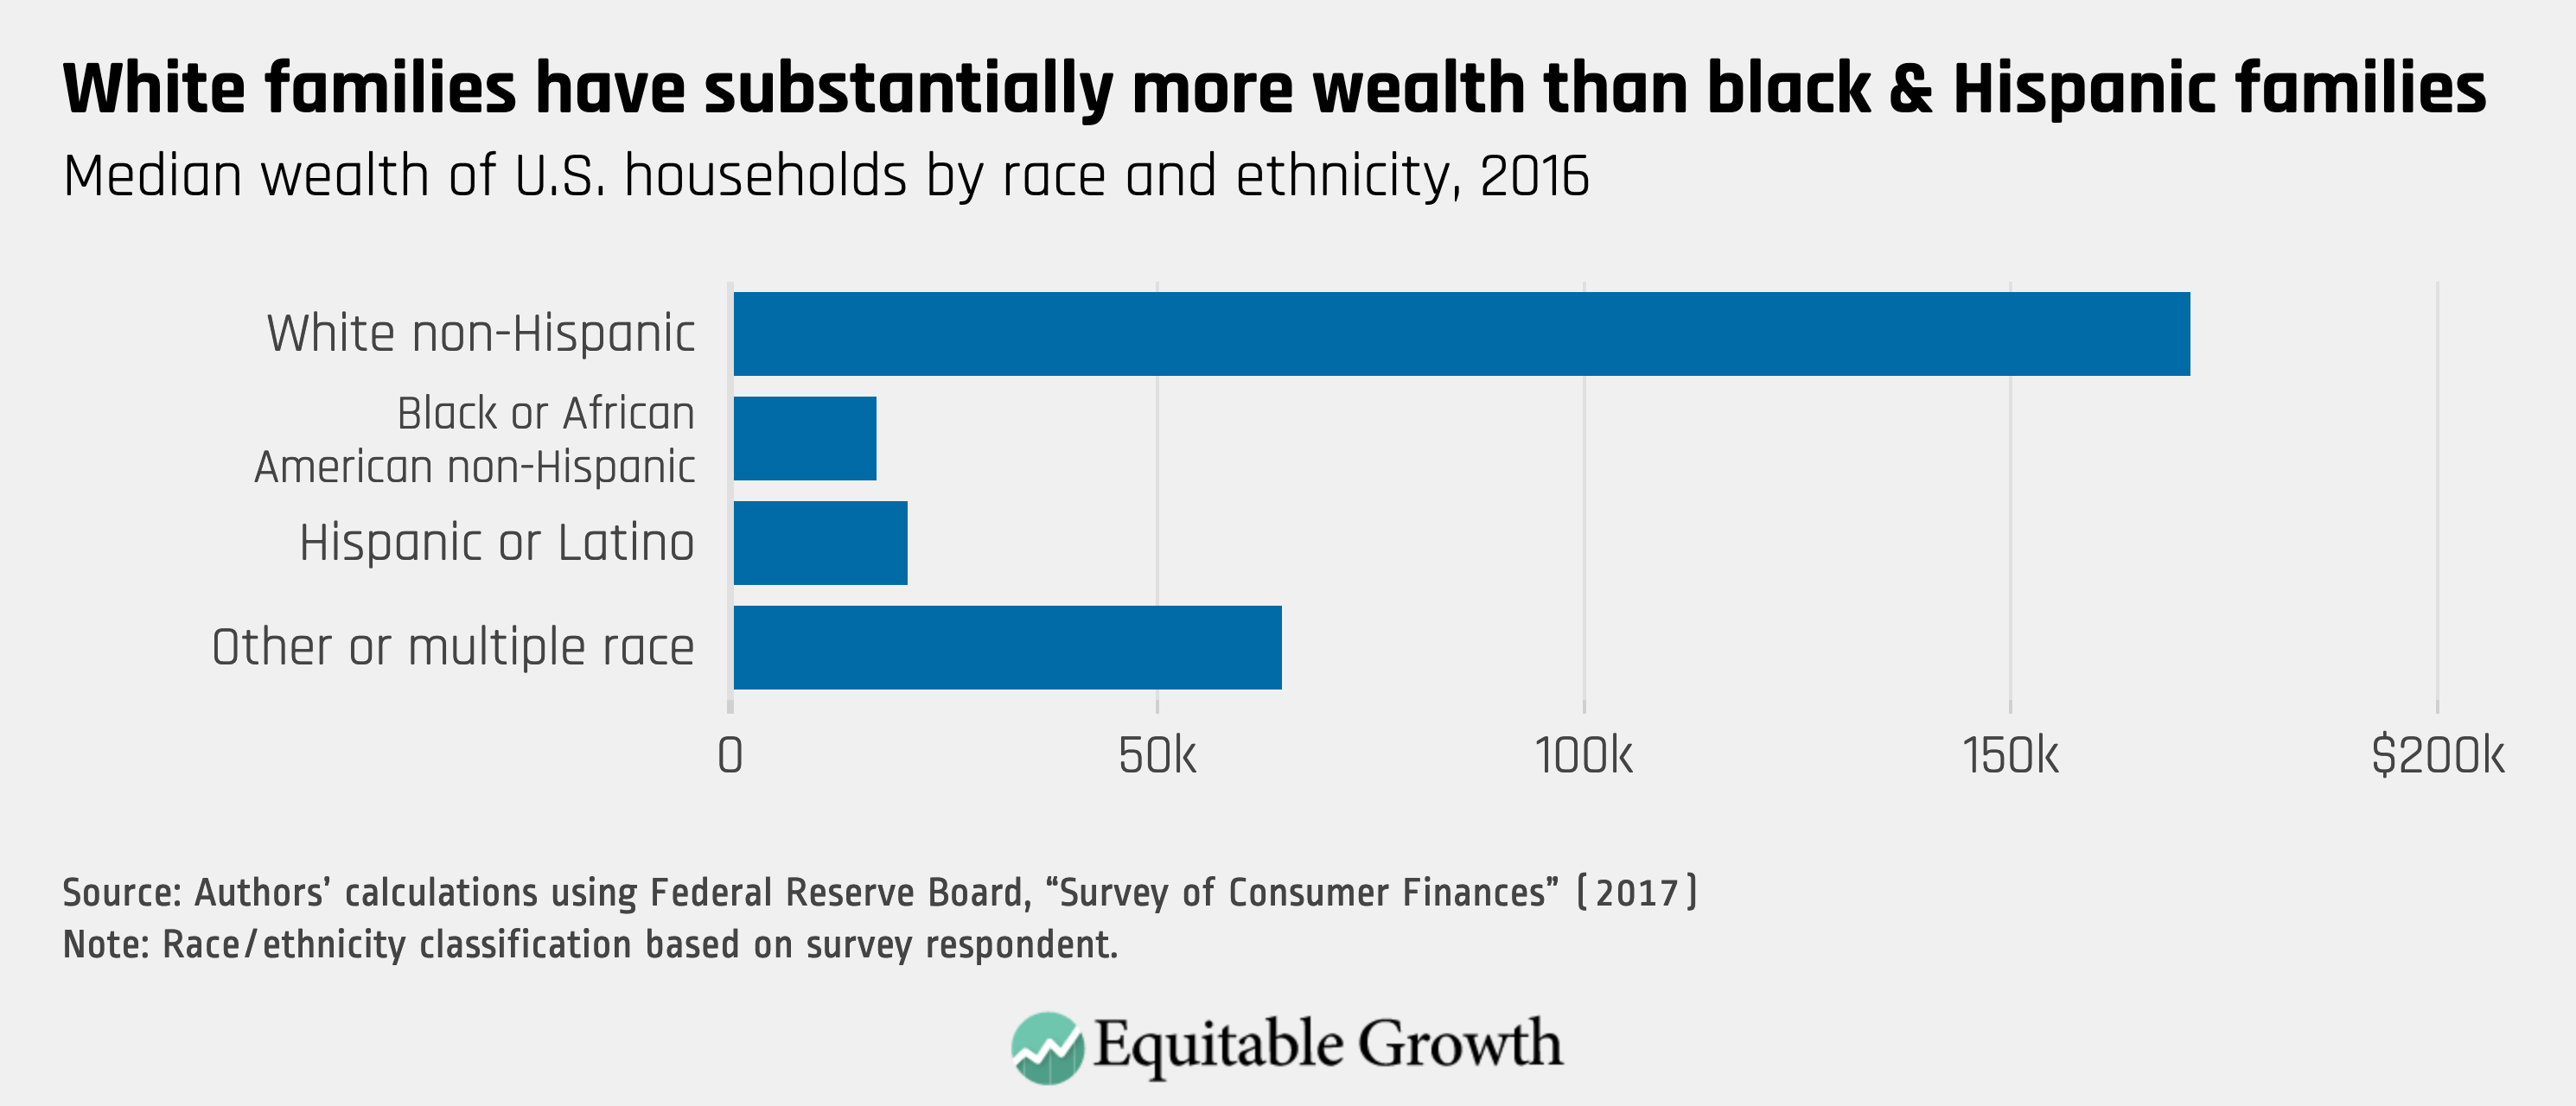
Comparative Analysis
| Metric | Net Worth Percentiles USA 2025 (Est.) |
|---|---|
| Median Net Worth | $140,000 (up from $120K in 2022) |
| Top 1% Threshold | $12 million+ (vs. $10M in 2020) |
| Bottom 50% Share of Wealth | <1% (unchanged from 2019) |
| Homeownership Rate (90th+ Percentile) | 92% (vs. 45% for bottom 20%) |
Future Trends and Innovations
The net worth percentiles USA 2025 are just a snapshot—2026–2030 will test whether the system corrects or deepens. Three trends loom largest: 1. AI and Automation: Productivity gains will boost corporate profits, but only shareholders and executives will see net worth percentiles rise. Wage earners may see stagnant growth. 2. Policy Shifts: If Biden’s wealth tax or Trump’s capital gains cuts prevail, the 90th+ percentiles could face heavier burdens—or lighter ones, depending on the outcome. 3. Crypto and Alternatives: Bitcoin and private markets (VC, real estate syndications) may bypass traditional percentiles, creating a new ultra-wealthy tier outside Fed tracking. The biggest wild card? Housing. If mortgage rates stay above 6%, homeownership—key to climbing percentiles—will remain out of reach for younger buyers, locking them into lower brackets. Meanwhile, rental income strategies could emerge as a middle-class hedge, but they won’t move the needle for those in the bottom 30%.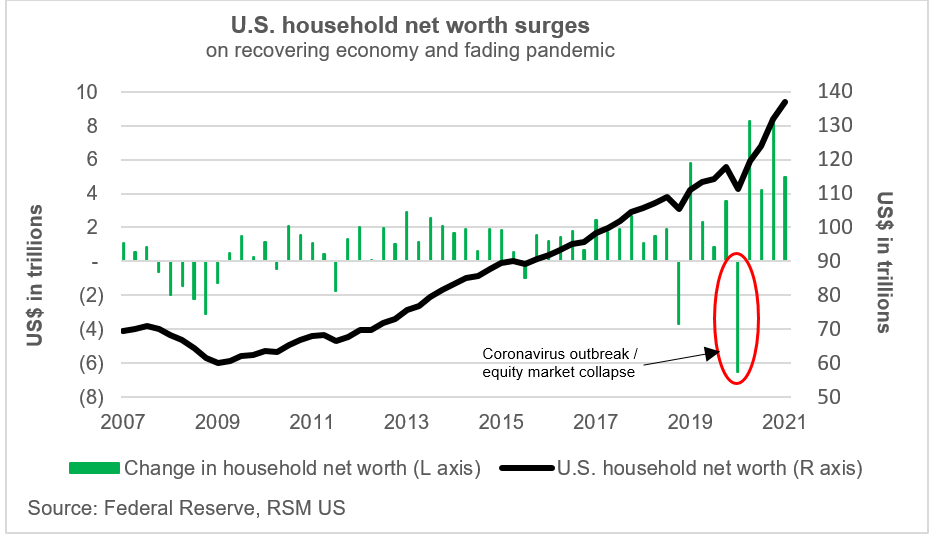
Conclusion
The net worth percentiles USA 2025 aren’t just numbers—they’re a diagnostic tool for an economy where wealth is increasingly inherited or asset-backed. The data shows that policy matters: countries with stronger social safety nets (e.g., Nordic models) have flatter wealth curves. But in the U.S., the trend is clear: without intervention, the top deciles will continue to pull ahead, while the middle classes scramble to stay afloat. For individuals, the takeaway is simple: net worth growth now depends on ownership. Stocks, real estate, or even crypto can bridge percentile gaps—but only if timed right. The question for 2025 isn’t whether the divide exists. It’s whether America will redesign the rules or watch the percentiles drift further apart.Comprehensive FAQs
Q: How are net worth percentiles calculated in the USA?
The Federal Reserve’s Survey of Consumer Finances ranks households by total assets minus liabilities, then divides them into deciles (10th, 20th, etc.). For example, the 90th percentile includes the wealthiest 10% of families.
Q: What’s the median net worth in the USA for 2025?
Estimates place it at $140,000, up from $120,000 in 2022, but this masks regional and demographic variations. Coastal cities skew higher, while Rust Belt metros lag.
Q: Does homeownership significantly impact net worth percentiles?
Absolutely. Homeowners in the 80th percentile have $500K+ in net worth, while renters in the same income bracket may sit in the 50th. Equity is the single biggest driver of percentile jumps.
Q: How do student loans affect net worth percentiles?
They suppress percentiles by $30K–$50K for borrowers. A graduate with $100K in debt and $60K in savings may land in the 30th percentile, while a non-borrower with similar income could reach the 50th.
Q: Are net worth percentiles higher in states with no income tax?
Not necessarily. Texas and Florida see higher top percentiles due to business growth, but their median net worth remains below national averages. Taxes aren’t the sole driver—job markets and housing costs matter more.
Q: Can I improve my net worth percentile without increasing income?
Yes, but it requires strategic asset-building: paying down high-interest debt, investing in index funds, or buying a home. Even small steps (e.g., maxing a 401(k) match) can shift you 5–10 percentiles over time.
Q: How do inheritance and gifting impact net worth percentiles?
They’re massive accelerants. The top 10% receive $1 trillion/year in transfers, pushing heirs into higher percentiles instantly. For example, a $500K inheritance could lift a family from the 60th to the 85th percentile.
Q: Will AI and automation widen net worth percentiles in 2025–2030?
Likely. Corporate profits will rise, but only shareholders and executives will see net worth percentiles climb. Wage earners may see stagnant growth unless they own equity or pivot to high-demand skills.
