Where It All Began
The modern study of net worth accumulation by age traces back to the 1970s, when the Federal Reserve began publishing its Survey of Consumer Finances. Early data showed a clean arc: wealth rose steadily from 25 to 65, then plateaued. Economists at the time attributed this to life stages—education loans in the 20s, home purchases in the 30s, and asset growth in the 40s and beyond. But beneath the surface, something else was at work. The post-WWII boom had created a compressed wealth timeline. A 35-year-old in 1975 could buy a home with a 20% down payment, thanks to low interest rates and wages that outpaced inflation. The distribution of net worth by age reflected this stability: by 50, most households had liquid assets, retirement accounts, and equity in their primary residence. The cracks appeared in the 1980s. Deregulation, the rise of financialization, and the hollowing out of manufacturing jobs began to reshape the curve. A 1989 study by the Brookings Institution noted that the median net worth of households headed by someone 35–44 had stagnated compared to the prior decade. The culprit? Student debt, which had ballooned from $25 billion in 1980 to $150 billion by 1990. For the first time, a generation faced the prospect of entering their peak earning years with debt that wouldn’t be fully paid off until their 50s. The age-related wealth gap wasn’t just about savings rates—it was about the cost of entry into adulthood itself.The Early Signs
By the mid-1990s, the wealth trajectory by age had begun to diverge sharply between owners and renters. Homeownership rates for under-35s dropped from 44% in 1980 to 36% by 1995, even as home values surged. Economists like Edward Wolff of NYU observed that the distribution of net worth by age was becoming bimodal: those who owned assets early (often through inheritance or family support) saw compounding growth, while those who didn’t faced a wealth ceiling. The dot-com crash of 2000 exposed the fragility of this divide. Stock market exposure, once a path to wealth for middle-class families, became a gamble. A 40-year-old with a 401(k) in 2000 saw its value drop by nearly 20% overnight—an erasure that took years to recover. The real turning point came with the 2008 financial crisis. The net worth by age data for those under 40 showed a permanent reset. Home values plummeted, unemployment spiked, and wages stagnated. A Pew Research analysis found that the median net worth of households headed by someone under 35 had fallen 83% from 1983 to 2010. For the first time in modern history, younger cohorts weren’t just poorer than their parents—they were structurally disadvantaged in ways that policy couldn’t easily fix.The Turning Point
The aftermath of 2008 didn’t just slow wealth accumulation; it redrew the rules. The distribution of net worth by age that had once followed a predictable S-curve now resembled a staircase with missing steps. The missing step? The 20s and early 30s, where stagnant wages, soaring education costs, and the death of the middle-class job left millions in limbo. The Fed’s data showed that by 2016, the median net worth of a 25–34-year-old was $50,000—half what it had been in 1989, adjusted for inflation. Meanwhile, the top 10% of households in that age group saw their wealth grow three times faster, thanks to asset ownership and inheritance. The shift wasn’t just economic; it was cultural. The idea that hard work alone would lead to wealth had become a myth. A 2017 study by the Urban Institute found that 60% of wealth accumulation for those under 40 came from inheritance or gifts—a figure that had doubled since the 1990s. The age-based wealth divide had become a class divide in disguise."Wealth isn’t just about income anymore. It’s about who you know, what you inherit, and whether you were born into a system that already gave you a head start." — Rachel Schneider, economist, Federal Reserve Bank of St. Louis
The Build-Up, Year by Year
| Period | Key Changes |
|---|---|
| 1980–1990 |
|
| 1990–2000 |
|
| 2000–2010 |
|
| 2010–2020 |
|
| 2020–Present |
|
Lessons From the Journey
- Wealth isn’t linear anymore. The distribution of net worth by age now follows a "winner-takes-most" model, where early asset ownership creates compounding advantages that later entrants can’t overcome.
- Policy lags culture. Minimum wage increases, student debt relief, and housing reforms arrive too late to fix structural imbalances created decades earlier.
- Liquidity matters more than income. A $100,000 salary with no assets is far less valuable than a $60,000 salary with a paid-off home or inherited stocks.
- The 50-year rule is dead. For the first time, the median net worth of a 50-year-old is lower than it was for a 45-year-old in 1990—adjusted for inflation.
Where Things Stand Today
Today, the wealth accumulation by age data tells two stories. For the top 20%, the curve is steeper than ever. A 35-year-old in the top decile has a 70% chance of being wealthier than their parents at the same age. Their net worth grows through stock options, real estate flips, and inherited capital. The bottom 40%, meanwhile, face a wealth ceiling. A 2023 Federal Reserve report found that 65% of households under 35 have no retirement savings whatsoever. The age-based wealth gap is now wider than the racial wealth gap in some metrics. The most alarming trend? The disappearing middle. The distribution of net worth by age for those 40–55 shows a hollowing out—fewer households in the $100,000–$500,000 range, and more clustered at the extremes. The safety net of a middle-class retirement is eroding. Even those who save aggressively now face a trilemma: work until 70, downsize their home, or rely on family.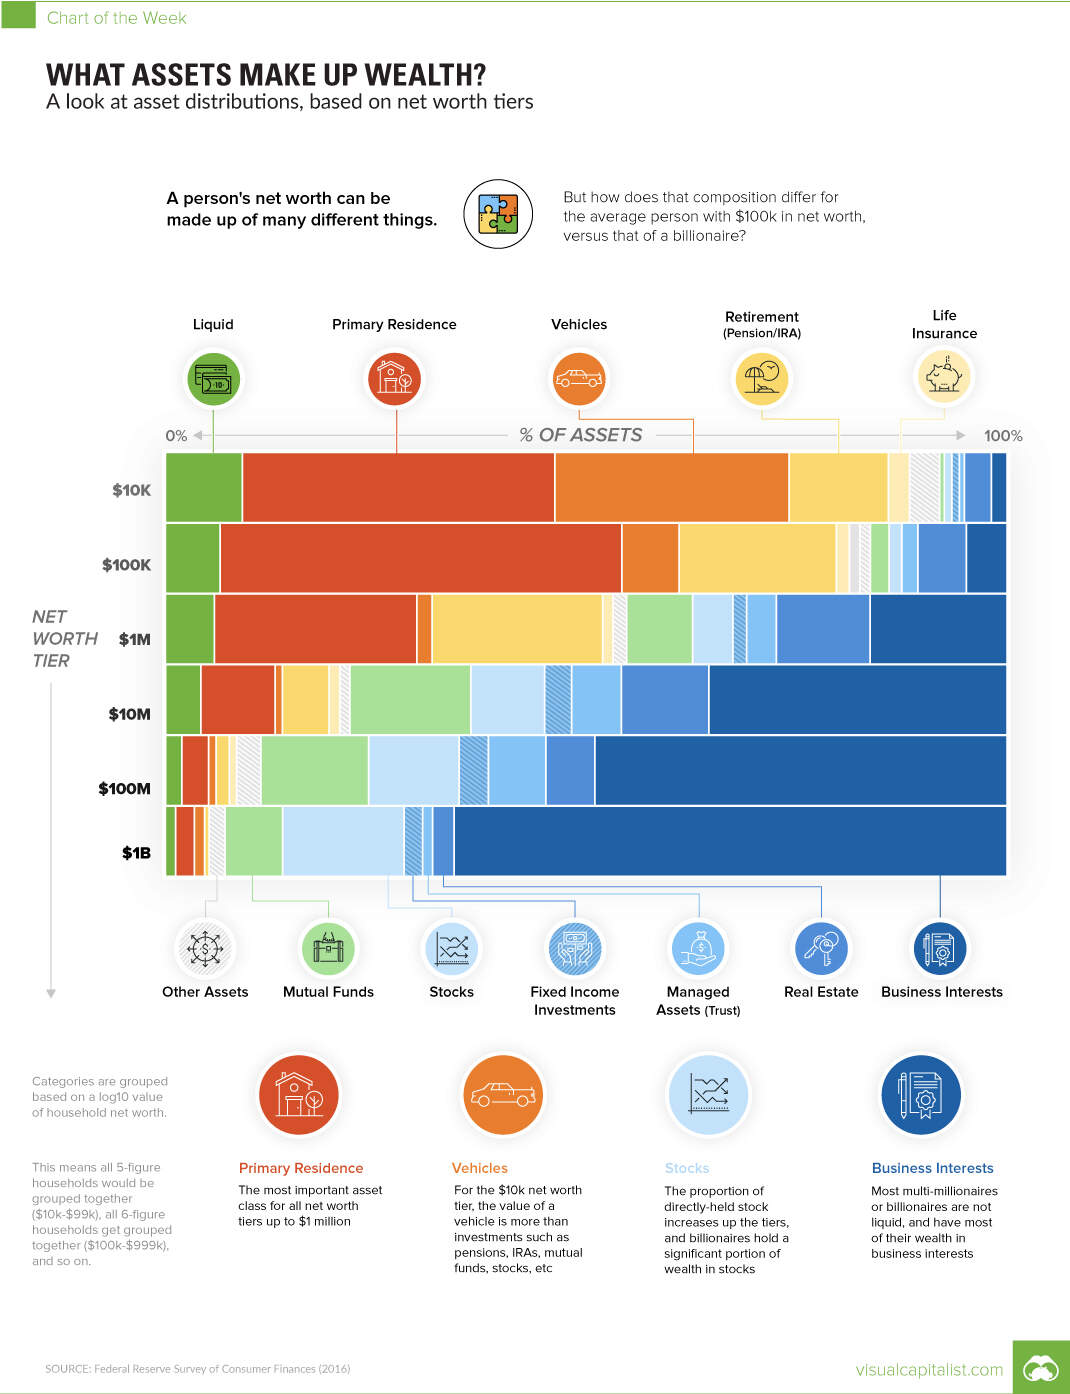
Conclusion
The distribution of net worth by age isn’t just a financial metric—it’s a report card on economic mobility. The data doesn’t lie: the system is rigged for those who start with advantages, and the advantages are hereditary. The question isn’t whether wealth inequality exists; it’s whether society can accept that the age at which wealth matters most has shifted from 40 to 50—and that for millions, the shift means forever falling behind. The solution won’t come from savings tips or side hustles alone. It requires structural changes: student debt cancellation, asset-building policies for young adults, and a reckoning with the idea that homeownership should be a right, not a privilege. Until then, the wealth curve by age will keep bending upward—for some—and flattening into a floor for others.Comprehensive FAQs
Q: Why does net worth grow so slowly for young adults today?
The combination of student debt, stagnant wages, and unaffordable housing creates a wealth drag in the 20s and 30s. Unlike past generations, young adults now face three major expenses simultaneously: education, rent/mortgage, and healthcare—with little disposable income left for savings.
Q: At what age does net worth typically peak?
Historically, net worth peaked around 65–70, when home equity and retirement accounts matured. Today, the peak has delayed to 70+ for many, while others never reach it due to longevity risks and healthcare costs in retirement.
Q: How does inheritance affect the distribution of net worth by age?
Inheritance now accounts for up to 70% of wealth transfers in the U.S., with the largest shares going to those already in the top 10%. A 2022 study found that 60% of millennials expect an inheritance, but only 30% will receive one—and those who do see wealth jumps of 30–50%.
Q: Can someone in their 30s or 40s still build significant wealth?
Yes, but the playbook has changed. Traditional paths (homeownership, 401(k)s) are less reliable. Instead, high-income skills, side businesses, and early real estate investments are the new levers. However, time is the enemy—each decade lost to debt or low savings compounds the gap.
Q: Why do some 50-year-olds have lower net worth than their parents at the same age?
This reflects three decades of economic shifts: the collapse of defined-benefit pensions, the housing bubble burst, and wage stagnation. A 50-year-old today may have student debt, no home equity, and a 401(k) exposed to market downturns—factors that didn’t exist for their parents.
Q: What’s the biggest myth about net worth by age?
The myth that "hard work alone will make you wealthy." The data shows that asset ownership, inheritance, and timing matter far more than effort. Two people with identical incomes can have net worths differing by 500% due to when they bought their first home or received a windfall.
Q: How does the distribution of net worth by age differ by race?
The racial wealth gap worsens with age. A white household headed by someone 50–64 has 10 times the median net worth of a Black household of the same age. For those under 35, the gap is 5:1. This reflects generational redlining, wage disparities, and unequal access to education and capital.
