Where It All Began
The origins of the net worth blog by age trace back to the late 2000s, when financial transparency was still radical. Before apps like Mint or YNAB, tracking net worth required manual calculations—adding assets, subtracting debts, and updating the total monthly. Early adopters were outliers: programmers, data analysts, and finance nerds who treated wealth like open-source code. They shared their progress on personal blogs, often with disclaimers like "This is not investment advice" or "Your mileage may vary." The tone was matter-of-fact, almost clinical, because the goal wasn’t to brag. It was to normalize the conversation. The turning point came when these blogs started organizing data by age brackets. A 25-year-old’s net worth looked different from a 35-year-old’s, and the differences weren’t just about income—they reflected life stages. Student loans dominated the 20s. Homeownership crept in by the 30s. Investments became the wild card after 40. The blogs didn’t just show numbers; they revealed the hidden rules of wealth accumulation. For example, the "FIRE movement" (Financial Independence, Retire Early) gained traction because these blogs proved that retiring by 40 wasn’t a fantasy—it was a math problem with variables you could control.The Early Signs
The first net worth blogs by age were crude by today’s standards. They lacked the polished dashboards of modern tools, but their raw honesty resonated. One of the earliest, maintained by a couple in their early 30s, tracked their journey from $0 to $150,000 in five years. The posts weren’t about the destination; they were about the process. "We saved $3,000 this month by cutting subscriptions and negotiating our phone bill," they’d write. The comments section became a forum for strangers to share their own struggles—rent hikes, medical bills, or the shock of realizing their 401(k) balance was half what they expected. What made these blogs compelling wasn’t the wealth itself, but the psychology of tracking. Seeing progress in black and white—$52,000 at 27, $89,000 at 30—created a feedback loop. Users who updated their net worth monthly reported feeling more in control. The blogs also exposed a harsh truth: wealth wasn’t just about earning more; it was about avoiding leaks. A single unplanned expense could derail years of saving. The early net worth blogs by age didn’t just inform; they forced readers to confront their own financial habits.The Turning Point
The shift from niche curiosity to mainstream obsession happened in 2013, when a Reddit thread titled "What’s your net worth?" went viral. The responses weren’t just numbers—they were stories. A nurse in her 30s with $120,000. A teacher in his 40s with $20,000. The disparity wasn’t just financial; it was generational. Millennials entering the workforce faced stagnant wages, while their parents’ net worth blogs by age from the 2000s showed steady growth. The frustration boiled over into movements like the Average Joe FIRE community, where people documented how they’d retire early despite average salaries. The turning point wasn’t just about the data—it was about the cultural permission to care. For decades, discussing money had been taboo. But when blogs like The White Coat Investor (a physician’s net worth journey) or Mr. Money Mustache (a former engineer’s path to financial freedom) gained traction, the stigma faded. Suddenly, a net worth blog by age wasn’t just for the wealthy. It was for anyone who wanted to understand the system they were trapped in."Wealth isn’t about how much you make. It’s about how much you keep—and how you measure it." — Early Retirement Extreme founder, 2014

The Build-Up, Year by Year
The evolution of the net worth blog by age can be broken into three phases, each reflecting broader economic and technological changes.| Period | What Happened / What Changed |
|---|---|
| 2010–2014 | Early adopters used manual spreadsheets or basic blog posts. The focus was on transparency over aesthetics—raw numbers with minimal commentary. The rise of Reddit and niche forums allowed for community-driven comparisons. Key insight: Wealth gaps were visible even among peers. |
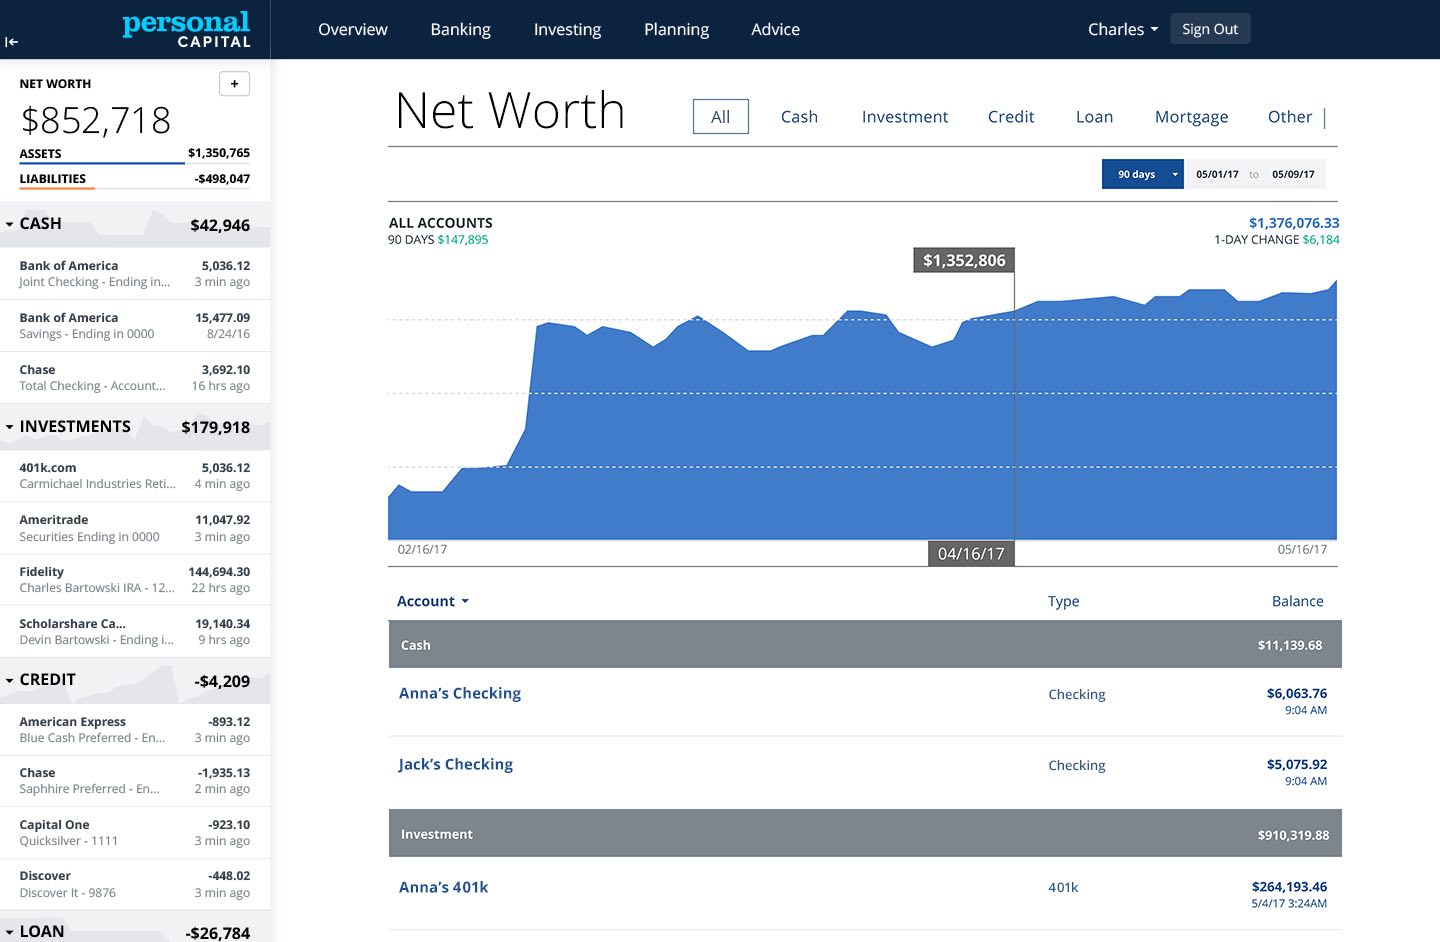
| 2015–2019 | Tools like Networthify and Personal Capital automated tracking. Blogs became more data-driven, with benchmarks by age, location, and career. The FIRE movement gained momentum, and net worth blogs by age started including liquidity ratios (how much you could withdraw annually without depleting savings). Debates erupted over "coast FI" (financial independence without retiring) vs. traditional retirement. |
| 2020–Present | AI and algorithmic tools (e.g., YNAB’s net worth tracking) made real-time updates standard. The pandemic accelerated interest in side hustles and alternative income streams, reflected in blogs that now include gig economy earnings. The conversation shifted from "How much should I have?" to "How do I protect what I have?"—with discussions on inflation, market volatility, and generational wealth transfers. |
Lessons From the Journey
The net worth blog by age phenomenon taught several hard-won lessons:- Wealth is relative—but benchmarks matter. A $500,000 net worth in San Francisco is different from $500,000 in rural Alabama. Blogs forced readers to adjust expectations based on cost of living, not just raw numbers.
- Small habits compound. The blogs that stuck weren’t about big wins—they were about consistent, often boring, actions: automating savings, negotiating bills, or investing $200 monthly.
- Debt isn’t the enemy—leverage is. Early net worth blogs by age treated all debt as bad, but later iterations distinguished between "good debt" (mortgages, student loans for high-earning fields) and "bad debt" (consumer loans, credit cards).
- The system is rigged—but you can work around it. The most successful blogs didn’t just track money; they reverse-engineered the rules, showing how to exploit tax loopholes, negotiate salaries, or invest in assets that appreciate faster than inflation.
Where Things Stand Today
Today, a net worth blog by age is less about bragging and more about financial self-defense. The tools have evolved—apps now offer net worth tracking with AI-driven insights, while platforms like r/financialindependence subreddit host thousands of anonymized comparisons. The conversation has also diversified. Blogs now include discussions on inherited wealth, crypto portfolios, and the gig economy’s impact on long-term savings. Yet the core question remains: What’s a "good" net worth for my age? The answer isn’t simple. A 35-year-old in tech might aim for $500,000, while a nurse in the same age bracket might target $150,000. The blogs that thrive today don’t just show numbers—they contextualize them. They explain why a $1 million net worth at 40 might not be enough in a high-cost city, or why a $200,000 net worth at 50 could still mean financial stress if housing costs are 40% of income. The modern net worth blog by age has also become a cultural barometer. The rise of "quiet luxury" spending in the 2020s, for example, is reflected in blogs where readers track not just savings but lifestyle inflation—the creeping expenses that eat into progress. Meanwhile, the generational wealth gap is laid bare in side-by-side comparisons: a 30-year-old inheriting $300,000 vs. one starting from $0.
Conclusion
The net worth blog by age started as a personal experiment and became a movement. It proved that wealth isn’t just about how much you earn—it’s about how you measure, protect, and grow what you have. The blogs that endure aren’t the ones with the highest numbers; they’re the ones that ask the right questions. How much do I need to feel secure? What trade-offs am I willing to make? Can I retire early, or do I need to redefine success? As the economy shifts—with remote work, AI-driven jobs, and unpredictable markets—the net worth blog by age will continue to adapt. But its core purpose remains: to turn abstract financial concepts into actionable, personal truths. Whether you’re tracking your first $10,000 or your tenth, the blogs remind us that wealth isn’t about keeping up. It’s about knowing where you stand—and what you’re willing to do about it.Comprehensive FAQs
Q: Is tracking net worth by age realistic for someone starting at 25?
A: Absolutely. The key is starting small and staying consistent. Many early adopters began with manual spreadsheets or free tools like Google Sheets. The goal isn’t to hit a specific number by a certain age—it’s to build the habit of tracking. For example, a 25-year-old with $10,000 in savings can still use a net worth blog by age to project growth based on income, expenses, and investment returns. The blogs that helped early users often included templates for beginners, emphasizing that even modest progress is meaningful.
Q: How do net worth blogs by age handle inflation?
A: Most modern blogs adjust for inflation by using real (inflation-adjusted) dollars rather than nominal values. For instance, a $500,000 net worth in 2023 might be compared to a $400,000 net worth in 2015 to account for rising costs. Some platforms also include liquidity benchmarks, showing how much you could withdraw annually without depleting savings, adjusted for inflation. The lesson from these blogs is clear: nominal numbers mean little if they don’t account for purchasing power.
Q: Can a net worth blog by age help with debt management?
A: Yes, but with a critical twist. Early blogs treated all debt as bad, but today’s versions categorize debt—distinguishing between high-interest consumer debt (credit cards, payday loans) and lower-interest, asset-building debt (mortgages, student loans for high-earning fields). A net worth blog by age can track debt paydown progress alongside savings, showing how reducing debt accelerates wealth accumulation. For example, a blogger might highlight how paying off a $30,000 car loan freed up $500/month for investments, increasing their net worth by $6,000 annually.
Q: Are there risks to publicly sharing net worth by age?
A: There are three main risks: 1. Privacy concerns—some blogs use anonymized data, but others share exact numbers, which can attract scams or unwanted attention. 2. Comparison anxiety—seeing peers with higher net worths can lead to unhealthy financial decisions (e.g., taking risky investments). 3. Over-optimization—focusing solely on net worth can neglect other life goals (health, relationships, career fulfillment). Most successful blogs balance transparency with caution, using aggregated data or broad age ranges to protect individuals. The best practice? Treat a net worth blog by age as a personal tool, not a public resume.
Q: How do net worth blogs by age adapt to economic downturns?
A: The most resilient blogs shift focus from growth to preservation. During downturns, they: - Highlight defensive asset allocation (e.g., shifting from stocks to bonds during recessions). - Emphasize emergency funds as a non-negotiable. - Adjust benchmarks to reflect lower expected returns (e.g., reducing FIRE withdrawal rates from 4% to 3.5%). - Include scenario planning, showing how different market conditions affect net worth trajectories. For example, a blog might simulate a 2008-style crash and demonstrate how a diversified portfolio recovers over time.
