Breaking Down the Numbers
The financial reality of a houses salary hinges on two variables: what a job actually pays and what a home costs in a given location. These aren’t static figures. Over the past decade, wage growth has lagged behind property price inflation in most major economies, particularly in urban centers. In the UK, for example, average weekly earnings rose by around 6% between 2010 and 2023, while house prices climbed by nearly 80% in the same period—according to the Office for National Statistics and Nationwide Building Society data. The result? A houses salary in 2023 requires more than it did in 2010, even if nominal wages have ticked up. The disconnect isn’t just about affordability; it’s about timing. For someone entering the job market today, the prospect of ever earning a houses salary in a city like London or New York feels increasingly distant. Industry reports suggest that to buy a median-priced home in London, a buyer would need a household income of roughly £80,000—well above the UK’s median full-time salary of £38,000. Even in more affordable regions, the math is brutal. In Manchester, where property prices are lower, a houses salary might still require earnings in the £40,000–£50,000 range, depending on mortgage rates and deposit sizes. The problem isn’t just the size of the salary; it’s the cumulative impact of student loans, rising living costs, and the erosion of savings from stagnant wage growth.The Verified Baseline
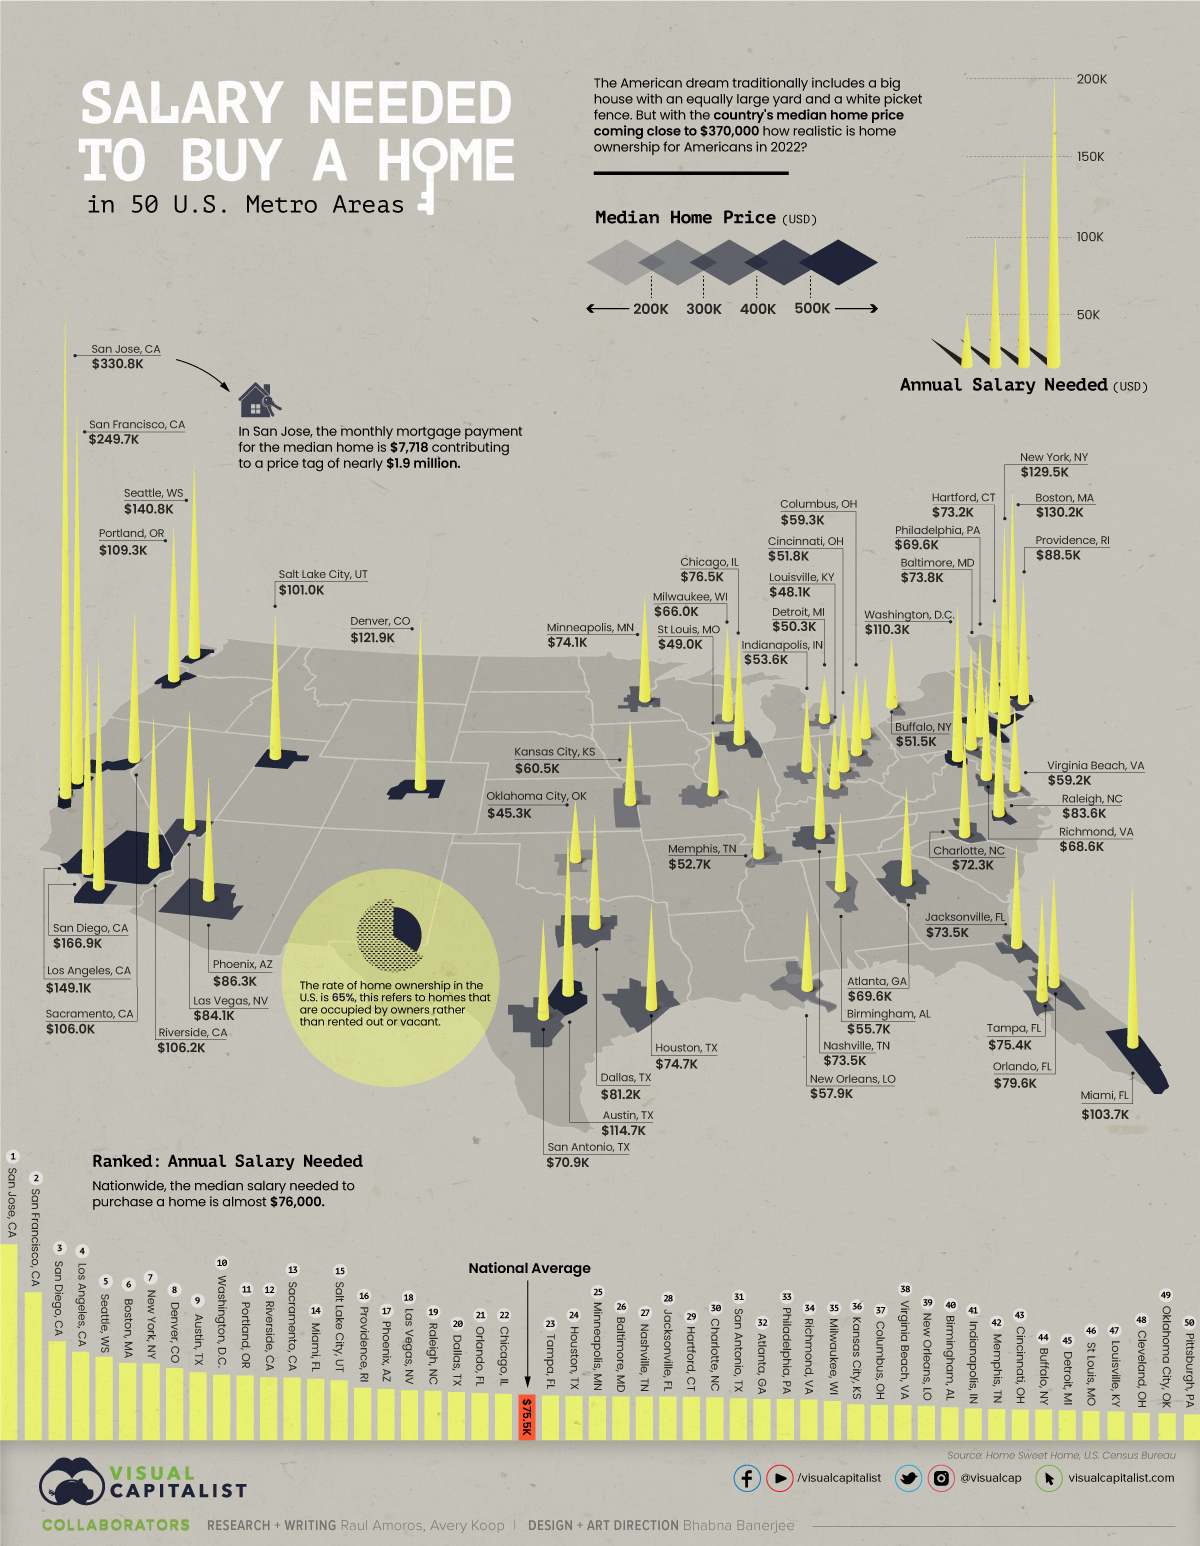
Publicly available data paints a clear picture of where houses salaries stand in 2024. Government and industry reports provide benchmarks, though they rarely account for individual circumstances. In the US, the Federal Housing Finance Agency’s House Price Index shows that the median home price in the first quarter of 2024 was around $420,000. To afford a mortgage on that property—assuming a 20% down payment and a 6.5% interest rate—would require a gross annual income of approximately $110,000, according to standard lending guidelines. That’s roughly double the median household income of $75,000. In the UK, the English Housing Survey reports that first-time buyers now need a deposit of £50,000 or more to enter the market in many areas. With mortgage rates hovering around 5–6%, the monthly payments on a £300,000 home would consume about 35% of a £60,000 salary—leaving little room for other expenses. These figures aren’t theoretical; they’re derived from real lending data and government housing reports. The baseline is stark: in most developed economies, a houses salary is no longer a modest middle-class aspiration but a high-earner’s necessity.What the Estimates Suggest
Where verified data ends, speculation and industry estimates begin. Analysts at firms like Savills and Redfin suggest that in the next five years, the gap between wages and housing costs will widen further unless policy interventions—such as increased social housing or rent controls—emerge. Their projections assume continued wage stagnation and property price growth, particularly in tech hubs and coastal cities. For instance, a houses salary in San Francisco might require earnings of $180,000 or more by 2029, up from $150,000 today, due to both higher prices and tighter lending standards post-2024. Private equity and real estate consultants often cite "affordability ratios" to highlight the issue. One widely referenced estimate places the houses salary threshold in London at £100,000 for a family home, based on a 4.5x income multiple—a rule of thumb used by mortgage lenders. However, this figure is fluid; it shifts with interest rates, deposit sizes, and local market conditions. The estimates carry caveats: they don’t account for regional disparities, they assume no major economic shocks, and they ignore the role of inheritance or shared ownership schemes. Yet they serve as a reality check for job seekers and policymakers alike.
Case Study: A Closer Look
Consider the career path of a mid-level data analyst in Berlin. Three years into their role, they earn €65,000 gross annually—a salary that, on paper, aligns with the city’s houses salary benchmarks. Berlin’s property market is relatively affordable compared to London or Paris, but the analyst’s situation is complicated by student debt and the cost of living in a gentrifying neighborhood. Their rent consumes 30% of their take-home pay, leaving little for savings or a future down payment. The decision to stay in Berlin hinges on whether their career trajectory can bridge the gap between current earnings and homeownership. Promotions might push their salary to €80,000 within five years, but even then, the deposit required for a €400,000 property (the Berlin average) would still be out of reach without family support or a side income. Their houses salary isn’t a fixed number; it’s a moving target tied to market conditions, personal debt, and future opportunities."In Berlin, you can earn enough to live comfortably, but not enough to buy a home in the areas you actually want to live. It’s a choice between stability and ambition—and right now, ambition often loses." — An anonymous mid-career tech professional, quoted in a 2023 Handelsblatt feature
| Factor | Estimated Impact |
|---|---|
| Current Salary (€65k) | Covers rent but leaves <5% of income for savings after taxes and living costs. |
| Projected Salary (€80k in 5 years) | Could support a €30,000–€40,000 deposit in 5–7 years, assuming no major economic shifts. |
| Student Debt (€25k) | Delays homeownership by 2–3 years, depending on repayment terms. |
What This Means Going Forward
The erosion of the houses salary concept has forced a reckoning with traditional career paths. For younger generations, the idea of a linear progression—education, stable job, homeownership—is no longer guaranteed. Instead, many are turning to alternative strategies: co-living arrangements, remote work in lower-cost regions, or delaying major life milestones like marriage or parenthood. The shift isn’t just about housing; it’s about redefining what financial security looks like in an era of precarious employment. Employers and policymakers are beginning to take notice. Some companies now advertise housing stipends or relocation packages as part of compensation, recognizing that a houses salary in one city may not translate to another. Meanwhile, governments are experimenting with measures like shared equity schemes or first-time buyer grants, though their long-term impact remains unclear. The conversation around houses salaries has evolved from a personal financial concern to a systemic issue—one that touches on urban planning, wage policies, and intergenerational equity.
Conclusion
The houses salary is more than a financial threshold; it’s a barometer of economic health. When it rises faster than wages, it signals deeper problems—stagnant productivity, unaffordable cities, and the hollowing out of middle-class stability. The data is clear: in many places, the houses salary is no longer a realistic expectation for the average worker. Yet the term persists, not as a relic of the past, but as a reminder of what’s at stake. For individuals, the message is simple: career choices must now account for housing costs in ways previous generations didn’t anticipate. For societies, the challenge is to close the gap before the houses salary becomes a luxury reserved for the few. The conversation has only just begun.Comprehensive FAQs
Q: What exactly constitutes a houses salary?
A houses salary is the income level needed to comfortably afford a mortgage or rent in a given location, typically covering 25–35% of take-home pay. The exact figure varies by city, property prices, and interest rates. For example, in London, it’s often cited as £80,000+, while in smaller UK towns, £40,000–£50,000 may suffice.
Q: How do student loans affect the ability to earn a houses salary?
Student debt delays homeownership by reducing disposable income and limiting savings for deposits. In the UK, graduates with loans may need to earn 10–20% more than non-graduates to achieve the same houses salary threshold, due to higher monthly repayments. The impact is most acute for those in lower-paying professions.
Q: Can remote work help bridge the houses salary gap?
Yes, but with caveats. Moving to a lower-cost region can stretch a salary further, but tax implications, career growth opportunities, and lifestyle trade-offs must be considered. Some professionals earn a houses salary in a high-cost city but relocate to afford a home elsewhere—a strategy that works for tech workers but may not suit all industries.
Q: Are houses salaries higher in rural areas?
Generally, yes. Rural and suburban areas often require lower incomes to afford housing, but this comes with trade-offs like longer commutes, fewer amenities, and potential career limitations. For instance, a £35,000 salary might cover a mortgage in a small town but would struggle in a city center.
Q: How do mortgage rates impact houses salaries?
Higher interest rates increase monthly payments, effectively raising the houses salary threshold. A 1% rate hike can add £50–£100 to monthly mortgage costs on a £300,000 loan, meaning borrowers may need to earn £5,000–£10,000 more annually to maintain affordability.
Q: Do shared ownership schemes help achieve a houses salary?
Shared ownership allows buyers to purchase a percentage of a home (often 25–75%) and pay rent on the remainder, lowering the income needed to qualify. However, it restricts future sales and equity growth. For some, it’s a viable path to homeownership with a lower houses salary; for others, it’s a temporary solution.
Q: How has the houses salary changed since 2010?
It has risen significantly in most markets. Adjusting for inflation and property price growth, a houses salary in 2010 might have required £40,000–£50,000 in the UK; today, that figure is closer to £70,000–£100,000 in many regions. The gap is most pronounced in cities where wages haven’t kept pace with housing costs.
Q: What’s the biggest misconception about houses salaries?
The assumption that a houses salary is static or universal. It’s highly localized, tied to property markets, interest rates, and personal circumstances. What qualifies as a houses salary in Manchester won’t apply in Manchester’s suburbs, let alone in another country. Overestimating one’s earning potential relative to local housing costs is a common pitfall.
